



 Chat with AI
Exam 6: Sellers and Incentives

Exam 1: The Principles and Practice of Economics103 Questions
Exam 2: Economic Methods and Economic Questions94 Questions
Exam 3: Optimization: Doing the Best You Can94 Questions
Exam 4: Demand, supply, and Equilibrium185 Questions
Exam 5: Consumers and Incentives187 Questions
Exam 6: Sellers and Incentives261 Questions
Exam 7: Perfect Competition and the Invisible Hand251 Questions
Exam 8: Trade264 Questions
Exam 9: Externalities and Public Goods223 Questions
Exam 10: The Government in the Economy: Taxation and Regulation244 Questions
Exam 11: Markets for Factors of Production237 Questions
Exam 12: Monopoly295 Questions
Exam 13: Game Theory and Strategic Play199 Questions
Exam 14: Oligopoly and Monopolistic Competition264 Questions
Exam 15: Trade-Offs Involving Time and Risk147 Questions
Exam 16: The Economics of Information119 Questions
Exam 17: Auctions and Bargaining123 Questions
Exam 18: Social Economics111 Questions
Select questions type


The following table shows the total output produced by different numbers of workers in a shoe factory.
 -Refer to the table above.Which of the following statements is true about the marginal product of labor?
 (Multiple Choice)
4.8/5  (89)
(89) The figure below shows short-run average total cost curves for a firm under four different production technologies. Assume that there are only four different technologies that the firm could use.
 -Refer to the figure above.The long-run average total cost curve of the firm goes through points ________.
 (Multiple Choice)
4.8/5 (74)
(74) The total revenue earned from the sale of a good is ________.
(Multiple Choice)
4.8/5 (85)
(85) Which of the following statements is true of the marginal product of an input?
(Multiple Choice)
5.0/5 (82)
(82) A firm is seeing a $500 loss in the short run.The fixed cost of operation for this firm is $1,000.What is the best decision for this firm in the short run?
(Multiple Choice)
4.8/5 (99)
(99) The figure below shows cost curves of a firm in a competitive market. The firm always makes the choice to maximize its profit.
 -Refer to the figure above.If the market price of the product is $3.25,what is the firm's revenue?
 (Multiple Choice)
4.7/5 (89)
(89) The following graph shows the short-run production function of a firm.
 -Refer to the graph above.When does the "diminishing marginal returns to inputs" begin?
 (Multiple Choice)
4.9/5 (74)
(74) The following figure depicts the supply curve of a certain firm.
 -Refer to the figure above.If the elasticity of supply is 0.5 when the quantity changes from 100 to 150,what is the price at the quantity 100?
 (Multiple Choice)
4.8/5 (75)
(75) A firm has an average total cost of $50.If it sells 20 units of its product at $80 each,what is its profit?
(Multiple Choice)
4.9/5 (76)
(76) Which of the following statements is true in the short run?
(Multiple Choice)
4.9/5 (97)
(97) Which of the following examples best describes the concept of free entry?
(Multiple Choice)
4.9/5 (73)
(73) If a firm is maximizing profits in the short run at a level of output where
Average total cost > Price > Average variable cost,then the firm is ________.
(Multiple Choice)
4.8/5 (66)
(66) A firm sells 20 units of a good at a price of $5 per unit.If the average cost of production of the good equals $3 per unit,the firm's revenue is ________.
(Multiple Choice)
4.8/5 (90)
(90) The following figure depicts a firm's long-run average total cost and selected short-run average total cost curves.
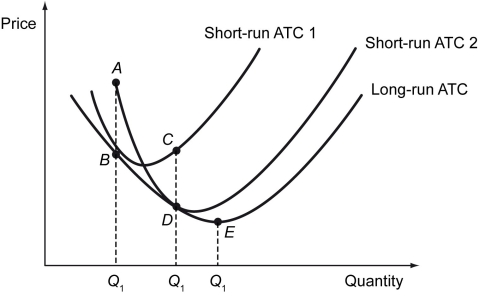 -Refer to the figure above.The firm is currently producing at point A.If it increases its employment of labor,it will move toward ________.
 (Multiple Choice)
4.8/5 (69)
(69) In the long run,a firm should exit from a market when ________.
(Multiple Choice)
4.8/5 (66)
(66) Scenario: A car repair shop hires workers and pays them the federal minimum wage of $7.25. The following table shows the marginal returns to each worker in terms of number of cars repaired.
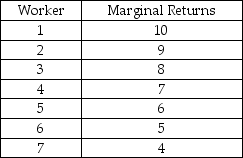 -Refer to the scenario above.If this firm hires 3 workers,how many cars in total can the shop repair per day?
 (Multiple Choice)
4.8/5 (78)
(78) Which of the following is true of the price elasticity of supply?
(Multiple Choice)
4.9/5 (78)
(78) If a small decrease in the price of a good decreases the quantity supplied to zero,the supply of the good is said to be ________.
(Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)