



 Chat with AI
Exam 6: Sellers and Incentives

Exam 1: The Principles and Practice of Economics103 Questions
Exam 2: Economic Methods and Economic Questions94 Questions
Exam 3: Optimization: Doing the Best You Can94 Questions
Exam 4: Demand, supply, and Equilibrium185 Questions
Exam 5: Consumers and Incentives187 Questions
Exam 6: Sellers and Incentives261 Questions
Exam 7: Perfect Competition and the Invisible Hand251 Questions
Exam 8: Trade264 Questions
Exam 9: Externalities and Public Goods223 Questions
Exam 10: The Government in the Economy: Taxation and Regulation244 Questions
Exam 11: Markets for Factors of Production237 Questions
Exam 12: Monopoly295 Questions
Exam 13: Game Theory and Strategic Play199 Questions
Exam 14: Oligopoly and Monopolistic Competition264 Questions
Exam 15: Trade-Offs Involving Time and Risk147 Questions
Exam 16: The Economics of Information119 Questions
Exam 17: Auctions and Bargaining123 Questions
Exam 18: Social Economics111 Questions
Select questions type


The long-run supply curve for a firm in a perfectly competitive industry is ________.
(Multiple Choice)
4.8/5  (75)
(75) The figure below shows cost curves of a firm in a competitive market. The firm always makes the choice to maximize its profit.
 -Refer to the figure above.If the market price of the product is $3.25,what is the firm's fixed cost?
 (Multiple Choice)
4.9/5 (83)
(83) Consider the following two scenarios:
i)The marginal product of a worker in a firm is 10 units.When an additional worker is employed,his marginal product is less than 10 units.
ii)The average total cost of a firm producing 10 units of output is $200.When it produces an additional unit,the average total cost increases to $300.
a)What is the difference between these scenarios?
b)What could be the reason behind both phenomena occurring?
c)Does specialization explain either of the two scenarios?
(Essay)
4.8/5 (88)
(88) The figure below shows the marginal cost (circles) and the average variable cost (crosses) of a firm in a competitive market. The firm always makes the choice to maximize its profit.
 -Refer to the figure above.If the market price of the product is $3,400,what is the firm's producer surplus?
 (Multiple Choice)
4.7/5 (78)
(78) A bakery that produces 100 loaves of bread has a variable cost of $50 and a fixed cost of $200.Calculate the total cost,average total cost,average variable cost,and average fixed cost of the bakery.
(Essay)
4.8/5 (86)
(86) The figure below shows the cost curves of a firm in a competitive market. The firm always makes the choice to maximize its profit.
 -Refer to the figure above.If the market price of the product is $1.50,the firm's profit maximizing output is ________ and its maximum profit is ________.
 (Multiple Choice)
4.9/5 (90)
(90) The output of a bakery is 250 loaves of bread when 10 workers are employed.If one more worker is hired,the total output increases to 275 loaves.Given that labor is the only variable input that the bakery uses and the market wage rate is $10,calculate the marginal cost when employment is increased from 10 to 11 workers.
(Essay)
4.8/5 (87)
(87) The figure below shows the marginal cost (circles) and the average variable cost (crosses) of a firm in a competitive market. The firm always makes the choice to maximize its profit.
-Refer to the figure above.If the market price of the product is $5,000,what is the firm's producer surplus?
-Refer to the figure above.If the market price of the product is $5,000,what is the firm's producer surplus? (Multiple Choice)
4.8/5 (84)
(84) The following table shows the total output, number of workers employed, variable costs, and fixed costs of a firm.
 -Refer to the table above.Suppose the only variable input that the firm uses is labor.What is the wage paid to a worker in the firm?
 (Multiple Choice)
4.8/5 (90)
(90) If price is greater than average total cost for a perfectly competitive firm,________.
(Multiple Choice)
5.0/5 (69)
(69) The following figure shows the cost curves on a firm that operates in a competitive market. Assume that all the firms in this market have identical cost structure.
 -Refer to the graph above.Which of the following graphs correctly represents this competitive market's demand and supply in the short run?
 (Multiple Choice)
4.8/5 (82)
(82) A firm sells 30 units of its product at a price of $5 per unit.It incurs a fixed cost of $100 and a variable cost of $20.The firm's profit is ________.
(Multiple Choice)
4.9/5 (90)
(90) Which of the following is true of a good with a perfectly elastic supply?
(Multiple Choice)
5.0/5 (74)
(74) Which of the following is NOT an element of a seller's decision-making process in a perfectly competitive market?
(Multiple Choice)
4.9/5 (83)
(83) Which of the following is true for a firm that enjoys economies of scale?
(Multiple Choice)
4.9/5 (84)
(84) The following figure depicts the supply curve of a certain firm.
 -Refer to the figure above.If the elasticity of supply is 0,2630 when the price changes from 30 to 70,what is the quantity at the price of $30?
 (Multiple Choice)
4.9/5 (85)
(85) The following table shows the total output, variable costs, fixed costs, total costs, average total costs, and marginal costs of a firm, with some cells in the table intentionally left blank.
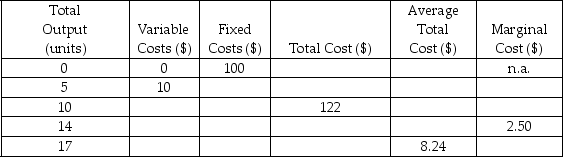 -Refer to the table above.What is the marginal cost when the firm produces 5 units of output?
 (Multiple Choice)
4.9/5 (69)
(69) ________ occur when average total cost falls as the quantity produced increases.
(Multiple Choice)
4.7/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)