



 Chat with AI
Exam 6: Sellers and Incentives

Exam 1: The Principles and Practice of Economics103 Questions
Exam 2: Economic Methods and Economic Questions94 Questions
Exam 3: Optimization: Doing the Best You Can94 Questions
Exam 4: Demand, supply, and Equilibrium185 Questions
Exam 5: Consumers and Incentives187 Questions
Exam 6: Sellers and Incentives261 Questions
Exam 7: Perfect Competition and the Invisible Hand251 Questions
Exam 8: Trade264 Questions
Exam 9: Externalities and Public Goods223 Questions
Exam 10: The Government in the Economy: Taxation and Regulation244 Questions
Exam 11: Markets for Factors of Production237 Questions
Exam 12: Monopoly295 Questions
Exam 13: Game Theory and Strategic Play199 Questions
Exam 14: Oligopoly and Monopolistic Competition264 Questions
Exam 15: Trade-Offs Involving Time and Risk147 Questions
Exam 16: The Economics of Information119 Questions
Exam 17: Auctions and Bargaining123 Questions
Exam 18: Social Economics111 Questions
Select questions type


The figure below shows the cost curves of a firm in a competitive market. The firm always makes the choice to maximize its profit.
 -Refer to the figure above.The short-run supply curve of the firm is ________.
 (Multiple Choice)
4.7/5  (94)
(94) Which of the following business is most likely to have the largest amount (or value)of fixed input?
(Multiple Choice)
4.9/5 (85)
(85) The figure below shows the cost curves of a firm in a competitive market. The firm always makes the choice to maximize its profit.
-Refer to the figure above.If the market price of the product is $2.00,the firm's profit maximizing output is ________ and its maximum profit is ________.
-Refer to the figure above.If the market price of the product is $2.00,the firm's profit maximizing output is ________ and its maximum profit is ________. (Multiple Choice)
4.8/5 (90)
(90) Scenario: Emily runs a small coffee roasting company. Labor is the only variable input. Output depends on the size of the coffee roaster (a fixed input) that she rents. She can fit only one roaster in her shop. The table below summarizes possible output per month depending on the number of workers employed and the size of a roaster Emily rents. Assume that workers cannot produce any quantity other than ones shown in the table. So, for example, if Emily wants to produce 3,000 kg per month with a small roaster, then she would have to hire 3 workers and produce 4,000 kg. Emily pays $2,400 per month to each worker she employs. Monthly rental prices are $400 for a small roaster, $650 for a medium roaster, and $880 for a large roaster. In addition, Emily's opportunity cost of being an entrepreneur is $12,000 per month because, with her MBA degree, she could be working for a management consulting firm. You should consider this as a part of the fixed cost.
 -Refer to the scenario above.If Emily wants to produce 2,400 kg per month,then the minimum total average cost is ________,which is achieved by renting a ________ roaster.
 (Multiple Choice)
4.8/5 (87)
(87) A firm is interested in entering a perfectly competitive market where all its competitors have cost structures identical to this firm and are earning positive economic profits.Using graphs,comment on the long-run profitability of the firms in this scenario.
(Essay)
4.8/5 (86)
(86) ________ are costs that,once committed,can never be recovered and should not affect current and future production costs.
(Multiple Choice)
4.9/5 (70)
(70) Which of the following statements is true in the long run?
(Multiple Choice)
4.9/5 (76)
(76) When the marginal cost curve lies below the average cost curve,________.
(Multiple Choice)
4.8/5 (82)
(82) In a competitive industry,some firms earn positive economic profits,while some earn zero economic profit in the long run because ________.
(Multiple Choice)
5.0/5 (80)
(80) In a perfectly competitive market,an individual seller cannot change the price of his product.This is because ________.
(Multiple Choice)
4.7/5 (92)
(92) Firm A and Firm B produce the same goods but with different inputs.If the inputs used by Firm A are more easily available than the inputs used by Firm B,then which of the following statements is true?
(Multiple Choice)
4.8/5 (59)
(59) The following table shows the total output, number of workers employed, variable costs, and fixed costs of a firm.
 -Refer to the table above.What is the average variable cost of producing 86 units of the good?
 (Multiple Choice)
4.7/5 (88)
(88) The following table shows the total output of bread produced by different numbers of workers in a bakery.
 -Refer to the table above.Diminishing marginal returns begin to occur when ________.
 (Multiple Choice)
4.8/5 (75)
(75) Which of the following statements is true in the long run?
(Multiple Choice)
4.9/5 (80)
(80) The figure below shows cost curves of a firm in a competitive market. The firm always makes the choice to maximize its profit.
 -Refer to the figure above.If the market price of the product is $3.25,what is the firm's total cost?
 (Multiple Choice)
4.9/5 (75)
(75) The following table shows the total output, variable costs, fixed costs, total costs, average total costs, and marginal costs of a firm, with some cells in the table intentionally left blank.
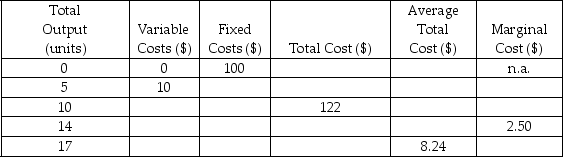 -Refer to the table above.What is the total cost of this firm when it doesn't produce any output?
 (Multiple Choice)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)