



 Chat with AI
Exam 6: Sellers and Incentives

Exam 1: The Principles and Practice of Economics103 Questions
Exam 2: Economic Methods and Economic Questions94 Questions
Exam 3: Optimization: Doing the Best You Can94 Questions
Exam 4: Demand, supply, and Equilibrium185 Questions
Exam 5: Consumers and Incentives187 Questions
Exam 6: Sellers and Incentives261 Questions
Exam 7: Perfect Competition and the Invisible Hand251 Questions
Exam 8: Trade264 Questions
Exam 9: Externalities and Public Goods223 Questions
Exam 10: The Government in the Economy: Taxation and Regulation244 Questions
Exam 11: Markets for Factors of Production237 Questions
Exam 12: Monopoly295 Questions
Exam 13: Game Theory and Strategic Play199 Questions
Exam 14: Oligopoly and Monopolistic Competition264 Questions
Exam 15: Trade-Offs Involving Time and Risk147 Questions
Exam 16: The Economics of Information119 Questions
Exam 17: Auctions and Bargaining123 Questions
Exam 18: Social Economics111 Questions
Select questions type


Scenario: Jenna makes homemade pastries. Her fixed input in the short run is the mixer. In the long run, she can choose a spatula, hand mixer, or a stand mixer. The following table shows the short-run fixed cost (F.Cand variable cost (VC) of weekly production using each different level of the capital input.
 -Refer to the scenario above.If Jenna wants to make 10 pastries per week,which level of capital input should she choose?
 (Multiple Choice)
4.8/5  (79)
(79) The figure below shows the supply and the demand for a good (left) and the cost curves of an individual firm in this market (right). Assume that all firms in this market, including the potential entrants, have identical cost curves. Initially, the market is in equilibrium at point A.
 -Refer to the figure above.As firms enter or exit,the market will tend toward the long-run equilibrium,where each firm earns ________ at the price ________.
 (Multiple Choice)
4.9/5 (82)
(82) A firm's production process does NOT exhibit diminishing returns.The returns to additional units of input for this firm happens to be constant.The marginal cost curve of this firm is ________.
(Multiple Choice)
4.8/5 (88)
(88) Scenario: Jenna makes homemade pastries. Her fixed input in the short run is the mixer. In the long run, she can choose a spatula, hand mixer, or a stand mixer. The following table shows the short-run fixed cost (F.Cand variable cost (VC) of weekly production using each different level of the capital input.
-Refer to the scenario above.If Jenna wants to make 500 pastries per week,which level of capital input should she choose?
-Refer to the scenario above.If Jenna wants to make 500 pastries per week,which level of capital input should she choose? (Multiple Choice)
4.8/5 (70)
(70) Which of the following best describes the long run for a firm?
(Multiple Choice)
4.9/5 (83)
(83) The figure below shows short-run average total cost curves for a firm under four different production technologies. Assume that there are only four different technologies that the firm could use.
 -Refer to the figure above.The minimum average total cost to produce a quantity between QD and QF is achieved by using technology ________.
 (Multiple Choice)
4.8/5 (74)
(74) Scenario: According to New York Department of State, Division of Licensing Services, "The practice of 'cosmetology' means providing service to the hair, head, face, neck, or scalp of a human being, including but not limited to shaving, trimming, and cutting the hair or beard either by hand or mechanical appliances and the application of antiseptics, powders, oils, clays, lotions or applying tonics to the hair, head, or scalp, and in addition includes providing, for a fee or any consideration or exchange, whether direct or indirect, services for the application of dyes, reactive chemicals, or other preparations to alter the color or to straighten, curl, or alter the structure of the hair of a human being." You must acquire a license to be a beautician to offer any of the services described above in New York State, as in many other states. Many aspiring beauticians enroll in accredited cosmetology schools to complete a 1,000-hour approved course of study and to pass both the New York State written and practical examinations to get a license to operate.
-Refer to the scenario above.Which condition of a perfectly competitive market could most directly be hampered by the licensing requirement?
(Multiple Choice)
4.8/5 (66)
(66) What conditions characterize the sellers' side in a perfectly competitive market?
(Essay)
4.8/5 (89)
(89) Consider the following graph,which depicts a competitive market.The producer surplus in this market is equal to ________.
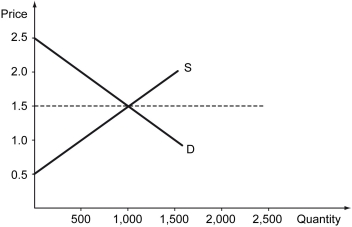
(Multiple Choice)
4.9/5 (94)
(94) Which of the following is an example of diminishing marginal returns?
(Multiple Choice)
4.8/5 (89)
(89) Scenario: The figure below shows the supply and the demand for a good (left) and the cost curves of an individual firm in this market (right). Initially, all firms in this market have identical cost curves MC₁ and ATC₁, and the market is in equilibrium at point A. Subsequently, a new production technology has been developed for this product. Some of the existing firms as well as some new firms have adopted the new technology, and their cost curves are MC₂ and ATC₂.
 -Refer to the figure above.Suppose that,due to firm entries,the supply curve has shifted so that the equilibrium price has reached $1.50.Subsequently,further entries lower the equilibrium price to $0.90.At this point,________.
 (Multiple Choice)
5.0/5 (75)
(75) In the long run,a firm should remain in a perfectly competitive industry if ________.
(Multiple Choice)
5.0/5 (79)
(79) The following table shows the total output produced by different numbers of workers in a shoe factory.
 -Refer to the table above.What is the marginal product of the third worker?
 (Multiple Choice)
4.8/5 (75)
(75) A firm is seeing a $500 loss in the short run.The fixed cost of operation for this firm is $200.What is the best decision for this firm in the short run?
(Multiple Choice)
4.9/5 (73)
(73) The following table shows the total output, number of workers employed, variable costs, and fixed costs of a firm.
 -Refer to the table above.What is the average total cost of producing 160 units of the good?
 (Multiple Choice)
4.7/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)