



 Chat with AI
Exam 11: Managing Transaction Exposure

Exam 1: Multinational Financial Management: An Overview79 Questions
Exam 2: International Flow of Funds74 Questions
Exam 3: International Financial Markets101 Questions
Exam 4: Exchange Rate Determination69 Questions
Exam 5: Currency Derivatives161 Questions
Exam 6: Government Influence on Exchange Rates116 Questions
Exam 7: International Arbitrage and Interest Rate Parity92 Questions
Exam 8: Relationships among Inflation, Interest Rates, and Exchange Rates59 Questions
Exam 9: Forecasting Exchange Rates84 Questions
Exam 10: Measuring Exposure to Exchange Rate Fluctuations82 Questions
Exam 11: Managing Transaction Exposure81 Questions
Exam 12: Managing Economic Exposure and Translation Exposure58 Questions
Exam 13: Direct Foreign Investment53 Questions
Exam 14: Multinational Capital Budgeting60 Questions
Exam 15: International Corporate Governance and Control72 Questions
Exam 16: Country Risk Analysis57 Questions
Exam 17: Multinational Cost of Capital and Capital Structure68 Questions
Exam 18: Long-Term Debt Financing53 Questions
Exam 19: Financing International Trade66 Questions
Exam 20: Short-Term Financing49 Questions
Exam 21: International Cash Management50 Questions
Select questions type


Many MNCs use selective hedging, in which they consider each type of transaction separately.
(True/False)
4.8/5  (83)
(83) The tradeoff when considering alternative call options to hedge a currency position is that an MNC can obtain a call option with a higher exercise price, but would have to pay a higher premium.
(True/False)
4.8/5 (76)
(76) Money Corp. frequently uses a forward hedge to hedge its Malaysian ringgit (MYR) receivables. For the next month, Money has identified its net exposure to the ringgit as being MYR1,500,000. The 30-day forward rate is $.23. Furthermore, Money's financial center has indicated that the possible values of the Malaysian ringgit at the end of next month are $.20 and $.25, with probabilities of .30 and .70, respectively. Based on this information, the revenue from hedging minus the revenue from not hedging receivables is____.
(Multiple Choice)
5.0/5 (74)
(74) In a forward hedge, if the forward rate is an accurate predictor of the future spot rate, the real cost of hedging payables will be:
(Multiple Choice)
4.9/5 (80)
(80) A ____ is not normally used for hedging long-term transaction exposure.
(Multiple Choice)
4.7/5 (83)
(83) When comparing the forward hedge to the options hedge, the MNC can easily determine which hedge is more desirable, because the cost of each hedge can be determined with certainty.
(True/False)
4.7/5 (85)
(85) The hedging of a foreign currency for which no forward contract is available with a highly correlated currency for which a forward contract is available is referred to as cross-hedging.
(True/False)
4.8/5 (92)
(92) The exact cost of hedging with call options (as measured in the text) is not known with certainty at the time that the options are purchased.
(True/False)
4.9/5 (86)
(86) A forward contract hedge is very similar to a futures contract hedge, except that ____ contracts are commonly used for ____ transactions.
(Multiple Choice)
4.8/5 (81)
(81) Assume zero transaction costs. If the 90-day forward rate of the euro is an accurate estimate of the spot rate 90 days from now, then the real cost of hedging payables will be:
(Multiple Choice)
4.9/5 (89)
(89) If Salerno Inc. desires to lock in a minimum rate at which it could sell its net receivables in Japanese yen but wants to be able to capitalize if the yen appreciates substantially against the dollar by the time payment arrives, the most appropriate hedge would be:
(Multiple Choice)
4.7/5 (96)
(96) The real cost of hedging payables with a forward contract equals:
(Multiple Choice)
4.9/5 (67)
(67) To hedge a contingent exposure, in which an MNC's exposure is contingent on a specific event occurring, the appropriate hedge would be a(n) ____ hedge.
(Multiple Choice)
4.7/5 (90)
(90) Since forward contracts are easy to use for hedging, any exposure to exchange rate movements should be hedged.
(True/False)
4.7/5 (84)
(84) Futures, forward, and money market hedges all lock into a certain price to be received from hedging a receivable. For a currency option hedge with a put option, however, the exact amount received is not known until the option is (or is not) exercised.
(True/False)
4.9/5 (82)
(82) Assume that Kramer Co. will receive SF800,000 in 90 days. Today's spot rate of the Swiss franc is $.62, and the 90-day forward rate is $.635. Kramer has developed the following probability distribution for the spot rate in 90 days:
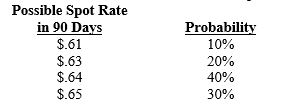 The probability that the forward hedge will result in more dollars received than not hedging is:
(Multiple Choice)
4.8/5 (80)
(80) Exhibit 11-1
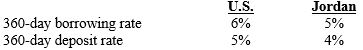 -Refer to Exhibit 11-1. Pablo Corp. will need 150,000 Jordanian dinar (JOD) in 360 days. The current spot rate of the dinar is $1.48, while the 360-day forward rate is $1.46. What is Pablo's cost from implementing a money market hedge (assume Pablo does not have any excess cash)?
 (Multiple Choice)
4.9/5 (75)
(75) Foghat Co. has 1,000,000 euros as receivables due in 30 days, and is certain that the euro will depreciate substantially over time. Assuming that the firm is correct, the ideal strategy is to:
(Multiple Choice)
4.9/5 (79)
(79) The price at which a currency put option allows the holder to sell a currency is called the settlement price.
(True/False)
4.7/5 (64)
(64) A ____ involves an exchange of currencies between two parties, with a promise to re-exchange currencies at a specified exchange rate and future date.
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)