Multiple Choice
Assume that Kramer Co. will receive SF800,000 in 90 days. Today's spot rate of the Swiss franc is $.62, and the 90-day forward rate is $.635. Kramer has developed the following probability distribution for the spot rate in 90 days: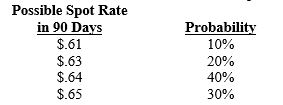
The probability that the forward hedge will result in more dollars received than not hedging is:
A) 10 percent.
B) 20 percent.
C) 30 percent.
D) 50 percent.
E) 70 percent.
Correct Answer:

Verified
Correct Answer:
Verified
Q5: A put option essentially represents two swaps
Q20: If Salerno Inc. desires to lock in
Q24: Futures, forward, and money market hedges all
Q25: Foghat Co. has 1,000,000 euros as receivables
Q59: The price at which a currency put
Q70: Since forward contracts are easy to use
Q71: The real cost of hedging payables with
Q72: A _ involves an exchange of currencies
Q73: To hedge a contingent exposure, in which
Q77: Exhibit 11-1<br> <img src="https://d2lvgg3v3hfg70.cloudfront.net/TB2125/.jpg" alt="Exhibit 11-1