



 Chat with AI
Exam 9: Perfect Competition

Exam 1: Foundations of Economics100 Questions
Exam 1: Extension: Understanding Graphs27 Questions
Exam 2: Markets and Economies104 Questions
Exam 3: Demand116 Questions
Exam 4: Supply118 Questions
Exam 5: Market Equilibrium118 Questions
Exam 6: Elasticity126 Questions
Exam 7: Consumer Behavior104 Questions
Exam 8: Production Costs125 Questions
Exam 9: Perfect Competition117 Questions
Exam 10: Market Power102 Questions
Exam 11: Factor Markets105 Questions
Exam 12: Market Failure and Government Failure82 Questions
Exam 13: Measuring an Economys Performance103 Questions
Exam 14: Aggregate Demand and Aggregate Supply105 Questions
Exam 15: Fiscal Policy105 Questions
Exam 16: Money and Banking74 Questions
Exam 17: Monetary Policy103 Questions
Exam 18: Economic Growth and Development49 Questions
Exam 19: International Trade and Finance110 Questions
Select questions type


The marginal cost curve above the minimum of average variable cost serves as the perfectly competitive firm's _____ curve.
(Multiple Choice)
4.8/5  (86)
(86) Why is a firm willing to produce a quantity that earns zero economic profits in the long run?
(Essay)
4.9/5 (84)
(84) The profit that is earned by a firm in a perfectly competitive market is the:
(Multiple Choice)
4.9/5 (75)
(75) In perfectly competitive markets, the incentives for _____ help firms achieve efficiency in production.
(Multiple Choice)
4.9/5 (85)
(85) In a perfectly competitive market, the market price is $3.50, and firms are producing 100 units. At a quantity of 100 units, average total cost is $4, and average variable cost is $3. In the long run, price will:
(Multiple Choice)
5.0/5 (74)
(74) A profit-maximizing firm in a perfectly competitive market is currently producing 1,000 units. The marginal cost of the 1,000th unit is $4, and the average total cost of producing 1,000 units is $1 per unit. Which of the following statements is NOT true?
(Multiple Choice)
4.8/5 (73)
(73) Which of the following is NOT a reason that firms in a perfectly competitive market are price takers?
(Multiple Choice)
4.9/5 (76)
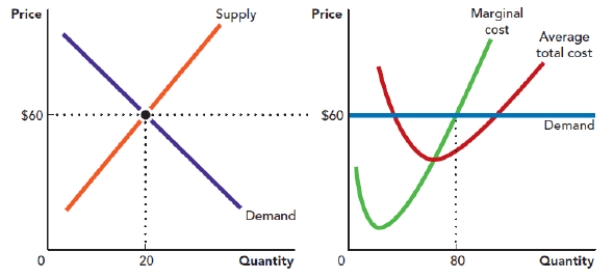
(76) Use the figure A Perfectly Competitive Market in the Short Run IV. If the price in this market persists, what will happen in the long run?
Figure: A Perfectly Competitive Market in the Short Run IV
(Multiple Choice)
4.9/5 (79)
(79) A firm in a perfectly competitive market produces an optimal quantity when it produces the quantity where marginal:
(Multiple Choice)
4.8/5 (78)
(78) What happens to firms that do not use the inputs and methods that minimize their production costs in a perfectly competitive market in the long run?
(Multiple Choice)
4.7/5 (84)
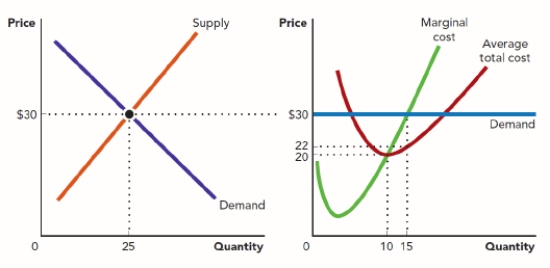
(84) Use the figure A Perfectly Competitive Market and a Firm in That Market's Cost Curves. Explain why this market is not in long-run equilibrium, and then explain the process by which this market will return to long-run equilibrium.
Figure: A Perfectly Competitive Market and a Firm in that Market's Cost Curves
(Essay)
5.0/5 (71)
(71) The market for taxi services in a major metropolitan area has thousands of taxis and thousands of potential customers. Taxi services are identical, and buyers have full information about pricing. To become a taxi operator in this city requires a permit, which is difficult and expensive to obtain. Which feature of a perfectly competitive market is violated?
(Multiple Choice)
4.7/5 (73)
(73) The demand curve for a perfectly competitive firm's product is the same as the:
(Multiple Choice)
4.8/5 (74)
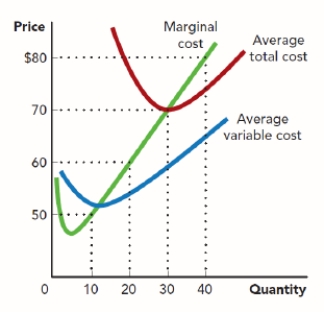
(74) . Use the figure Costs for a Firm. What price makes this firm willing to operate in the short run but not in the long-run?
Figure: Costs for a Firm
(Multiple Choice)
4.8/5 (70)
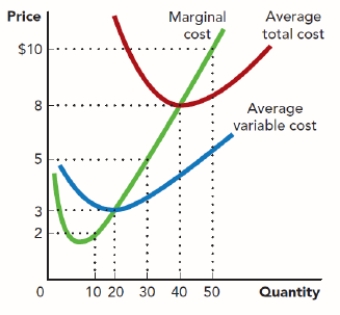
(70) . Use the figure Costs for a Firm II. What price and quantity combination are part of this firm's long-run supply curve?
Figure: Costs for a Firm II
(Multiple Choice)
4.8/5 (95)
(95) In a perfectly competitive market the market price is $4, and firms are producing 100 units. At a quantity of 100 units, average total cost is $4, and average variable cost is $3. In the long run, price will:
(Multiple Choice)
4.8/5 (77)
(77) Suppose that Magma Motor Company has total revenue of $400,000, fixed costs of $100,000, and variable costs of $200,000. If Magma Motor company is known to be in a perfectly competitive market, which of the following is true?
(Multiple Choice)
4.7/5 (78)
(78) How many buyers and sellers are there in a perfectly competitive market?
(Multiple Choice)
4.8/5 (81)
(81) Which of the following is essential in perfect competition?
(Multiple Choice)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)