



 Chat with AI
Exam 10: Market Power

Exam 1: Foundations of Economics100 Questions
Exam 1: Extension: Understanding Graphs27 Questions
Exam 2: Markets and Economies104 Questions
Exam 3: Demand116 Questions
Exam 4: Supply118 Questions
Exam 5: Market Equilibrium118 Questions
Exam 6: Elasticity126 Questions
Exam 7: Consumer Behavior104 Questions
Exam 8: Production Costs125 Questions
Exam 9: Perfect Competition117 Questions
Exam 10: Market Power102 Questions
Exam 11: Factor Markets105 Questions
Exam 12: Market Failure and Government Failure82 Questions
Exam 13: Measuring an Economys Performance103 Questions
Exam 14: Aggregate Demand and Aggregate Supply105 Questions
Exam 15: Fiscal Policy105 Questions
Exam 16: Money and Banking74 Questions
Exam 17: Monetary Policy103 Questions
Exam 18: Economic Growth and Development49 Questions
Exam 19: International Trade and Finance110 Questions
Select questions type


Which one of the following statements is NOT true for a monopolist?
(Multiple Choice)
4.9/5  (89)
(89) Which of the following is NOT a legal barrier to entry in a market?
(Multiple Choice)
4.8/5 (82)
(82) By charging each customer according to its maximum willingness to pay, a perfectly price-discriminating monopolist leads to zero _____ in the market.
(Multiple Choice)
4.9/5 (73)
(73) Economies of scale refers to the situation where an increase in the output of a firm leads to a decrease in:
(Multiple Choice)
4.8/5 (71)
(71) A perfectly competitive market produces a _____ level of output and charges a _____ price compared to a monopoly market.
(Multiple Choice)
4.9/5 (93)
(93) When the long-run average total costs of an industry decline with an increase in output, its market is:
(Multiple Choice)
4.9/5 (76)
(76) Economists use the tools of _____ theory to study behavior among economic agents whose decisions are interdependent.
(Multiple Choice)
4.8/5 (65)
(65) Suppose that a movie theater has a pricing policy where it charges a lower rate to students and a higher rate to everyone else. This is an example of:
(Multiple Choice)
4.8/5 (76)
(76) Which one of the following statements is FALSE about a firm in a monopolistically competitive market at its long-run equilibrium?
(Multiple Choice)
4.9/5 (83)
(83) A group of producers that collude to restrict the quantity of output to maximize profits is called a:
(Multiple Choice)
4.9/5 (84)
(84) Suppose that a firm in a monopolistically competitive market is operating at its profit-maximizing point in the long run. The firm has a total revenue of $800, its marginal revenue is $10, and it sells 50 units of output. Given this, we can conclude that the average total cost of the firm is _____ and the marginal cost of production is:
(Multiple Choice)
4.9/5 (74)
(74) Because a monopolist charges a price that is ____ than marginal cost, a monopoly market allocates _____ resources to the production of a good than is socially optimal.
(Multiple Choice)
4.8/5 (97)
(97) Why is the marginal revenue for a monopolist different from the price or the average revenue? Given this, show why the profit-maximizing quantity for a monopolist is different from the socially optimal output. Provide a graph for your explanation.
(Essay)
4.9/5 (91)
(91) Flying Carpet Airlines operates the only early Monday morning flight from Stewarton, which arrives at Colberton at 9 a.m. Through market research, it discovers that the flight is taken by two groups of customers - busy business executives who must reach Colberton on Monday morning by 9 a.m. and students who have a more elastic demand and do not care about when they arrive. Given that Flying Carpet has a monopoly on this early morning flying route, what is the best way that it can price tickets to maximize profits?
(Essay)
4.7/5 (96)
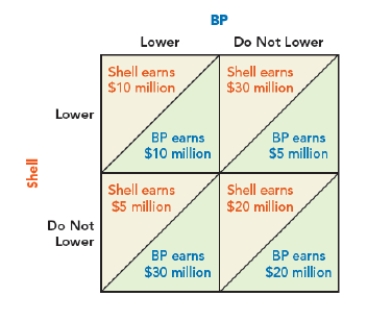
(96) Use Figure: Payoff Matrix Shell & BP I. The figure shows the payoff matrix where the hypothetical daily profits of BP and Shell (in millions of dollars) depend on each other's decision about whether to lower prices. Based on the payoffs, BP's dominant strategy is _____ the price, and Shell's dominant strategy is _____ the price.
Figure: Payoff Matrix Shell & BP I
(Multiple Choice)
4.7/5 (82)
(82) Suppose that a firm in a monopolistically market charges $8 for its good and sells 100 units of output in the long-run. Given this, we can conclude that the total cost of production for the firm is _____ and the average cost of production is:
(Multiple Choice)
4.9/5 (66)
(66) Relative to a perfectly competitive market, a monopolist produces a_____ level of output and charges a _____ price.
(Multiple Choice)
4.8/5 (86)
(86) Suppose that a monopolist is operating at its profit-maximizing point by charging a price of $18 and selling 50 units of output. If the marginal revenue of the firm is $10 and the average total cost is $12, then the firm's marginal cost is _____, and the total profit is:
(Multiple Choice)
4.8/5 (80)
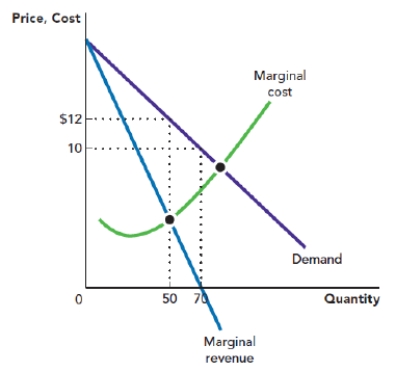
(80) Use Figure: Profit-Maximizing Quantity and Price. The figure depicts the demand curve, marginal revenue curve, and marginal cost curve that are facing a monopolist. Assume that the monopolist is operating at its profit-maximizing point. If the total profit of the monopolist is $200, then the average total cost of production is:
Figure: Profit-Maximizing Quantity and Price
(Multiple Choice)
4.7/5 (76)
(76) Which of the following can give rise to economies of scale for a firm?
(Multiple Choice)
4.8/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)