



 Chat with AI
Exam 21: Accounting Changes

Exam 12: Financial Liabilities and Provisions78 Questions
Exam 13: Financial Instruments: Long-Term Debt74 Questions
Exam 14: Shareholders Equity181 Questions
Exam 15: Financial Instruments: Complex Debt and Equity135 Questions
Exam 16: Corporate Income Tax122 Questions
Exam 17: Tax Losses98 Questions
Exam 18: Leases234 Questions
Exam 19: Post-Employment Benefits92 Questions
Exam 20: Earnings Per Share153 Questions
Exam 21: Accounting Changes157 Questions
Exam 22: Financial Statement Analysis165 Questions
Select questions type


Revised estimates of the useful life or residual value of a depreciable asset are examples of a change in accounting principle.
(True/False)
4.9/5  (86)
(86) A change from an accelerated depreciation method to the straight-line depreciation method should be accounted for as a:
(Multiple Choice)
4.8/5 (88)
(88) Following are five separate and completely independent cases:
CASE A: A $700 item was excluded incorrectly from the ending inventory; the related purchase was not recorded.
CASE B: A $200 item was included incorrectly in the ending inventory; the related purchase was
recorded.
CASE C: A $900 item was included incorrectly in the ending inventory; the related purchase was not recorded.
CASE D: A $500 item was excluded incorrectly from ending inventory; the related purchase was recorded.
CASE E: The beginning inventory was Overstated $400.
Enter dollar amounts where appropriate in the following tabulation to indicate the effect on the financial statements of each of the items given above (disregard income tax). 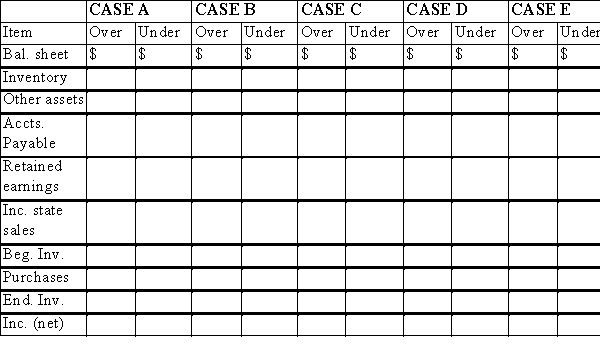
(Essay)
4.9/5 (73)
(73) A retrospectively applied change in accounting policy relating to fixed assets where a company changes from the straight-line amortization method to the double-declining balance method would result in a decrease to opening retained earnings.
(True/False)
4.8/5 (59)
(59) A change in an estimate, which was not determined reasonable (i.e., not in good faith)to a good faith estimate, is accounted for as an accounting error.
(True/False)
4.9/5 (87)
(87) An understatement of ending inventory will result in a credit to Future Income Taxes.
(True/False)
4.8/5 (85)
(85) A change in the salvage value of an asset depreciated on a straight-line basis and arising because additional information has been obtained is:
(Multiple Choice)
4.8/5 (76)
(76) Both IFRS and ASPE require note disclosures pertaining to accounting standards not yet in effect.
(True/False)
4.8/5 (62)
(62) A firm changed from completed contract to percentage of completion for revenue recognition on long-term construction contracts in 20x7.This change had the following effects on earnings: Increase in earnings 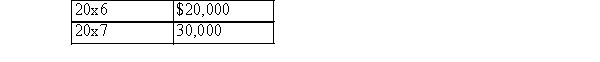 All years retained earnings balances before 20x6 100,000
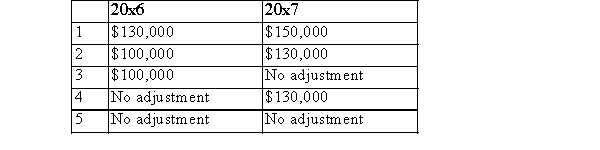
By what amounts are the beginning retained earnings balances for 20x6 and 20x7 adjusted, if the 20x6 and 20x7 statements are shown comparatively.
All years retained earnings balances before 20x6 100,000
By what amounts are the beginning retained earnings balances for 20x6 and 20x7 adjusted, if the 20x6 and 20x7 statements are shown comparatively. (Multiple Choice)
4.9/5 (72)
(72) Depreciation expense for the most recent fiscal year on equipment purchased a few years ago is $10,000.The balance sheet at the end of the same year disclosed the following: 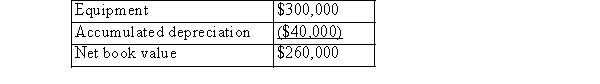 The asset is not expected to have a salvage value and the firm depreciates the asset on the straight-line basis.In March of the next year (the year of change), the firm decided to reduce the original total useful life 20% and that a salvage value of $30,000 is a reasonabl estimate.What is depreciation in the year of the change?
 (Multiple Choice)
4.9/5 (77)
(77) A misstatement of opening inventory is an example of a counterbalancing error.
(True/False)
4.8/5 (70)
(70) If a corporation changes from reporting investments on the cost basis to reporting on the equity basis, the prospective approach of reporting must be used.
(True/False)
4.8/5 (73)
(73) An overstatement of opening inventory entails an overstatement of Cost of Goods Sold in the current period.
(True/False)
5.0/5 (78)
(78) Failure to record depreciation expense in one-year results in what is usually called a counterbalancing error.
(True/False)
4.9/5 (83)
(83) Which of the following changes would be accounted for using the approach of a retrospective approach without restatement?
(Multiple Choice)
4.9/5 (76)
(76) At the end of the accounting year, December 31, 20x4, adjusting entries were not made for wages that had been earned but not yet paid, $1,800, and rent revenue of $1,400 that had been earned but not yet collected.As a consequence, the 20x4 amount of pre-tax earnings was:
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)