



 Chat with AI
Exam 17: Tax Losses

Exam 12: Financial Liabilities and Provisions78 Questions
Exam 13: Financial Instruments: Long-Term Debt74 Questions
Exam 14: Shareholders Equity181 Questions
Exam 15: Financial Instruments: Complex Debt and Equity135 Questions
Exam 16: Corporate Income Tax122 Questions
Exam 17: Tax Losses98 Questions
Exam 18: Leases234 Questions
Exam 19: Post-Employment Benefits92 Questions
Exam 20: Earnings Per Share153 Questions
Exam 21: Accounting Changes157 Questions
Exam 22: Financial Statement Analysis165 Questions
Select questions type


AG's taxable income for the first five years was as follows: 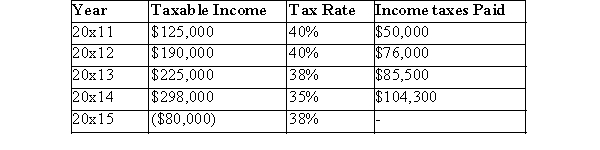 Calculate the tax recovery in 20x15.
Free
(Essay)
4.7/5  (91)
(91) Correct Answer: Verified
Please see the following table: 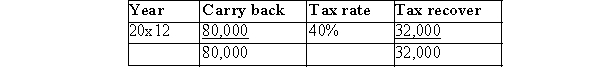
CJM provided the following data related to income tax allocation: 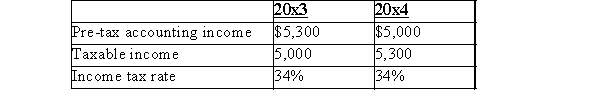 The deferred income tax account showed a zero balance at the start of 2013.There was only one temporary difference, an expense, which was deductible for tax purposes in 2013, but was recorded for accounting purposes in 2014.There are no carry backs or carry forwards and no originating temporary differences in 2014.The journal entry to record the income tax consequences for 2014 would include a:
Free
(Multiple Choice)
4.8/5 (93)
(93) Correct Answer:Verified
VerifiedC
All of the following are true regarding loss carry forwards except:
Free
(Multiple Choice)
4.7/5 (62)
(62) Correct Answer:Verified
VerifiedA
The recovery of income tax expense is credited to income tax expense (recovery)account.
(True/False)
4.9/5 (78)
(78) The maximum number of years a tax loss can be carried forward is:
(Multiple Choice)
4.8/5 (75)
(75) In the year in which a tax loss is incurred, the tax loss must equal the net loss reported on the company's financial statements.
(True/False)
4.8/5 (81)
(81) Under current law, at the end of the year of loss or anytime during the next 15 years, a company may select to either carry back or carry forward-only the loss.
(True/False)
4.9/5 (91)
(91) VB Ltd.provided you with the following information: 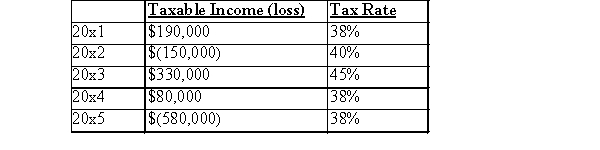 There are no temporary differences.The deferred income tax benefit of the loss carry forward was set up in 2015 as the probability of realization was greater than 50%.In 2016 it was determined that the probability of realization was less than 50%.What would be th carrying amount of the deferred income tax benefit-loss carry forward on the balance sheet at the end of 2016?
 (Multiple Choice)
4.8/5 (78)
(78) XYZ Inc.is a publicly traded company.At the start of the current year, the company had tax loss carry forwards in the amount of $500,000.This amount increased by $100,000 during the year, due to a change in estimate of the company's future earnings targets.The tax rate for the current year is 25%.The enacted tax rate for future years is 20%.The company uses a valuation allowance account to track its tax loss carry forwards.Which of the following correctly describes the balances in XYZ's internal records at the end of the current year?
(Multiple Choice)
4.9/5 (83)
(83) There is some question as to whether there should be early recognition of the deferred benefit of a loss carry forward.Discuss.
(Essay)
4.9/5 (82)
(82) Which of the following statements with respect to the required disclosures relating to tax loss carry forwards and carry backs is/are correct?
(Multiple Choice)
4.9/5 (75)
(75) A company may not file previous years' tax returns to change the amount of CCA claimed if it so wishes.
(True/False)
4.8/5 (81)
(81) JR Ltd.provided you with the following information: 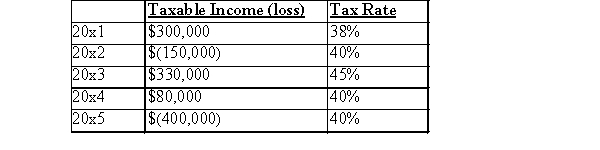 There are no temporary differences.What will be the amount of the tax refund received in 2015 assuming that tax losses are carried back as far as possible (sequentially)?
 (Multiple Choice)
4.8/5 (81)
(81) Geisler Corp.provided you with the following information for the year ending December 31, 2017: Net Income before taxes: $150,000 Depreciation (included in above)$90,000 CCA$250,000
The net book value of the capital assets was $1,100,000, and their UCC was $900,000 on January 1, 2017.
A temporary difference of $200,000 is reflected in an accumulated deferred income tax liability (DTL)balance of $90,000 at January 1, 2017.
There were no permanent differences.
Taxable income in the three-year carry back period was $400,000.Tax losses are carried back as far as allowable by law.
A tax rate of 45% applies to the current and previous years.
As a result of the company's temporary differences, Geisler's 2017 statement of financial position would show:
(Multiple Choice)
4.9/5 (73)
(73) How can a company use CCA to fully utilize losses that have been incurred?
(Essay)
4.9/5 (79)
(79) A tax loss represents the present and deferred benefit that the company will be able to realize from the tax loss through a reduction of income taxes paid to governments.
(True/False)
4.8/5 (79)
(79) JMR Corp.sustained taxable income in 2011 of $50,000 when the tax rate was 40%.In 2012 they suffered a tax loss of $80,000 when the tax rate was 38%.All of the following are true except:
(Multiple Choice)
4.8/5 (84)
(84) In order to help companies and their auditors determine whether the criteria "more likely than not" has been realized, IAS 12 has set out some guidelines for unfavourable evidence.List two of these.
(Essay)
4.8/5 (73)
(73) Under IFRS, the income tax expense pertaining to continuing operations must be presented on the face of the income statement.
(True/False)
4.9/5 (83)
(83) FGH had a $1,200 temporary difference for deferred gross margin on instalment sales at the end of 2012.This temporary difference will reverse equally during 2013, 2014 and 2015.The enacted corporate income tax rate is 48% and government is discussing a reduction in the corporate income tax rates for 2014 and 2015 to 38%.The deferred income tax liability related to this temporary difference at the end of 2013 would be:
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)