



 Chat with AI
Exam 17: Tax Losses

Exam 12: Financial Liabilities and Provisions78 Questions
Exam 13: Financial Instruments: Long-Term Debt74 Questions
Exam 14: Shareholders Equity181 Questions
Exam 15: Financial Instruments: Complex Debt and Equity135 Questions
Exam 16: Corporate Income Tax122 Questions
Exam 17: Tax Losses98 Questions
Exam 18: Leases234 Questions
Exam 19: Post-Employment Benefits92 Questions
Exam 20: Earnings Per Share153 Questions
Exam 21: Accounting Changes157 Questions
Exam 22: Financial Statement Analysis165 Questions
Select questions type


The terms "probable" and "more likely than not" refer to probabilities that are greater than or equal to 50%.
(True/False)
4.9/5  (85)
(85) KAR Ltd.has been in business for five years and incurs a loss of $320,000 in 20x15.The company has no temporary differences.The history of the company's earnings since they began operations is a follows: 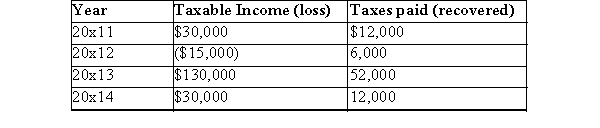 The tax rate has been constant at 40%.Required:
Prepare journal entries to record the recovery of taxes and any journal entries necessary for any loss carry forwards.Assume probability of recovery is less than 50%
The tax rate has been constant at 40%.Required:
Prepare journal entries to record the recovery of taxes and any journal entries necessary for any loss carry forwards.Assume probability of recovery is less than 50% (Essay)
4.7/5 (81)
(81) Existing sufficient taxable temporary differences, which will result in taxable income, is one piece of evidence to support a more likely than not criteria.
(True/False)
4.8/5 (78)
(78) Under ASPE, deferred income tax assets due to carry forwards may or may not be recognized, depending whether the company uses the taxes payable method.
(True/False)
4.8/5 (68)
(68) VB Corporation incurred a tax loss of $86,000.Based on a tax rate of 45% what is the potential tax benefit?
(Multiple Choice)
4.8/5 (78)
(78) In general, deferred income tax assets due to tax loss carry forwards only to the extent that they are likely to be realized.
(True/False)
4.7/5 (76)
(76) A company will show the same income tax expense/benefit regardless of whether or not a valuation allowance account is used.
(True/False)
4.7/5 (70)
(70) Taxes are recovered at the rate at which it was originally paid.The tax rate in the year the loss occurs is not relevant.
(True/False)
4.8/5 (67)
(67) A tax benefit represents the present and deferred benefit that the company will be able to realize from the tax loss through a reduction of income taxes paid to governments.
(True/False)
4.8/5 (87)
(87) MDB had a $1,200 temporary tax difference for deferred gross margin on instalment sales at the end of 2012.This temporary difference will reverse equally during 2013, 2014, and 2015.The enacted corporate income tax rate is 25% and Parliament is discussing an increase in the corporate income tax rates for 2014 and 2015 to 35%.The deferred income tax liability related to this temporary difference at the end of 2013 would be:
(Multiple Choice)
4.7/5 (92)
(92) VB Ltd.provided you with the following information: 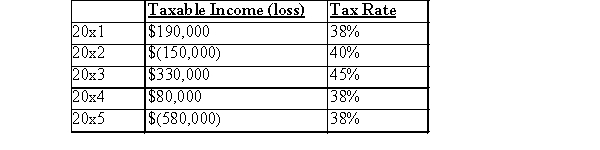 There are no temporary differences.The deferred income tax benefit of the loss carry forward was set up in 2015 as the probability of realization was greater than 50%.In 2016 a further loss of $140,000 was incurred.Management determined that they were still mor likely than not to realize the loss.The tax rate for 2016 was 45%.What would be the carrying amount of the deferred income tax benefit/loss carry forward on the balance sheet at the end of 2016?
 (Multiple Choice)
4.8/5 (95)
(95) Once a deferred benefit of a tax loss carry forward has been recorded, does it have to remain on the
balance sheet until realized? Explain.
(Essay)
4.9/5 (87)
(87) EGR Ltd.has been in business for five years and incurs a loss of $320,000 in 20x15.The company has no temporary differences.The history of the company's earnings since they began operations is a follows: 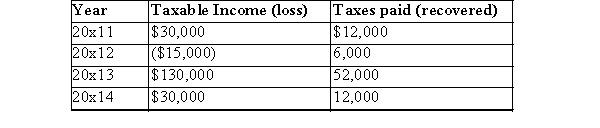 The tax rate has been constant at 40%.Required:
Prepare journal entries to record the recovery of taxes and any journal entries necessary for any loss carry forwards.Assume probability of recovery is greater than 50%
The tax rate has been constant at 40%.Required:
Prepare journal entries to record the recovery of taxes and any journal entries necessary for any loss carry forwards.Assume probability of recovery is greater than 50% (Essay)
4.8/5 (78)
(78) JR Company incurred a loss in 2011, due in part to a fire at one of its plants.The deferred benefit of a loss carry forward was not recognized in the year as the probability of realization was less than 50%.In 2012, JR Company incurred a small loss, but due to large contracts upcoming, it was determined that the probability of realization was greater than 50%.The tax rate for 2011 was 40% and 2012 45%.JR Company should:
(Multiple Choice)
4.9/5 (78)
(78) The following information for JG Corporation is available: 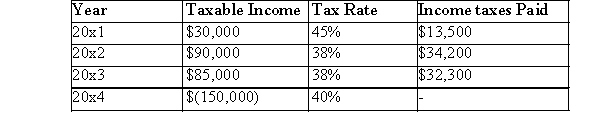 JG carries applies its tax losses sequentially, that is, tax losses are carried back as far as possible.The taxes recovered for the year ended 2014 amounted to:
 (Multiple Choice)
4.9/5 (88)
(88) Carry back and carry forward procedures for temporary differences are always applied, even when there are no temporary differences for deductible items, and there are no current income taxes payable.
(True/False)
4.9/5 (83)
(83) Reducing CCA is one tax strategy that a company may employ.All of the following are true except:
(Multiple Choice)
4.7/5 (86)
(86) If a corporation incurs a taxable loss, they are entitled to carry the loss back for three years or forward for twenty years.
(True/False)
5.0/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)