



 Chat with AI
Exam 21: Accounting Changes

Exam 12: Financial Liabilities and Provisions78 Questions
Exam 13: Financial Instruments: Long-Term Debt74 Questions
Exam 14: Shareholders Equity181 Questions
Exam 15: Financial Instruments: Complex Debt and Equity135 Questions
Exam 16: Corporate Income Tax122 Questions
Exam 17: Tax Losses98 Questions
Exam 18: Leases234 Questions
Exam 19: Post-Employment Benefits92 Questions
Exam 20: Earnings Per Share153 Questions
Exam 21: Accounting Changes157 Questions
Exam 22: Financial Statement Analysis165 Questions
Select questions type


Which of the following is not a change in accounting policy?
(Multiple Choice)
4.9/5  (64)
(64) The primary principle addressed by recent changes to ASPE and IFRS on accounting changes and error corrections is the:
(Multiple Choice)
4.8/5 (99)
(99) Which of the following changes would be accounted for prospectively?
(Multiple Choice)
4.9/5 (83)
(83) A change in policy mandated by a change of standard under IFRS is an example of a mandatory policy change.
(True/False)
4.8/5 (76)
(76) On July 1, 20x1, PRC purchased a delivery truck for $116,000 cash.Its estimated useful life was 7 years with a residual value of $4,000.Straight-line depreciation is used.On January 1, 20x4, PRC revised the estimated useful life of the truck to 6 years and projected a residual value of $7,400.The accounting period ends December 31.What amount of depreciation should PRC recognize on the truck at December 31, 20x4?
(Multiple Choice)
4.9/5 (72)
(72) A change, for depreciation purposes, of either estimated useful life or from one GAAP to another GAAP accounting method, usually is referred to as a change in accounting principle.
(True/False)
4.9/5 (82)
(82) On January 1, 20x1, MBC purchased a pattern-making machine for $400,000 cash.The machine had an estimated useful life of 25 years and a residual value of $10,000.At the beginning of 20x6, the machine was given a major overhaul, which cost $28,000.The overhaul cost was properly debited to the asset account.The overhaul did not change the estimated residual value but did change the total estimated life to 30 years.The accounting period ends December 31.MBC should recognize 20x6 depreciation of:
(Multiple Choice)
4.8/5 (81)
(81) A firm changes from accelerated depreciation to straight-line depreciation in 20x1: Depreciation: Total before 20x1: 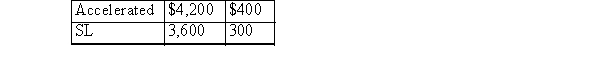 Provide the 20x1 entries to record the accounting change and to record 20x1 depreciation expense, ignoring taxes.
 (Essay)
4.9/5 (80)
(80) When an accounting change is to be recorded and reported under the Retrospective approach, the:
(Multiple Choice)
4.8/5 (70)
(70) ABC Inc.'s Year 1 ending inventory was overstated by $20,000.Its Year 2 ending inventory was understated by $30,000.Assuming that the books for Year 2 are now closed, which of the following adjustments would be required? Assume a tax rate of 25%.
(Multiple Choice)
4.7/5 (59)
(59) An asset cost $12,000 when acquired and had an estimated useful life of 10 years with no estimated residual value.Use straight-line depreciation.During Year 7, the overall life was changed to 12 years
(a)What should be recorded as depreciation expense for Year 7? $_ _.
(b)What would the balance of accumulated depreciation be at the start of Year 8? $________
(c)Would a correcting entry be made during Year 7 for the change? Yes ________ No ________ Explain why.________
(Essay)
4.8/5 (83)
(83) A change in an amortization rate, such as on a copyright, should be accounted for:
(Multiple Choice)
4.7/5 (80)
(80) The failure to accrue revenues for services rendered but not billable until future periods would be considered a self-correcting error.
(True/False)
4.7/5 (63)
(63) In 20x1, an asset was purchased for $45,000 and has been depreciated using sum-of-the-years'-digits based on an estimated useful life of five years and no residual value.In 20x3 (before the adjusting an closing entries), the company decided to change to straight-line depreciation.The estimated useful lif was not to be changed.
(a)Give the entry required when the decision was made.
(b)Give the entry for depreciation expense for 20x3.
(Essay)
5.0/5 (72)
(72) Which type of accounting change should always be accounted for in current and future periods?
(Multiple Choice)
4.8/5 (80)
(80) Give the correct response to each of the following events:
(a)An overstatement of accrued wages payable by $2,000 at the end of 20x1 would cause retained earnings at the end of 20x2 to be ________ Overstated; ________ Understated by; correct
(assuming no correcting entry).
(b)A $6,000 purchase of merchandise on credit in 20x1 was not recorded in 20x1; but it was recorde in 20x2 when the cash was paid.It was discovered during 20x3.The merchandise was not included in the 20x1 ending inventory.Therefore, 20x1 income was: ________ Overstated; ________
Understated by; correct.
(c)The 20x2 ending inventory was Overstated $4,000 and no correcting entry has been made.Therefore the 20x3 net income is: ________ Overstated; ________ Understated by; ________
correct.
(Essay)
4.7/5 (83)
(83) If it is impracticable to determine the cumulative effect at the beginning of the current period or, if it is allowed by the creation of a new accounting standard, an accounting change may be applied prospectively.
(True/False)
4.8/5 (91)
(91) The following accounting errors occurred in 20x1; they were discovered in 20x2: Purchases for 20x1 Overstated $600; ending 20x1 inventories Overstated $600; and depreciation expense for 20x1 Overstated $600.The combined effect of these errors caused 20x1 pre-tax income to be:
Overstated $________; or Understated by $________; or No Effect _.
(Essay)
4.7/5 (75)
(75) Which of the following combinations of errors would cause a $2,000 overstatement of pre-tax income?
(Multiple Choice)
4.9/5 (84)
(84) At the end of Year 1, ABC Inc.'s inventories were overstated by $10,000.At the end of Year 2 its inventories were overstated by $20,000.Assuming that ABC Inc.is subject to a 20% tax rate, the effect of these overstatements on the company's Year 2 Cost of Goods Sold would be an:
(Multiple Choice)
4.9/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)