



 Chat with AI
Exam 20: Risk Management in Financial Institutions

Exam 1: An Overview of Financial Markets and Institutions45 Questions
Exam 2: The Federal Reserve and Its Powers48 Questions
Exam 3: The Fed and Interest Rates43 Questions
Exam 4: The Level of Interest Rates29 Questions
Exam 5: Bond Prices and Interest Rate Risk32 Questions
Exam 6: The Structure of Interest Rates33 Questions
Exam 7: Money Markets 133 Questions
Exam 8: Bond Markets33 Questions
Exam 9: Mortgage Markets and Mortgagebacked Securities37 Questions
Exam 10: Equity Markets29 Questions
Exam 11: Derivatives Markets38 Questions
Exam 12: International Markets24 Questions
Exam 13: Commercial Bank Operations28 Questions
Exam 14: International Banking35 Questions
Exam 15: Regulation of Financial Institutions33 Questions
Exam 16: Thrift Institutions and Finance Companies44 Questions
Exam 17: Insurance Companies and Pension Funds47 Questions
Exam 18: Investment Banking36 Questions
Exam 19: Investment Companies35 Questions
Exam 20: Risk Management in Financial Institutions75 Questions
Select questions type


To hedge a positive duration gap a bank could sell interest rate futures.
(True/False)
4.9/5  (80)
(80) A bank wishing to avoid higher borrowing costs would be most likely to:
(Multiple Choice)
4.9/5 (87)
(87) Which one of the following is a source of liquidity risk for a bank?
(Multiple Choice)
4.9/5 (85)
(85) Earnings simulations that estimate proforma income statements and balance sheets for different detailed economic and interest rate scenarios for 1‐ or 2‐year periods are called ______ analysis.
(Multiple Choice)
4.7/5 (89)
(89) Refer to the information below for questions
Formosa Independence Bank has the following balance sheet:
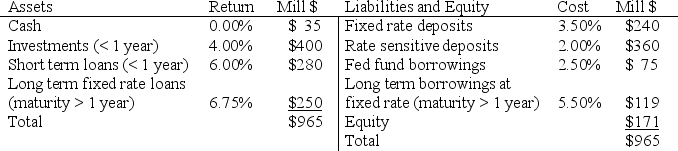 -If all interest rates on the two sides of balance sheet decline by 65 basis points, when other things are equal, what is the change in net interest income for Formosa Independence Bank over the year?
 (Multiple Choice)
4.7/5 (87)
(87) A bank has a negative duration gap and wishes to hedge to use an interest rate swap to hedge its interest rate risk. The bank should
(Multiple Choice)
4.9/5 (67)
(67) A bond has a duration of 7.5 years. Its current market price is $1,125. Interest rates in the market are 7% today. It has been forecasted that interest rates will rise to 9% over the next couple of weeks. How will this bond's price change in percentage terms?
(Multiple Choice)
4.8/5 (71)
(71) The risk of direct or indirect loss resulting from inadequate or failed internal processes, people, and systems, or from external events is called
(Multiple Choice)
4.8/5 (76)
(76) A bank that has made 30 year adjustable rate mortgages that reprice in 6 months that are funded with one year CDs will have a positive $GAP over a 1 year period and a negative Duration Gap all else equal.
(True/False)
4.9/5 (75)
(75) Relying on liquid assets to meet liquidity requirements is ______ than relying on liability management, but the former is ______.
(Multiple Choice)
4.8/5 (74)
(74) Which of the following could be used to reduce a bank's credit risk exposure?
I. Increase its loan to deposit ratio
II. Increase its allowable concentration ratio
III. Increase its required minimum credit score
IV. Participate in loans in other geographic areas
(Multiple Choice)
4.8/5 (85)
(85) Microhedging is hedging the interest rate risk of a specific transaction.
(True/False)
4.8/5 (96)
(96) ABC Bank has $39 million invested in T-Bonds with a 16-year duration, $39 million in 6 month maturity T-Bills, and $75 million invested in consumer loans with a 3 year duration. Based only on this data, what is the duration of the bank's asset portfolio in years?
(Multiple Choice)
4.8/5 (85)
(85) A bank has an average asset duration of 5 years and an average liability duration of 3 years. This bank has total assets of $500 million and total liabilities of $250 million. Currently, market interest rates are 10 percent. If interest rates fall to 8 percent, what is this bank's change in net worth?
(Multiple Choice)
4.9/5 (70)
(70) A bank has an average asset duration of 1.15 years and an average liability duration of 2.70 years. This bank has $250 million in total assets and $225 million in total liabilities. This bank has:
(Multiple Choice)
4.9/5 (80)
(80) Swaps are usually the best hedging tool to use to hedge short term risks occurring in a half year or less.
(True/False)
5.0/5 (65)
(65) Which of the following could be appropriately used to reduce the $Gap for a bank that specializes in mortgage lending?
I. Issue more ARMs
II. Securitize and sell mortgages
III. Buy futures on long term Treasury bonds
IV. Enter into a swap to pay fixed and receive a variable rate of interest
(Multiple Choice)
4.7/5 (85)
(85) The most liquid asset on the bank balance sheet are ______ and the highest earning category of assets are ______.
(Multiple Choice)
4.8/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)