



 Chat with AI
Exam 20: Risk Management in Financial Institutions

Exam 1: An Overview of Financial Markets and Institutions45 Questions
Exam 2: The Federal Reserve and Its Powers48 Questions
Exam 3: The Fed and Interest Rates43 Questions
Exam 4: The Level of Interest Rates29 Questions
Exam 5: Bond Prices and Interest Rate Risk32 Questions
Exam 6: The Structure of Interest Rates33 Questions
Exam 7: Money Markets 133 Questions
Exam 8: Bond Markets33 Questions
Exam 9: Mortgage Markets and Mortgagebacked Securities37 Questions
Exam 10: Equity Markets29 Questions
Exam 11: Derivatives Markets38 Questions
Exam 12: International Markets24 Questions
Exam 13: Commercial Bank Operations28 Questions
Exam 14: International Banking35 Questions
Exam 15: Regulation of Financial Institutions33 Questions
Exam 16: Thrift Institutions and Finance Companies44 Questions
Exam 17: Insurance Companies and Pension Funds47 Questions
Exam 18: Investment Banking36 Questions
Exam 19: Investment Companies35 Questions
Exam 20: Risk Management in Financial Institutions75 Questions
Select questions type


Refer to the information below for questions
Formosa Independence Bank has the following balance sheet:
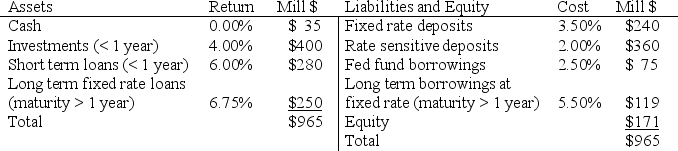 -The bank's one-year gap between assets and liabilities is (Mill $)
 (Multiple Choice)
4.9/5  (82)
(82) Although caps, floors, and collars can be created by buying and selling options on financial futures, this strategy is difficult because
(Multiple Choice)
4.8/5 (68)
(68) Which one of the following alternatives is an appropriate way to deal with deposit withdrawals that utilizes asset management of liquidity?
(Multiple Choice)
4.8/5 (75)
(75) Negotiable certificates of deposit (CDs), federal funds, repurchase agreements, commercial paper, and Eurodollar borrowings are called
(Multiple Choice)
4.7/5 (73)
(73) Suppose that the mean change in the Treasury bill yield over the next month is 0 basis points with a standard deviation of 0.50. The duration for the Treasury bills is 6 months or 0.50 years and the bank holds $10,000,000 in Treasury bills The Treasury bills have an APR of 7.0 (3.5% for six months) . Based on this information, what is the VaR with a 99% confidence level?
(Multiple Choice)
5.0/5 (70)
(70) Refer to the information below for questions
XYZ Bank has DA = 2.4 years and DL = 0.9 years. The bank has total equity of $82 million and total assets of $850 million. Currently, interest rates are at 6%.
-What is the bank's duration gap in years?
(Multiple Choice)
4.8/5 (87)
(87) A ______ eliminates the effects of extreme movements in interest rates, allowing the bank's cash flows to fluctuate within a specified range.
(Multiple Choice)
4.8/5 (72)
(72) Macrohedging is the use of risk-management instruments such as futures and options to reduce the interest rate risk of the overall bank portfolio.
(True/False)
5.0/5 (91)
(91) Short‐term assets that can be converted quickly into cash at a price near their purchase price that are held to provide both liquidity and a safe return are called
(Multiple Choice)
4.9/5 (83)
(83) The simplest form of hedging interest rate risk is matched funding of loans..
(True/False)
4.9/5 (84)
(84) For a given time period, assets that mature within the period or reprice within the period are considered rate sensitive.
(True/False)
4.8/5 (86)
(86) A bank with a positive dollar gap will have a decrease in net interest income when ______.
(Multiple Choice)
4.9/5 (78)
(78) A U.S. company has a euro denominated liability it must repay in 6 months. A short position in euro futures could help offset the corporation's foreign exchange risk.
(True/False)
4.9/5 (91)
(91) Refer to the information below for questions
XYZ Bank has DA = 2.4 years and DL = 0.9 years. The bank has total equity of $82 million and total assets of $850 million. Currently, interest rates are at 6%.
-To set the bank's duration gap to zero the bank could
(Multiple Choice)
4.7/5 (80)
(80) Suppose a bank has an asset duration of 5 years and a liability duration of 2.5 years. This bank has $1,000 million in assets and $750 million in liabilities. They plan on hedging with a Treasury bond futures contract which has an underlying duration of 8.5 years and which is selling right now for $99,000 for a $100,000 contract. How many futures contracts does this bank need to fully hedge itself against interest rate risk?
(Multiple Choice)
4.9/5 (81)
(81) Refer to the information below for questions
Formosa International Bank (FIB) (mill$)
Funds borrowed \ 6,300 Maximum amount FIB can still borrow \ 8,600 Cash-type assets \ 4,700 Excess cash reserves \ 100 Federal Reserve borrowings \ 200
-What are Formosa International Bank's total current uses of liquidity?
(Multiple Choice)
4.9/5 (84)
(84) In a credit default swap, the most a seller of the swap may have to pay is
(Multiple Choice)
4.7/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)