



 Chat with AI
Exam 3: Supply and Demand Theory

Exam 1: What Economics Is About174 Questions
Exam 2: Production Possibilities Frontier Framework156 Questions
Exam 3: Supply and Demand Theory224 Questions
Exam 4: Prices Free Controlled and Relative122 Questions
Exam 5: Supply Demand and Price Applications76 Questions
Exam 6: Macroeconomic Measurements Part I Prices and Unemployment151 Questions
Exam 7: Macroeconomic Measurements Part II Gdp and Real Gdp150 Questions
Exam 8: Aggregate Demand and Aggregate Supply204 Questions
Exam 9: Classical Macroeconomics and the Self Regulating Economy172 Questions
Exam 10: Keynesian Macroeconomics and Economic Instability a Critique of the Self Regulating Economy200 Questions
Exam 11: Fiscal Policy and the Federal Budget167 Questions
Exam 12: Money Banking and the Financial System150 Questions
Exam 13: The Federal Reserve System180 Questions
Exam 14: Money and the Economy150 Questions
Exam 15: Monetary Policy185 Questions
Exam 16: Expectations Theory and the Economy150 Questions
Exam 17: Economic Growth Resources Technology Ideas and Institutions103 Questions
Exam 18: Debates in Macroeconomics Over the Role and Effects of Government100 Questions
Exam 19: Elasticity204 Questions
Exam 20: Consumer Choice and Behavioral Economics179 Questions
Exam 21: Production and Costs245 Questions
Exam 22: Perfect Competition187 Questions
Exam 23: Monopoly195 Questions
Exam 24: Monopolistic Competition Oligopoly and Game Theory172 Questions
Exam 25: Government and Product Markets Antitrust and Regulation158 Questions
Exam 26: Factor Markets With Emphasis on the Labor Market184 Questions
Exam 27: Wages Unions and Labor138 Questions
Exam 28: The Distribution of Income and Poverty99 Questions
Exam 29: Interest Rent and Profit198 Questions
Exam 30: Market Failure Externalities Public Goods and Asymmetric Information187 Questions
Exam 31: Public Choice and Special Interest Group Politics135 Questions
Exam 32: Building Theories to Explain Everyday Life From Observations to Questions to Theories to Predictions62 Questions
Exam 33: International Trade152 Questions
Exam 34: International Finance122 Questions
Exam 35: The Economic Case for and Against Government Five Topics Considered87 Questions
Exam 36: Stocks Bonds Futures and Options110 Questions
Select questions type


Exhibit 3-17
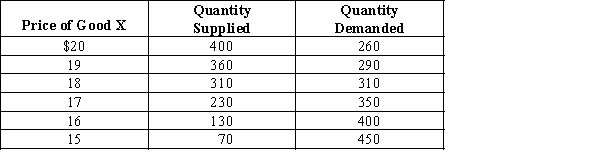 -Refer to Exhibit 3-17. At a price of $20, the quantity demanded of good X is ____________ than the quantity supplied of good X, and economists would use this information to predict that the price of good X would soon ______________. This would push the price __________ the equilibrium price.
 (Multiple Choice)
4.8/5  (82)
(82) Economists use the terms neutral good and normal good interchangeably.
(True/False)
5.0/5 (80)
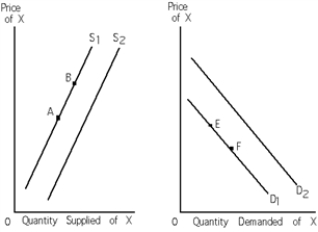
(80) Exhibit 3-6
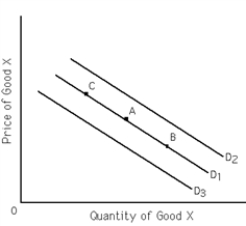 -Refer to Exhibit 3-6. If an increase in income causes the demand for good X to shift from D1 to D2,then good X is
 (Multiple Choice)
4.9/5 (78)
(78) Good X is a normal good. If the average income of those who buy good X rises, the _____________ curve for good X will shift ____________ resulting in a(n) _____________ in the equilibrium price of X and a(n) ____________ in the equilibrium quantity of X.
(Multiple Choice)
4.9/5 (86)
(86) Exhibit 3-11
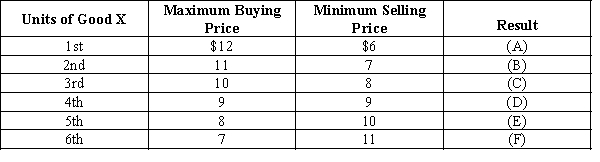 -Refer to Exhibit 3-11. Fill in blanks (A) and (B) respectively with "Exchange" or "No Exchange" to indicate whether or not exchange would take place at the given prices.
 (Multiple Choice)
4.9/5 (80)
(80) Which of the following is true about the relationship between price and quantity supplied?
(Multiple Choice)
4.8/5 (84)
(84) 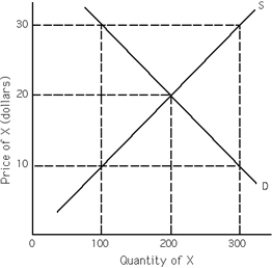 -Refer to Exhibit 3-10. $20 is the
Exhibit 3-9
 -Refer to Exhibit 3-9. Consumers view X and Y as substitutes. If the price of Y increases as a result of a decrease in the supply of Y, an economist would expect a movement in the market for X from
 (Multiple Choice)
4.8/5 (73)
(73) Suppose Smith wants one iPhone no matter what the price is between $0 and $350, Jones wants one iPhone no matter what the price is between $0 and $200, and Griffith wants one iPhone no matter what the price is between $0 and $450. In this case, each individual buyer's demand curve will be __________________ and the market demand curve will be __________________.
(Multiple Choice)
4.9/5 (74)
(74) The fundamental reason why most supply curves are upward sloping is that
(Multiple Choice)
4.9/5 (85)
(85) Exhibit 3-1
 -Refer to Exhibit 3-1. Equilibrium price and quantity are ____________________, respectively.
 (Multiple Choice)
4.9/5 (79)
(79) The price of X was $10 in year 1 and $14 in year 2. Which of the following could be the correct reason for the rise in price?
(Multiple Choice)
4.8/5 (74)
(74) An increase in the expected price of corn would likely do the following to the current supply and demand for corn:
(Multiple Choice)
4.9/5 (72)
(72) One can determine the consumers' surplus if the _______________ are known.
(Multiple Choice)
4.8/5 (87)
(87) At a price for which quantity demanded exceeds quantity supplied, a __________ is experienced, which pushes the price __________ toward its equilibrium value.
(Multiple Choice)
4.9/5 (67)
(67) When Hurricane Katrina hit the Gulf Coast of the United States in 2005 it destroyed 5,000,000 acres of timber. Given that lumber is timber that has been sawed or split into planks and boards, explain in terms of supply and/or demand how the hurricane impacted each of the following markets (be sure to note the expected resulting impact on equilibrium price and quantity):
a.Domestic lumber
b.Imported lumber
c.New home construction
(Essay)
4.9/5 (81)
(81) When the price of a good is $5, the quantity demanded of a good is 30 units, and the quantity supplied of the good is 50 units. For every $1 decrease in the price of this good, quantity demanded rises by 5 units and quantity supplied falls by 5 units. The equilibrium price of this good is ___________and the equilibrium quantity of this good is _________ units.
(Multiple Choice)
4.7/5 (79)
(79) As the price of good A rises as a result of a decrease in the supply of good A, the demand for good B rises. Therefore, goods A and B are
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)