



 Chat with AI
Exam 17: Economic Growth Resources Technology Ideas and Institutions

Exam 1: What Economics Is About174 Questions
Exam 2: Production Possibilities Frontier Framework156 Questions
Exam 3: Supply and Demand Theory224 Questions
Exam 4: Prices Free Controlled and Relative122 Questions
Exam 5: Supply Demand and Price Applications76 Questions
Exam 6: Macroeconomic Measurements Part I Prices and Unemployment151 Questions
Exam 7: Macroeconomic Measurements Part II Gdp and Real Gdp150 Questions
Exam 8: Aggregate Demand and Aggregate Supply204 Questions
Exam 9: Classical Macroeconomics and the Self Regulating Economy172 Questions
Exam 10: Keynesian Macroeconomics and Economic Instability a Critique of the Self Regulating Economy200 Questions
Exam 11: Fiscal Policy and the Federal Budget167 Questions
Exam 12: Money Banking and the Financial System150 Questions
Exam 13: The Federal Reserve System180 Questions
Exam 14: Money and the Economy150 Questions
Exam 15: Monetary Policy185 Questions
Exam 16: Expectations Theory and the Economy150 Questions
Exam 17: Economic Growth Resources Technology Ideas and Institutions103 Questions
Exam 18: Debates in Macroeconomics Over the Role and Effects of Government100 Questions
Exam 19: Elasticity204 Questions
Exam 20: Consumer Choice and Behavioral Economics179 Questions
Exam 21: Production and Costs245 Questions
Exam 22: Perfect Competition187 Questions
Exam 23: Monopoly195 Questions
Exam 24: Monopolistic Competition Oligopoly and Game Theory172 Questions
Exam 25: Government and Product Markets Antitrust and Regulation158 Questions
Exam 26: Factor Markets With Emphasis on the Labor Market184 Questions
Exam 27: Wages Unions and Labor138 Questions
Exam 28: The Distribution of Income and Poverty99 Questions
Exam 29: Interest Rent and Profit198 Questions
Exam 30: Market Failure Externalities Public Goods and Asymmetric Information187 Questions
Exam 31: Public Choice and Special Interest Group Politics135 Questions
Exam 32: Building Theories to Explain Everyday Life From Observations to Questions to Theories to Predictions62 Questions
Exam 33: International Trade152 Questions
Exam 34: International Finance122 Questions
Exam 35: The Economic Case for and Against Government Five Topics Considered87 Questions
Exam 36: Stocks Bonds Futures and Options110 Questions
Select questions type


Exhibit 17-3
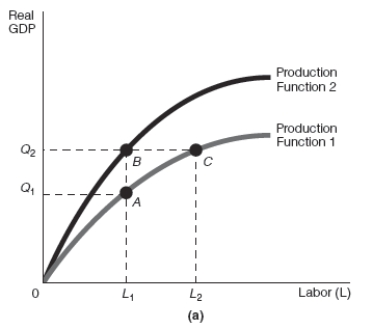
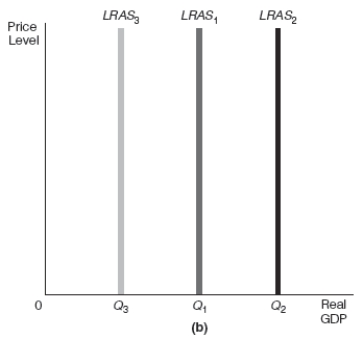 -Refer to Exhibit 17-3 Assume that the starting point on the production function is point A. After an increase in the technology coefficient, there would be a ______________________ which would shift the LRAS curve from LRAS1 to _______________ resulting in _______________..
 (Multiple Choice)
4.8/5  (80)
(80) The relation between technology and the quantity of factor inputs to Real GDP is specified by the production function.
(True/False)
4.9/5 (74)
(74) When a production function is graphed with Real GDP on the vertical axis and labor on the horizontal axis, a rise in labor ________________________, and a rise in the technology coefficient __________________.
(Multiple Choice)
4.9/5 (86)
(86) Exhibit 17-1
Production Function
Real GDP = T (L, K), such that Real GDP = T(L + K)
Assume that the technology coefficient is equal to 0.40.
-Refer to Exhibit 17-1. If this production function is graphed with Real GDP on the vertical axis and labor on the horizontal axis, and the technology coefficient rises from 0.40 to 0.50, it would cause a
(Multiple Choice)
4.7/5 (78)
(78) Examples of physical capital include _______________________. Examples of human capital include ______________________________.
(Multiple Choice)
4.8/5 (81)
(81) The range of laws, rules, and regulations that define the allowed forms of use and transfer of resources is called the __________ structure of the economy.
(Multiple Choice)
4.9/5 (87)
(87) Two Harvard economists, Robert Barro and Rachel McCleary, have researched the role that ________________ plays in economic growth.
(Multiple Choice)
4.8/5 (77)
(77) In contrast to neoclassical growth theory, new growth theory lays more emphasis on
(Multiple Choice)
4.9/5 (95)
(95) _______________________ specifies the relation between technology and the factor inputs to output.
(Multiple Choice)
4.7/5 (95)
(95) When a country's GDP is higher one year than it was the previous year, absolute real economic growth has occurred.
(True/False)
4.8/5 (81)
(81) Neoclassical growth theory treats technology as an _________________ variable, and new growth theory treats technology as an ______________.
(Multiple Choice)
4.9/5 (60)
(60) In the production function Real GDP = T (L, K, NR, H), the T represents the _____________ coefficient, the L represents ________________, the K represents _______________, the NR represents natural resources, and the H represents ________________.
(Multiple Choice)
5.0/5 (85)
(85) The term economic growth can be used in reference to absolute real economic growth or to per- capita real economic growth.
(True/False)
4.8/5 (71)
(71) When a production function is graphed with Real GDP on the vertical axis and labor on the horizontal axis, a rise in labor ________________________, and a rise in capital __________________.
(Multiple Choice)
4.7/5 (84)
(84) Neoclassical growth theory placed emphasis on two resources:
(Multiple Choice)
4.9/5 (77)
(77) When income taxes are lowered in a given economy, it causes the supply of labor curve to shift __________which ___________ the equilibrium quantity of labor employed. In terms of the production function (graphed with labor on the horizontal axis and Real GDP on the vertical axis) this then causes _______________, which makes the LRAS curve shift ____________ resulting in ______________________.
(Multiple Choice)
4.8/5 (79)
(79) Research by Harvard economists Barro and McCleary revealed that church attendance and economic growth have a(n) _______________ relationship. They also found that specific religious beliefs (in heaven, hell, and afterlife) and economic growth have a(n) ___________ relationship.
(Multiple Choice)
4.8/5 (78)
(78) A useful rule of thumb called the "Rule of 70" states that if something grows at a constant rate of Z percent per year, it doubles in size approximately every __________ years.
(Multiple Choice)
4.8/5 (83)
(83) When a production function is graphed with Real GDP on the vertical axis and labor on the horizontal axis, a rise in capital________________________, and a rise in the technology coefficient __________________.
(Multiple Choice)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)