



 Chat with AI
Exam 22: Accounting for Changes and Errors

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


On January 1, 2016, Tessa loaned $12,000 to another company on a three-year, 4% note. No interest was accrued in
2016. Cash will not be received for the interest until the end of the three-year period. The error was discovered before adjusting and closing entries were posted on December 31, 2017. Ignoring income taxes, what should be the correct journal entry on December 31 a. Interest Receivable 480 Retained Earnings 480 b. Interest Receivable 960 Interest Revenue 960 c. Interest Receivable 480 Interest Revenue 480 d. Interest Receivable 960 Interest Revenue 480 Retained Earnings 480
(Short Answer)
4.8/5  (72)
(72) The accounting changes identified by current GAAP include all of the following except
(Multiple Choice)
4.9/5 (80)
(80) Several items related to accounting changes appear below. 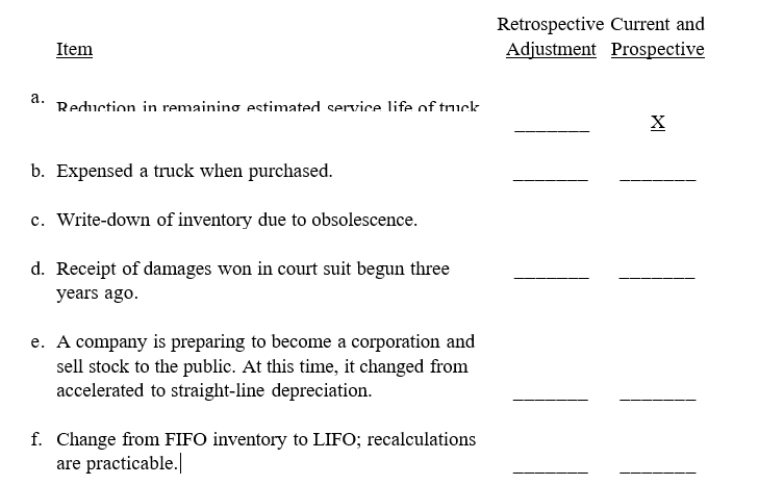 g. Increase in bad debt estimate from to of sales._______ _________
h. Change from LIFO to FIFO._______ _________
i. Change from individual statements to consolidated statements._______ _________
j. Change from percentage-of-sales to percentage-ofreceivables method of bad debt estimation._______ _________
k. Change from full costing to successful efforts._______ _________ Required:
Indicate the appropriate method of accounting for each case by placing an "X" in the appropriate column. Part a)
has been completed as an example.
g. Increase in bad debt estimate from to of sales._______ _________
h. Change from LIFO to FIFO._______ _________
i. Change from individual statements to consolidated statements._______ _________
j. Change from percentage-of-sales to percentage-ofreceivables method of bad debt estimation._______ _________
k. Change from full costing to successful efforts._______ _________ Required:
Indicate the appropriate method of accounting for each case by placing an "X" in the appropriate column. Part a)
has been completed as an example. (Essay)
4.9/5 (66)
(66) The correct 2016 net income for Magness Company, after error corrections, was $56,000. Two errors were found after net income was first reported. The January 1, 2016 inventory and the December 31, 2016, inventory were overstated by $5,000 and $10,000, respectively. What is the amount of the net income that must have been originally reported?
(Multiple Choice)
4.9/5 (80)
(80) Exhibit 22-5
Daniel Company, having a fiscal year ending on December 31, discovered the following errors in 2016:
· A collection of $12,000 from a customer for rent related to January, 2017, was recorded as revenue in 2016.
· Depreciation was understated by $600 in 2016.
· The January 1, 2015, inventory was overstated by $10,000.
· The January 1, 2016, inventory was understated by $6,000.
· Insurance premiums of $2,000 that relate to 2017 were expensed in 2016 when paid. Assume no other errors have occurred and ignore income taxes.
-Refer to Exhibit 22-5. Net income for 2016 was
(Multiple Choice)
4.9/5 (80)
(80) A change in accounting principle because an Accounting Standard Update has been issued and the former principle is no longer generally accepted is treated under the prospective method.
(True/False)
4.8/5 (77)
(77) The correction of an error in the financial statements of a prior period should be reflected, net of applicable income taxes, in the current
(Multiple Choice)
4.9/5 (90)
(90) On January 1, 2016, Sarah Company purchased for $60,000 a truck that had an estimated life of five years and no residual value at the end of its useful life. Sarah uses straight-line depreciation. The cost of the truck was charged to Repairs Expense when purchased in 2016.
Required:
a. Ignoring income taxes, prepare the journal entry to correct the error if it was discovered and corrected on January 1, 2019 Sarah's year ends on December 31).
b. When preparing the 2019 financial statements, how much depreciation expense should be reported on the comparative 2017 and 2018 income statements?
(Essay)
4.9/5 (66)
(66) Tulip Company decided to change from LIFO to FIFO inventory costing, effective January 1, 2018. The following data were available: 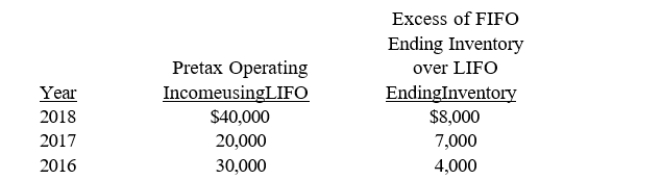 The income tax rate is 35%. The company began operations on January 1, 2016, and has paid no dividends since inception.
Required:
Answer the following questions relating to the 2017-2018 comparative financial statements.
a. What is net income for 2018?
b. What is restated net income for 2017?
c. Prepare the 2017 statement of retained earnings as it would appear in the comparative
2017-2018 financial statements.
The income tax rate is 35%. The company began operations on January 1, 2016, and has paid no dividends since inception.
Required:
Answer the following questions relating to the 2017-2018 comparative financial statements.
a. What is net income for 2018?
b. What is restated net income for 2017?
c. Prepare the 2017 statement of retained earnings as it would appear in the comparative
2017-2018 financial statements. (Essay)
4.9/5 (66)
(66) The Catherine Company, effective January 1, 2018, made the following accounting change:
· Catherine changed its depreciation method from double-declining-balance to the straight-line method on equipment purchased on January 1, 2016, at a cost of $400,000. The equipment had an estimated useful life of five years and a $30,000 residual value.
Catherine is subject to an income tax rate of 30% and can justify the changes.
Required:
Calculate the following amounts:
a. 2018 depreciation expense
b. the December 31, 2018, accumulated depreciation balance on the equipment
(Essay)
4.8/5 (62)
(62) Refer to Exhibit 22-1. Assuming an income tax rate of 35%, what is the amount of cumulative effect change reported in Chrissy's 2018 income statement ?
(Multiple Choice)
5.0/5 (78)
(78) When making a retrospective adjustment, all of the following steps are included except
(Multiple Choice)
5.0/5 (88)
(88) The December 31, 2016, ending inventory failed to include $25,000 of inventory that was received on December 27,
2016. The purchase on account was, however, properly recorded on the date of delivery. What effect will this error have on the December 31, 2016, assets, liabilities, and net income for the year then ended? Assets Liabilities NetIncome I. overstated overstated no effect II. understated understated no effect III. understated no effect understated IV understated understated understated
(Multiple Choice)
4.8/5 (92)
(92) An example of a change in accounting principle is the change from the direct method of accounting for uncollectable accounts to the aging-of-receivables method.
(True/False)
4.8/5 (76)
(76) When disclosing the impact of a retrospective adjustment for the change from LIFO to FIFO in 2017, which of the following impacts is not expected to be reported in the comparative financial statements when two-year comparative statements are presented?
(Multiple Choice)
4.9/5 (88)
(88) The Opal Company was incorporated and began operations on January 1, 2016. Opal used the weighted-average method for costing inventories. Effective January 1, 2017, Opal changed to FIFO for costing inventories and can justify the change. Information related to 2016 and 2017 inventory cost and net income is presented below: 2016 2017 Ending inventory, using: Weighted-average \ 650,000 \ 620,000 FIFO 680,000 630,000 Net income 700,000 750,000 (using average) (using FIFO) Opal's income tax rate is 30% for both 2016 and 2017.
Required:
Calculate the amount of the cumulative effect of the change on beginning retained earnings on January 1, 2017, that would appear on Opal's statement of retained earnings for the year ended December 31, 2017.
(Essay)
5.0/5 (80)
(80) Refer to Exhibit 22-3. If the revised estimated useful life of the truck is a total of eight years, what is the amount of depreciation expense that Katrina should report in its 2017 income statement?
(Multiple Choice)
4.9/5 (76)
(76) Generally accepted methods of accounting for a change in accounting principle include
(Multiple Choice)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)