



 Chat with AI
Exam 3: The Accounting Information System

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


The failure to properly record an adjusting entry to accrue an expense will result in an
(Multiple Choice)
4.8/5  (72)
(72) Accrual basis.Grier & Associates maintains its records on the cash basis. You have been engaged to convert its cash basis income statement to the accrual basis. The cash basis income statement, along with additional information, follows: 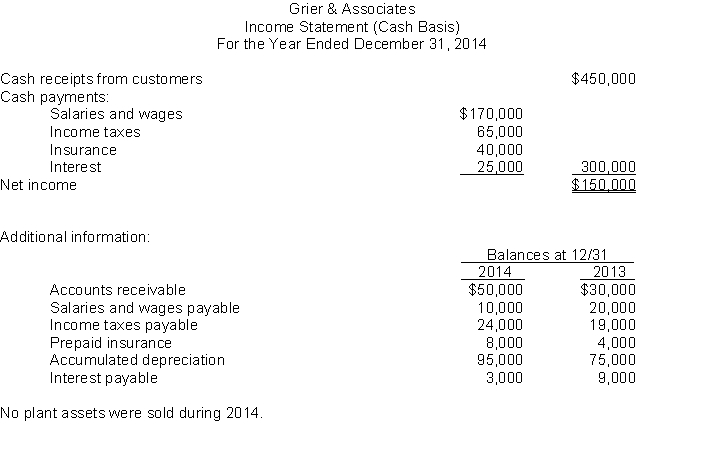
(Essay)
4.7/5 (96)
(96) To compute interest expense on a note for an adjusting entry, the formula is (principal × annual rate × a fraction). The numerator and denominator of the fraction are: 
(Short Answer)
4.9/5 (68)
(68) On June 1, 2014, Nott Corp. loaned Horn $800,000 on a 12% note, payable in five annual installments of $160,000 beginning January 2, 2015. In connection with this loan, Horn was required to deposit $5,000 in a noninterest-bearing escrow account. The amount held in escrow is to be returned to Horn after all principal and interest payments have been made. Interest on the note is payable on the first day of each month beginning July 1, 2014. Horn made timely payments through November 1, 2014. On January 2, 2015, Nott received payment of the first principal installment plus all interest due. At December 31, 2014, Nott's interest receivable on the loan to Horn should be
(Multiple Choice)
4.8/5 (93)
(93) Which of the following is the first step to be taken by a company deciding to convert to IFRS?
(Multiple Choice)
4.9/5 (82)
(82) Chen Company's account balances at December 31, 2014 for Accounts Receivable and the Allowance for Doubtful Accounts are $480,000 debit and $900 credit. Sales during 2014 were $1,650,000. It is estimated that 1% of sales will be uncollectible. The adjusting entry would include a credit to the allowance account for
(Multiple Choice)
4.8/5 (83)
(83) An example of an internal event would be a flood that destroyed a portion of a company's inventory.
(True/False)
4.7/5 (83)
(83) The ending retained earnings balance is reported on both the retained earnings statement and the balance sheet.
(True/False)
4.9/5 (76)
(76) Accrual basis.Sales salaries paid during 2014 were $85,000. Advances to salesmen were $1,100 on January 1, 2014, and $800 on December 31, 2014. Sales salaries accrued were $1,360 on January 1, 2014, and $1,880 on December 31, 2014. Show the computation of sales salaries on an accrual basis for 2014.
(Essay)
4.9/5 (89)
(89) If ending accounts receivable exceeds the beginning accounts receivable
(Multiple Choice)
4.9/5 (89)
(89) Olsen Company paid or collected during 2014 the following items:  The following balances have been excerpted from Olsen's balance sheets:
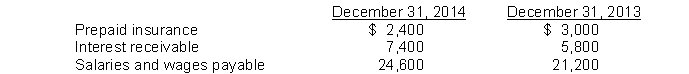 The interest revenue on the income statement for 2014 was
The following balances have been excerpted from Olsen's balance sheets: The interest revenue on the income statement for 2014 was (Multiple Choice)
4.9/5 (86)
(86) Which of the following criteria must be met before an event or item should be recorded for accounting purposes?
(Multiple Choice)
4.8/5 (74)
(74) It is not necessary to post the closing entries to the ledger accounts because new revenue and expense accounts will be opened in the subsequent accounting period.
(True/False)
4.8/5 (70)
(70) Reversing entries are
1. normally prepared for prepaid, accrued, and estimated items.
2. necessary to achieve a proper matching of revenue and expense.
3. useful in simplifying the recording of transactions in the next accounting period.
(Multiple Choice)
4.8/5 (64)
(64) A journal entry to record a receipt of rent in advance will include a
(Multiple Choice)
4.9/5 (73)
(73) Which of the following is a reason for recasting prior financial statements based on IFRS?
(Multiple Choice)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)