



 Chat with AI
Exam 3: The Accounting Information System

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Adjusting entries.Data relating to the balances of various accounts affected by adjusting or closing entries appear below. (The entries which caused the changes in the balances are not given.) You are asked to supply the missing journal entries which would logically account for the changes in the account balances.1. Interest receivable at 1/1/14 was $1,000. During 2014 cash received from debtors for interest on outstanding notes receivable amounted to $5,000. The 2014 income statement showed interest revenue in the amount of $6,400. You are to provide the missing adjusting entry that must have been made, assuming reversing entries are not made.2. Unearned rent at 1/1/14 was $5,300 and at 12/31/14 was $8,000. The records indicate cash receipts from rental sources during 2014 amounted to $55,000, all of which was credited to the Unearned Rent Revenue account. You are to prepare the missing adjusting entry.3. Accumulated depreciation-equipment at 1/1/14 was $230,000. At 12/31/14 the balance of the account was $280,000. During 2014, one piece of equipment was sold. The equipment had an original cost of $40,000 and was 3/4 depreciated when sold. You are to prepare the missing adjusting entry.4. Allowance for doubtful accounts on 1/1/14 was $50,000. The balance in the allowance account on 12/31/14 after making the annual adjusting entry was $65,000 and during 2014 bad debts written off amounted to $30,000. You are to provide the missing adjusting entry.5. Prepaid rent at 1/1/14 was $29,000. During 2014 rent payments of $120,000 were made and charged to "rent expense." The 2014 income statement shows as a general expense the item "rent expense" in the amount of $145,000. You are to prepare the missing adjusting entry that must have been made, assuming reversing entries are not made.6. Retained earnings at 1/1/14 was $130,000 and at 12/31/14 it was $210,000. During 2014, cash dividends of $50,000 were paid and a stock dividend of $40,000 was issued. Both dividends were properly charged to retained earnings. You are to provide the missing closing entry.
(Essay)
4.8/5  (67)
(67) The process of transferring figures from the book of original entry to the ledger accounts is called
(Multiple Choice)
4.8/5 (84)
(84) The book value of any depreciable asset is the difference between its cost and its salvage value.
(True/False)
4.9/5 (80)
(80) Adjusting entries that should be reversed include those for prepaid or unearned items that
(Multiple Choice)
5.0/5 (65)
(65) Eight-column work sheet.The trial balance of Winsor Corporation is reproduced on the following page. The information below is relevant to the preparation of adjusting entries needed to both properly match revenues and expenses for the period and reflect the proper balances in the real and nominal accounts.
InstructionsAs the accountant for Winsor Corporation, you are to prepare adjusting entries based on the following data, entering the adjustments on the work sheet and completing the additional columns with respect to the income statement and balance sheet. Carefully key your adjustments and label all items. (Due to time constraints, an adjusted trial balance is not required.) Round all computations to the nearest dollar.
(a) Winsor determined that one percent of sales will become uncollectible.
(b) Depreciation is computed using the straight-line method, with an eight-year life and $1,000 salvage value.
(c) Salesmen are paid commissions of 15% of sales. Commissions on sales for December have not been paid.(d) The note was issued on October 1, bearing interest at 8%, due Feb. 1, 2015.(e) A physical inventory of supplies indicated $340 of supplies currently in stock.(f) Provisions of a lease contract specify payments must be made one month in advance, with monthly payments at $800/mo. This provision has been complied with as of Dec. 31, 2014. 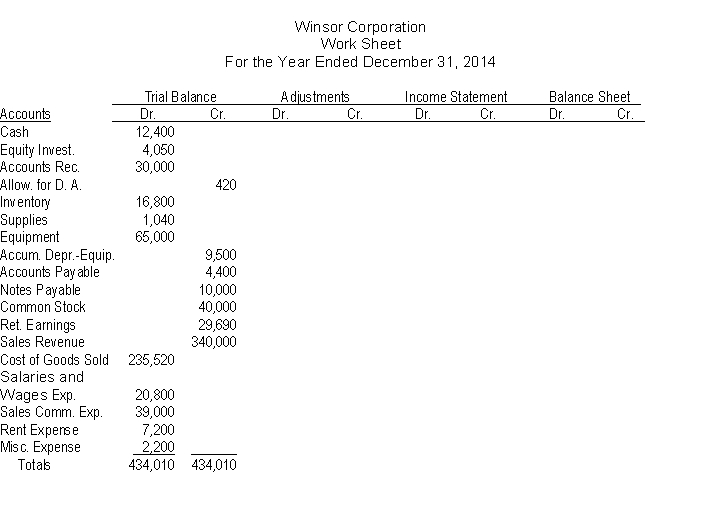
(Essay)
4.9/5 (81)
(81) A ledger is where a company first records transactions and other selected events.
(True/False)
4.8/5 (69)
(69) Olsen Company paid or collected during 2014 the following items: 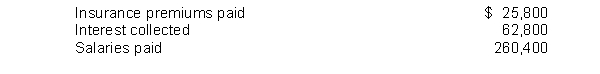 The following balances have been excerpted from Olsen's balance sheets:
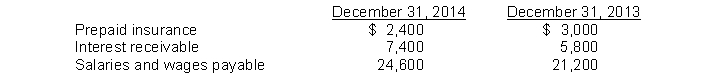 The insurance expense on the income statement for 2014 was
The following balances have been excerpted from Olsen's balance sheets: The insurance expense on the income statement for 2014 was (Multiple Choice)
4.9/5 (82)
(82) Recording the adjusting entry for depreciation has the same effect as recording the adjusting entry for
(Multiple Choice)
4.8/5 (66)
(66) The adjusted trial balance of Ryan Financial Planners appears below. Using the information from the adjusted trial balance, you are to prepare for the month ending December 31:1. an income statement.2. a retained earnings statement.3. a balance sheet. 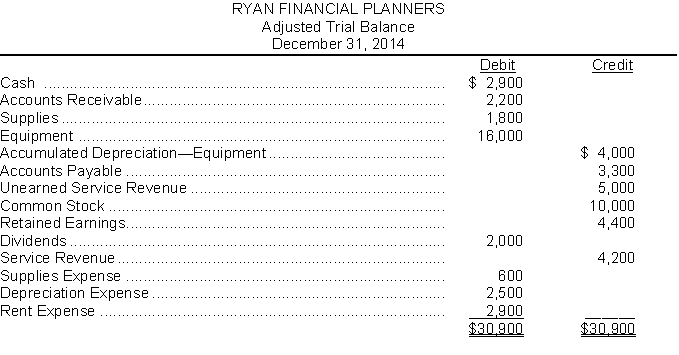
(Essay)
4.8/5 (76)
(76) Compared to the accrual basis of accounting, the cash basis of accounting overstates income by the net increase during the accounting period of the 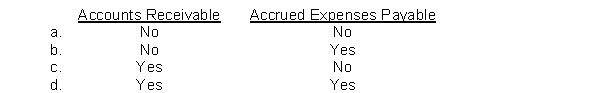
(Short Answer)
4.9/5 (82)
(82) When converting from cash-basis to accrual-basis accounting, which of the following adjustments should be made to cash receipts from customers to determine accrual-basis service revenue?
(Multiple Choice)
4.8/5 (83)
(83) A journal entry to record the sale of inventory on account will include a
(Multiple Choice)
4.8/5 (69)
(69) In general, debits refer to increases in account balances, and credits refer to decreases.
(True/False)
4.9/5 (89)
(89) An adjusting entry to record an accrued expense involves a debit to a(an)
(Multiple Choice)
4.9/5 (65)
(65) Which of the following statements best describes the purpose of closing entries?
(Multiple Choice)
5.0/5 (77)
(77) Mune Company recorded journal entries for the declaration of $150,000 of dividends, the $96,000 increase in accounts receivable for services rendered, and the purchase of equipment for $63,000. What net effect do these entries have on owners' equity?
(Multiple Choice)
5.0/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)