



 Chat with AI
Exam 9: Inventories: Additional Valuation Issues

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


GAAP requires reporting inventory at net realizable value, even if above cost, whenever there is a controlled market with a quoted price applicable to all quantities.
(True/False)
5.0/5  (88)
(88) On January 1, 2014, the merchandise inventory of Glaus, Inc. was $1,200,000. During 2014 Glaus purchased $2,400,000 of merchandise and recorded sales of $3,000,000. The gross profit rate on these sales was 25%. What is the merchandise inventory of Glaus at December 31, 2014?
(Multiple Choice)
4.9/5 (77)
(77) Which statement is true about the retail inventory method?
(Multiple Choice)
4.8/5 (92)
(92) Drake Corporation had the following amounts, all at retail:  What is Drake's ending inventory at retail?
 (Multiple Choice)
4.8/5 (76)
(76) When inventory declines in value below original (historical) cost, and this decline is considered other than temporary, what is the maximum amount that the inventory can be valued at?
(Multiple Choice)
4.8/5 (86)
(86) The inventory account of Irick Company at December 31, 2014, included the following items:  Based on the above information, the inventory account at December 31, 2014, should be reduced by
 (Multiple Choice)
4.8/5 (83)
(83) What is the effect of freight-in on the cost-to-retail ratio when using the conventional retail method?
(Multiple Choice)
4.9/5 (80)
(80) Confectioners, a chain of candy stores, purchases its candy in bulk from its suppliers. For a recent shipment, the company paid $1,500 and received 8,500 pieces of candy that are allocated among three groups. Group 1 consists of 2,500 pieces that are expected to sell for $0.15 each. Group 2 consists of 5,500 pieces that are expected to sell for $0.36 each. Group 3 consists of 500 pieces that are expected to sell for $0.72 each. Using the relative sales value method, what is the cost per item in Group 3?
(Multiple Choice)
4.9/5 (82)
(82) A markup cancellation can exceed the original markup but a markdown cancellation cannot exceed the original markdown.
(True/False)
4.9/5 (78)
(78) When the conventional retail inventory method is used, markdowns are commonly ignored in the computation of the cost to retail ratio because
(Multiple Choice)
4.8/5 (93)
(93) On August 31, a hurricane destroyed a retail location of Vinny's Clothier including the entire inventory on hand at the location. The inventory on hand as of June 30 totaled $960,000. Since June 30 until the time of the hurricane, the company made purchases of $255,000 and had sales of $750,000. Assuming the rate of gross profit to selling price is 40%, what is the approximate value of the inventory that was destroyed?
(Multiple Choice)
4.9/5 (68)
(68) Fry Corporation's computation of cost of goods sold is:  The average days to sell inventory for Fry are
 (Multiple Choice)
4.7/5 (91)
(91) Which of the following is not an acceptable approach in applying the lower-of-cost-or-market method to inventory?
(Multiple Choice)
4.9/5 (68)
(68) Which method(s) may be used to record a loss due to a price decline in the value of inventory?
(Multiple Choice)
4.9/5 (82)
(82) Lower-of-cost-or-market.
At 12/31/14, the end of Jenner Company's first year of business, inventory was $4,100 and $2,800 at cost and at market, respectively.Following is data relative to the 12/31/15 inventory of Jenner:  Selling price is $1.00/unit for all items. Disposal costs amount to 10% of selling price and a "normal" profit is 30% of selling price. There are 1,000 units of each item in the 12/31/15 inventory.
Instructions
(a) Prepare the entry at 12/31/14 necessary to implement the lower-of-cost-or-market procedure assuming Jenner uses a contra account for its balance sheet.
(b) Complete the last three columns in the 12/31/15 schedule above based upon the lower-of-cost-or-market rules.
(c) Prepare the entry(ies) necessary at 12/31/15 based on the data above.
(d) How are inventory losses disclosed on the income statement?
Selling price is $1.00/unit for all items. Disposal costs amount to 10% of selling price and a "normal" profit is 30% of selling price. There are 1,000 units of each item in the 12/31/15 inventory.
Instructions
(a) Prepare the entry at 12/31/14 necessary to implement the lower-of-cost-or-market procedure assuming Jenner uses a contra account for its balance sheet.
(b) Complete the last three columns in the 12/31/15 schedule above based upon the lower-of-cost-or-market rules.
(c) Prepare the entry(ies) necessary at 12/31/15 based on the data above.
(d) How are inventory losses disclosed on the income statement? (Essay)
4.9/5 (70)
(70) Oslo Corporation has two products in its ending inventory, each accounted for at the lower of cost or market. A profit margin of 30% on selling price is considered normal for each product. Specific data with respect to each product follows: 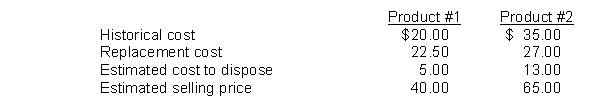 In pricing its ending inventory using the lower-of-cost-or-market, what unit values should Oslo use for products #1 and #2, respectively?
 (Multiple Choice)
4.9/5 (87)
(87) The lower-of-cost-or-market method is used for inventory despite being less conservative than valuing inventory at market value.
(True/False)
4.8/5 (82)
(82) The gross profit method can be used to approximate the dollar amount of inventory on hand.
(True/False)
4.8/5 (88)
(88) Boxer Inc. uses the conventional retail method to determine its ending inventory at cost. Assume the beginning inventory at cost (retail) were $196,500 ($297,000), purchases during the current year at cost (retail) were $1,704,000 ($2,596,800), freight-in on these purchases totaled $79,500, sales during the current year totaled $2,333,000, and net markups were $207,000. What is the ending inventory value at cost?
(Multiple Choice)
4.7/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)