



 Chat with AI
Exam 11: Depreciation, Impairments, and Depletion

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Glow Co. purchased machinery on January 2, 2009, for $660,000. The straight-line method is used and useful life is estimated to be 10 years, with a $60,000 salvage value. At the beginning of 2015 Glow spent $144,000 to overhaul the machinery. After the overhaul, Glow estimated that the useful life would be extended 4 years (14 years total), and the salvage value would be $30,000. The depreciation expense for 2015 should be
(Multiple Choice)
4.9/5  (73)
(73) On September 19, 2014, Markham Co. purchased machinery for $285,000. Salvage value was estimated to be $15,000. The machinery will be depreciated over eight years using the sum-of-the-years'-digits method. If depreciation is computed on the basis of the nearest full month, Markham should record depreciation expense for 2015 on this machinery of
(Multiple Choice)
4.8/5 (86)
(86) Companies frequently use the composite approach when the assets are similar in nature and have approximately the same useful lives.
(True/False)
4.8/5 (84)
(84) Depreciation is based on the decline in the fair market value of the asset.
(True/False)
4.8/5 (81)
(81) IFRS permits the same depreciation methods as U.S GAAP, with the exception of the units-of-production method, which is not allowed under IFRS.Answers to True / False questions
(True/False)
4.9/5 (87)
(87) Song Company purchased a depreciable asset for $350,000 on April 1, 2012. The estimated salvage value is $35,000, and the estimated useful life is 5 years. The straight-line method is used for depreciation. What is the balance in accumulated depreciation on May 1, 2015 when the asset is sold?
(Multiple Choice)
4.9/5 (78)
(78) Which of the following is not a difference between the accounting treatment for depreciation and cost depletion?
(Multiple Choice)
4.9/5 (73)
(73) Which of the following is not one of the basic questions that must be answered before the amount of depreciation charge can be computed?
(Multiple Choice)
4.9/5 (72)
(72) Harris Co. takes a full year's depreciation expense in the year of an asset's acquisition and no depreciation expense in the year of disposition. Data relating to one of Harris's depreciable assets at December 31, 2015 are as follows: 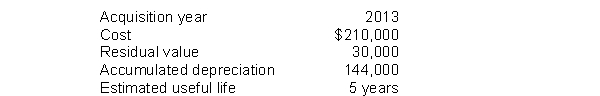 Using the same depreciation method as used in 2013, 2014, and 2015, how much depreciation expense should Harris record in 2016 for this asset?
 (Multiple Choice)
4.8/5 (75)
(75) During 2014, Node Co. sold equipment that had cost $294,000 for $176,400. This resulted in a gain of $12,900. The balance in Accumulated Depreciation-Equipment was $975,000 on January 1, 2014, and $930,000 on December 31. No other equipment was disposed of during 2014. Depreciation expense for 2014 was
(Multiple Choice)
4.7/5 (67)
(67) Under both IFRS and U.S. GAAP, interest costs incurred during construction must be capitalized.
(True/False)
4.7/5 (90)
(90) The major objection to the straight-line method is that it assumes the asset's economic usefulness and repair expense are the same each year.
(True/False)
4.9/5 (77)
(77) The profit margin on sales ratio is a measure for analyzing the use of property, plant, and equipment.
(True/False)
4.9/5 (66)
(66) Barton Corporation acquires a coal mine at a cost of $1,500,000. Intangible development costs total $360,000. After extraction has occurred, Barton must restore the property (estimated fair value of the obligation is $180,000), after which it can be sold for $510,000. Barton estimates that 5,000 tons of coal can be extracted. If 900 tons are extracted the first year, which of the following would be included in the journal entry to record depletion?
(Multiple Choice)
4.8/5 (71)
(71) A depreciable asset has an estimated 15% salvage value. At the end of its estimated useful life, the accumulated depreciation would equal the original cost of the asset under which of the following depreciation methods? 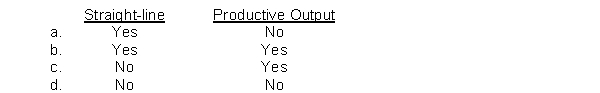
(Short Answer)
4.9/5 (74)
(74) Questions 7 through 10 are based on the following information:
Tongas Company applies revaluation accounting to plant assets with a carrying value of $1,600,000, a useful life of 4 years, and no salvage value. Depreciation is calculated on the straight-line basis. At the end of year 1, independent appraisers determine that the asset has a fair value of $1,500,000.
-The journal entry to record depreciation for year one will include a
(Multiple Choice)
4.8/5 (83)
(83) For income statement purposes, depreciation is a variable expense if the depreciation method used is
(Multiple Choice)
4.7/5 (73)
(73) The units-of-production approach to depreciation is appropriate when depreciation is a function of time instead of activity.
(True/False)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)