



 Chat with AI
Exam 4: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Erica transfers land worth $500,000, basis of $100,000, to a newly formed corporation, Robin Corporation, for all of Robin's stock, worth $300,000, and a 10-year note. The note was executed by Robin and made payable to Erica in the amount of $200,000. As a result of the transfer:
(Multiple Choice)
5.0/5  (72)
(72) The use of § 351 is not limited to the initial formation of a corporation, and it can apply to later transfers as well.
(True/False)
4.8/5 (89)
(89) What is the rationale underlying the tax deferral treatment available under § 351?
(Essay)
4.8/5 (87)
(87) Kim, a real estate dealer, and others form Eagle Corporation under § 351. Kim contributes inventory (land held for resale) in return for Eagle stock. The holding period for the stock includes the holding period of the inventory.
(True/False)
4.9/5 (90)
(90) Kevin and Nicole form Indigo Corporation with the following transfers: inventory from Kevin (basis of $360,000 and fair market value of $400,000) and improved real estate from Nicole (basis of $320,000 and fair market value of $375,000). Nicole, an accountant, agrees to contribute her services (worth $25,000) in organizing Indigo. The corporation's stock is distributed equally to Kevin and Nicole. As a result of these transfers:
(Multiple Choice)
4.7/5 (68)
(68) Because boot is generated under § 357(b) (i.e., the liability is not supported by a bona fide business purpose), the transferor shareholder will always have to recognize gain.
(True/False)
4.9/5 (74)
(74) In a § 351 transfer, a shareholder receives boot of $10,000 but ends up with a realized loss of $3,000. Only $7,000 of the boot will be taxed to the shareholder.
(True/False)
4.9/5 (72)
(72) Earl and Mary form Crow Corporation. Earl transfers property, basis of $200,000 and value of $1,600,000, for 50 shares in Crow Corporation. Mary transfers property, basis of $80,000 and value of $1,480,000, and agrees to serve as manager of Crow for one year; in return Mary receives 50 shares of Crow. The value of Mary's services is $120,000. With respect to the transfers:
(Multiple Choice)
4.7/5 (82)
(82) When a taxpayer transfers property subject to a mortgage to a controlled corporation in an exchange qualifying under § 351, the transferor shareholder's basis in stock received in the transferee corporation is increased by the amount of the mortgage on the property.
(True/False)
4.9/5 (80)
(80) Trish and Ron form Pine Corporation. Trish transfers inventory (basis of $60,000 and fair market value of $110,000) for 50% of the stock in Pine. Ron transfers machinery (basis of $20,000 and fair market value of $60,000) and agrees to serve as manager of Pine Corporation for one year for 50% of the stock. What are the tax consequences to Trish, Ron, and Pine Corporation?
(Essay)
4.8/5 (75)
(75) In structuring the capitalization of a corporation, the tax law is neutral for the investor as to debt versus equity financing.
(True/False)
4.9/5 (81)
(81) Eileen transfers property worth $200,000 (basis of $190,000) to Goldfinch Corporation. In return, she receives 80% of the stock in Goldfinch Corporation (fair market value of $180,000) and a long-term note (fair market value of $20,000) executed by Goldfinch and made payable to Eileen. Eileen recognizes gain on the transfer of:
(Multiple Choice)
4.7/5 (77)
(77) A taxpayer may never recognize a loss on the transfer of property in a transaction subject to § 351.
(True/False)
4.8/5 (70)
(70) A taxpayer transfers assets and liabilities to a corporation in return for its stock. If the liabilities exceed the basis of the assets transferred, the taxpayer will have a negative basis in the stock.
(True/False)
5.0/5 (78)
(78) Dick, a cash basis taxpayer, incorporates his sole proprietorship. He transfers the following items to newly created Orange Corporation. 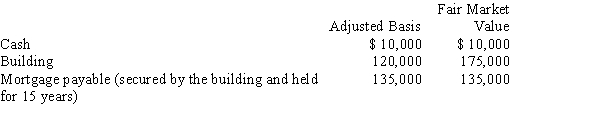
With respect to this transaction:
With respect to this transaction: (Multiple Choice)
4.9/5 (59)
(59) Ashley, a 70% shareholder of Wren Corporation, transfers property with a basis of $250,000 and a fair market value of $900,000 to Wren Corporation for additional stock. Ashley owns 78% of Wren after the transfer. Two other shareholders in Wren transfer a nominal amount of property to Wren along with Ashley's transfer so that Ashley and the two shareholders own 90% of the Wren stock after the transfer. Does Ashley have taxable gain on the transfer?
(Essay)
4.8/5 (69)
(69) George transfers cash of $150,000 to Finch Corporation, a newly formed corporation, for 100% of the stock in Finch worth $80,000 and debt in the amount of $70,000, payable in equal annual installments of $7,000 plus interest at the rate of 9% per annum. In the first year of operation, Finch has net taxable income of $40,000. If Finch pays George interest of $6,300 and $7,000 principal payment on the note:
(Multiple Choice)
4.9/5 (77)
(77) Wade and Paul form Swan Corporation with the following investments. Wade transfers machinery (basis of $40,000 and fair market value of $100,000), while Paul transfers land (basis of $20,000 and fair market value of $90,000) and services rendered (worth $10,000) in organizing the corporation. Each is issued 25 shares in Swan Corporation. With respect to the transfers:
(Multiple Choice)
4.9/5 (84)
(84) A shareholder's holding period for stock received under § 351 can include the holding period of the property transferred to the corporation.
(True/False)
5.0/5 (67)
(67) Leah transfers equipment (basis of $400,000 and fair market value of $500,000) for additional stock in Crow Corporation. After the transfer, Leah owns 80% of Crow's stock. Associated with the equipment is § 1245 depreciation recapture potential of $70,000. As a result of the transfer:
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)