



 Chat with AI
Exam 4: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


If both §§ 357(b) and (c) apply to the same transfer (i.e., the liability is not supported by a bona fide business purpose and also exceeds the basis of the properties transferred), § 357(c) predominates.
(True/False)
4.9/5  (91)
(91) In determining whether § 357(c) applies, assess whether the liabilities involved exceed the bases of all assets a shareholder transfers to the corporation.
(True/False)
4.7/5 (85)
(85) When Pheasant Corporation was formed under § 351, Kristen transferred property (basis of $26,000 and fair market value of $22,500) for § 1244 stock. Kristen's basis in the Pheasant stock is $26,000. Three years later, Pheasant Corporation goes bankrupt and its stock becomes worthless. Kristen, who is single, owned the stock as an investment. Kristen's loss is:
(Multiple Choice)
4.8/5 (65)
(65) The receipt of nonqualified preferred stock in exchange for the transfer of appreciated property to a controlled corporation results in recognition of gain to the transferor.
(True/False)
4.9/5 (97)
(97) A city contributes $500,000 to a corporation as an inducement to locate in the city. Within the next 12 months, the corporation uses the money to purchase property. The corporation has income of $500,000 and must reduce its tax basis in the property by the same amount.
(True/False)
4.7/5 (85)
(85) Rob and Fran form Bluebird Corporation with the following investments. 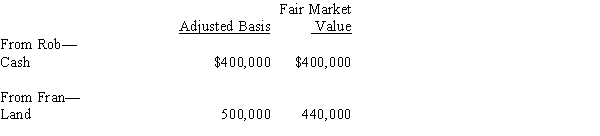
Each receives 50% of Bluebird's stock. In addition, Fran receives cash of $40,000. One result of these transfers is that Fran has a:
Each receives 50% of Bluebird's stock. In addition, Fran receives cash of $40,000. One result of these transfers is that Fran has a: (Multiple Choice)
4.8/5 (85)
(85) To help avoid the thin capitalization problem, it is advisable to make the repayment of the debt contingent upon the corporation's earnings.
(True/False)
4.9/5 (66)
(66) Dawn, a sole proprietor, was engaged in a service business and reported her income on a cash basis. Later, she incorporates her business and transfers the assets of the business to the corporation in return for all the stock in the corporation plus the corporation's assumption of the liabilities of her proprietorship. All the receivables and the unpaid trade payables are transferred to the newly formed corporation. The assets of the proprietorship had a basis of $105,000 and fair market value of $300,000. The trade accounts payable totaled $25,000. There was a note payable to the bank in the amount of $95,000 that the corporation assumes. The note was issued for the purchase of computers and other business equipment.
(Multiple Choice)
4.9/5 (90)
(90) Similar to like-kind exchanges, the receipt of "boot" under § 351 can cause loss to be recognized.
(True/False)
4.9/5 (82)
(82) Penny, Miesha, and Sabrina transfer property to Owl Corporation for 75% of its stock. Nancy, their attorney, receives 25% of the stock in Owl for legal services rendered in incorporating the business. What are the tax consequences of these transactions? How should this transaction have been handled?
(Essay)
4.9/5 (89)
(89) In order to induce Yellow Corporation to build a new manufacturing facility in Knoxville, Tennessee, the city donates land (fair market value of $400,000) and cash of $100,000 to the corporation. Several months after the donation, Yellow Corporation spends $450,000 (which includes the $100,000 received from Knoxville) on the construction of a new plant located on the donated land.
(Multiple Choice)
5.0/5 (71)
(71) A person who performs services for a corporation in exchange for stock cannot be treated as a member of the transferring group even if that person also transfers some property to the corporation.
(True/False)
4.9/5 (80)
(80) In general, the basis of property to a corporation in a transfer that qualifies as a nontaxable exchange under § 351 is the basis in the hands of the transferor shareholder decreased by the amount of any gain recognized on the transfer.
(True/False)
4.9/5 (76)
(76) Tina incorporates her sole proprietorship with assets having a fair market value of $100,000 and an adjusted basis of $110,000. Even though § 351 applies, Tina may recognize her realized loss of $10,000.
(True/False)
4.8/5 (67)
(67) In return for legal services worth $60,000 rendered incident to its formation, Crimson Corporation issues stock to Greta, an attorney. Crimson cannot immediately deduct the value of any of this stock but instead must capitalize it as an organizational expenditure.
(True/False)
4.8/5 (63)
(63) For transfers falling under § 351, what are the holding period rules for stock received by the shareholder and for the assets transferred to the corporation?
(Essay)
4.8/5 (85)
(85) When incorporating her sole proprietorship, Samantha transfers all of its assets and liabilities. Included in the $30,000 of liabilities assumed by the corporation is $500 that relates to a personal expenditure. Under these circumstances, the entire $30,000 will be treated as boot.
(True/False)
4.7/5 (89)
(89) George (an 80% shareholder) has made loans to Mountainview Corporation that become worthless in the current year. George is not employed by Mountainview.
(Multiple Choice)
4.7/5 (73)
(73) Adam transfers cash of $300,000 and land worth $200,000 to Camel Corporation for 100% of the stock in Camel. In the first year of operation, Camel has net taxable income of $70,000. If Camel distributes $50,000 to Adam:
(Multiple Choice)
4.9/5 (68)
(68) Gabriella and Juanita form Luster Corporation. Gabriella transfers cash of $50,000 for 50 shares of stock, while Juanita transfers information concerning a proprietary process (basis of zero and fair market value of $50,000) for 50 shares of stock.
(Multiple Choice)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)