



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return
-Loss deferral on intercompany transactions
(Multiple Choice)
4.8/5  (81)
(81) A tax-exempt charitable trust, created by a U.S. C corporation, can join in a Federal consolidated return.
(True/False)
4.9/5 (84)
(84) Calendar year Parent Corporation acquired all of the stock of SubCo on January 1, Year 1, for $500,000. The subsidiary's operating gains and losses are shown below. In addition, a $50,000 dividend is paid early in Year 2.
Complete the following chart, indicating the appropriate stock basis and excess loss account amounts. 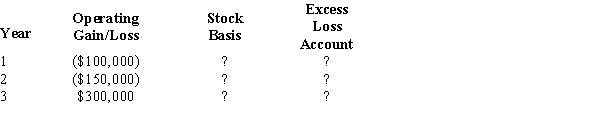
(Essay)
4.8/5 (69)
(69) ParentCo owns all of the stock of both SubOne and SubTwo. List three "intercompany transactions" that might occur among the three members of the consolidated filing group.
(Essay)
4.8/5 (69)
(69) Match each of the following items with the appropriate description, indicating whether the item's treatment for financial accounting and Federal income tax purposes is the same or not
-Sales amounts (after returns and allowances) are combined in the consolidation process.
(Multiple Choice)
4.9/5 (93)
(93) ParentCo and SubCo have filed consolidated returns since both entities were incorporated in 2012. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 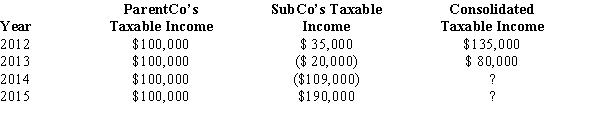 The 2014 consolidated loss:
 (Multiple Choice)
4.7/5 (79)
(79) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return
-Gain deferral on intercompany transactions
(Multiple Choice)
4.8/5 (85)
(85) Gold, Silver, and Bronze constitute a Federal consolidated tax return group. Which of the members is responsible to pay the tax liability-the parent, the subsidiaries, or both? How are these tax-payable amounts determined? Hint: Use the term tax-sharing agreement in your answer.
(Essay)
4.9/5 (82)
(82) ParentCo purchased 100% of SubCo's stock on January 1, 2014, and the companies have filed consolidated returns since then. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 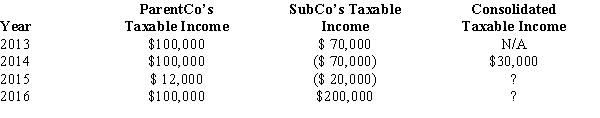 The 2015 net operating loss:
 (Multiple Choice)
4.7/5 (83)
(83) In computing consolidated taxable income, compensation amounts are removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
5.0/5 (74)
(74) SubCo sells an asset to ParentCo at a realized gain. While ParentCo still holds the asset, SubCo leaves the consolidated group. As a result:
(Multiple Choice)
4.9/5 (62)
(62) ParentCo, SubOne and SubTwo have filed consolidated returns since 2014. All of the entities were incorporated in 2013. Taxable income computations for the members include the following. None of the group members incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 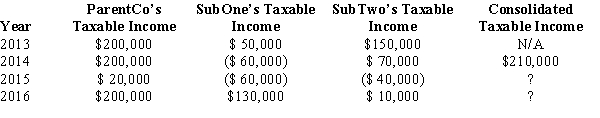 How should the 2015 consolidated net operating loss be apportioned among the group members?
ParentCo SubOne SubTwo
How should the 2015 consolidated net operating loss be apportioned among the group members?
ParentCo SubOne SubTwo (Multiple Choice)
4.8/5 (76)
(76) The ____________________ rules can limit the net operating loss deduction claimed on a Federal consolidated return.
(Essay)
4.9/5 (84)
(84) When a member departs from a consolidated group, it leaves behind any NOLs that it generated while in the group. The parent corporation and remaining affiliates apply those NOLs against future consolidated taxable income.
(True/False)
4.9/5 (76)
(76) A Federal consolidated group can claim a dividends received deduction for payments that the parent receives from other affiliates.
(True/False)
4.8/5 (80)
(80) The consolidated net operating loss of the Parent Group includes all of the following except:
(Multiple Choice)
5.0/5 (68)
(68) Which of the following entities is eligible to join in a Federal consolidated return?
(Multiple Choice)
4.8/5 (87)
(87) When an affiliated group elects to file Federal consolidated income tax returns, it gives up the ability to claim a ____________________ deduction for distributions of profits paid to other members.
(Short Answer)
4.8/5 (84)
(84) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return
-Tax compliance deadlines and recordkeeping
(Multiple Choice)
4.9/5 (82)
(82) In computing consolidated taxable income, the profit/loss from a sale between Subsidiary and Parent is an example of a(n) ____________________ item.
(Short Answer)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)