



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


A Federal consolidated filing group aggregates its separate charitable contributions for the tax year, deductions for which then are subject to an annual limitation of 10% of consolidated taxable income.
(True/False)
4.7/5  (81)
(81) Match each of the following terms with the appropriate description, in the context of a consolidated Federal income tax return
-Tax treatment of operating losses when the basis of the payor's stock is zero
(Multiple Choice)
4.7/5 (79)
(79) The Nanie consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss (NOL) that is apportioned to Minor. 
(Multiple Choice)
4.8/5 (74)
(74) The Maestro consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss (NOL) that is apportioned to Parent. 
(Multiple Choice)
4.9/5 (75)
(75) ParentCo and SubCo had the following items of income and deduction for the current year. 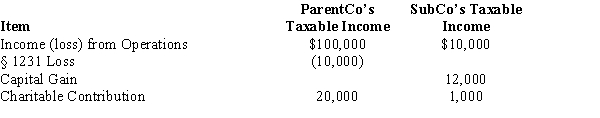 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
ParentCo SubCo (Multiple Choice)
4.9/5 (84)
(84) After a takeover, the parent's balance sheet shows a fair market value cost basis in the subsidiary, for both book and tax purposes.
(True/False)
4.8/5 (91)
(91) ParentCo's controlled group includes the following members. ParentCo owns all of the stock in each of the listed entities. Which entities can join ParentCo in a consolidated return?
∙
SubCoA, a manufacturer incorporated in India.
∙
SubCoB, a U.S. manufacturer.
∙
SubCoC, a U.S. S corporation.
∙
SubCoD, a U.S. partnership.
∙
SubCoE, a U.S. limited liability company (LLC).
∙
SubCoF, a U.S. manufacturer incorporated in Puerto Rico.
∙
SubCoG, a U.S. manufacturer that claims a deduction for its production activities (DPAD).
∙
SubCoH, a U.S. tax-exempt museum.
(Essay)
4.8/5 (99)
(99) All members of an affiliated group have ____________________ and ____________________ liability for each other's Federal income tax liabilities.
(Essay)
4.7/5 (95)
(95) ParentCo and SubOne have filed consolidated returns since 2012. SubTwo was formed in 2014 through an asset spin-off from ParentCo. SubTwo has joined in the filing of consolidated returns since then. Taxable income computations for the members include the following. None of the group members incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. 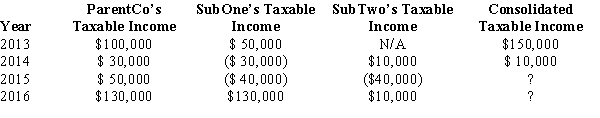 If ParentCo does not elect to forgo the carryback of the 2015 net operating loss, how much of the 2015 consolidated net operating loss is carried back to offset prior years' income?
 (Multiple Choice)
4.9/5 (71)
(71) In computing consolidated taxable income, the domestic production activities deduction (DPAD) is removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
4.8/5 (83)
(83) The rules for computing Federal consolidated taxable income are some of the most complex in the tax law.
(True/False)
4.9/5 (70)
(70) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary
-Member's capital gain
(Multiple Choice)
4.9/5 (83)
(83) Keep Corporation joined an affiliated group by merger in 2010. The group generated a 2016 consolidated NOL, and Keep's share of the loss was $50,000. Keep's share of the loss is included in the group's NOL carryforward to 2017.
(True/False)
4.7/5 (93)
(93) Match each of the following items with the appropriate description, indicating whether the item's treatment for financial accounting and Federal income tax purposes is the same or not
-Parent owns 100% of a U.S. partnership and wants the entity to join the consolidated group.
(Multiple Choice)
4.8/5 (77)
(77) Conformity among the members of a consolidated group must be implemented for which of the following tax items?
(Multiple Choice)
4.9/5 (75)
(75) Within a Federal consolidated income tax group, SubOne ____________________ (can/cannot) use the LIFO inventory method at the same time that SubTwo uses the FIFO method.
(Short Answer)
4.9/5 (80)
(80) All affiliates joining in a newly formed consolidated return must consent to the election on Form 1122, as attached to the Form 1120 for the group.
(True/False)
4.9/5 (66)
(66) Which of the following tax effects becomes more restrictive if an election is made to file a group's Federal corporate income tax returns on a consolidated basis?
(Multiple Choice)
4.8/5 (83)
(83) Parent Corporation's current-year taxable income included $100,000 net profit from operations and a $30,000 net long-term capital gain. Parent also made a $22,000 contribution to State University. SubCo produced $85,000 of income from operations and incurred a $25,000 net short-term capital loss.
Use the computational worksheet of Exhibit 8.3 to derive the group members' separate taxable incomes and the group's consolidated taxable income. 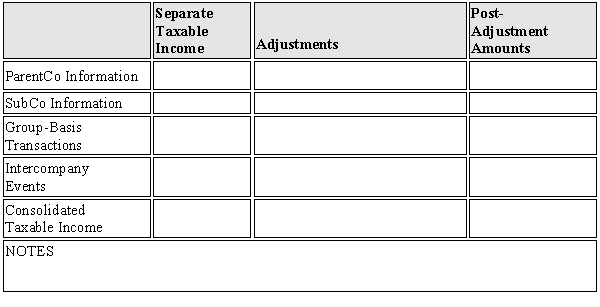
(Essay)
4.8/5 (71)
(71) A joint venture, taxed like a partnership, can join in a consolidated Federal income tax return.
(True/False)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)