



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


A city might assess a recording tax when a business takes out a mortgage on its real estate.
(True/False)
4.8/5  (77)
(77) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses
-State income tax expense.
(Multiple Choice)
4.8/5 (82)
(82) Trayne Corporation's sales office and manufacturing plant are located in State X. Trayne also maintains a manufacturing plant and sales office in State W. For purposes of apportionment, X defines payroll as all compensation paid to employees, including elective contributions to § 401(k) deferred compensation plans. Under the statutes of W, neither compensation paid to officers nor contributions to § 401(k) plans are included in the payroll factor. Trayne incurred the following personnel costs. 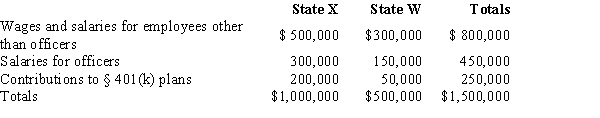 Trayne's payroll factor for State X is:
 (Multiple Choice)
4.8/5 (71)
(71) A taxpayer has nexus with a state for sales and use tax purposes if it has a physical presence in the state.
(True/False)
4.8/5 (89)
(89) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses
-Federal general business credit.
(Multiple Choice)
4.8/5 (83)
(83) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its A headquarters to a customer in B. This activity is not sufficient for General to create nexus with B. State B applies a throwback rule, but State A does not. In which state(s) will the sale be included in the sales factor numerator?
(Multiple Choice)
5.0/5 (69)
(69) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected
a.Taxable
b.Not taxable
-A textbook purchased by a State University student.
(Multiple Choice)
4.9/5 (92)
(92) Under P.L. 86-272, the taxpayer is exempt from state taxes on income resulting from the mere solicitation of orders for the sale of stocks and bonds.
(True/False)
4.8/5 (71)
(71) Parent Corporation owns all of the stock of Junior Corporation, a Delaware passive investment company. Parent operates strictly in nonunitary State B, which levies a 9% income tax. This year, Junior earned $200,000 of portfolio interest income and paid a $150,000 dividend to Parent. In which state(s) will the interest income create an income tax liability?
(Multiple Choice)
4.8/5 (81)
(81) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected
a.Taxable
b.Not taxable
-Earthmoving equipment used by the purchaser in construction business.
(Multiple Choice)
4.9/5 (78)
(78) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its A headquarters to an agency of the U.S. government. State A applies a throwback rule. In which state(s) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.9/5 (71)
(71) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its A headquarters to a customer in B. This activity is not sufficient for General to create nexus with B. State A applies a throwback rule, but State B does not. In which state(s) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.8/5 (77)
(77) If a state follows Federal income tax rules, the state's tax compliance and enforcement become easier to accomplish.
(True/False)
4.9/5 (83)
(83) All of the U.S. states use an apportionment formula based on the sales, property, and payroll factors.
(True/False)
4.7/5 (83)
(83) A state can levy an income tax on a business only if the business was incorporated in the state.
(True/False)
4.9/5 (66)
(66) Most states exempt consumer purchases of groceries from the collection of the local sales tax.
(True/False)
4.9/5 (80)
(80) For most taxpayers, which of the traditional apportionment factors yields the greatest opportunities for tax reduction?
(Multiple Choice)
4.9/5 (84)
(84) Typically exempt from the sales/use tax base is the purchase of prescription medicines by an individual.
(True/False)
4.8/5 (88)
(88) A typical state taxable income subtraction modification is the interest income earned from another state's bonds.
(True/False)
4.9/5 (87)
(87) Ramirez Corporation is subject to tax only in State A. Ramirez generated the following income and deductions. 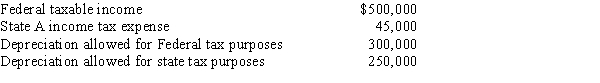
Federal taxable income is the starting point in computing A taxable income. State income taxes are not deductible for A tax purposes. Ramirez's A taxable income is:
Federal taxable income is the starting point in computing A taxable income. State income taxes are not deductible for A tax purposes. Ramirez's A taxable income is: (Multiple Choice)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)