



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Typically exempt from the sales/use tax base is the purchase of lumber by a do-it-yourself homeowner, when she builds a deck onto her patio. This exemption is known as the "homestead rule."
(True/False)
4.7/5  (76)
(76) Hendricks Corporation sells widgets in two states. State A levies a 9% effective tax rate, and State B levies a 3% rate. A and B have adopted sales-factor-only apportionment formulas. To reduce overall multistate income tax liabilities, Hendricks should:
(Multiple Choice)
4.9/5 (72)
(72) Typically, corporate income taxes constitute about 20 percent of a state's annual tax collections.
(True/False)
4.7/5 (73)
(73) Given the following transactions for the year, determine Comp Corporation's D payroll factor denominator. State D has adopted the principles of UDITPA. 
(Multiple Choice)
4.9/5 (71)
(71) Nonbusiness income receives tax-exempt treatment under all state corporate income taxes.
(True/False)
4.7/5 (82)
(82) The property factor includes land and buildings used for business purposes.
(True/False)
4.8/5 (104)
(104) State and local politicians tend to apply new and increased taxes to taxpayers who are visitors to the jurisdiction, such as a tax on auto rentals, because the taxpayer cannot vote to reelect the lawmaker.
(True/False)
4.8/5 (69)
(69) The property factor includes business assets that the taxpayer owns, but also those merely used under a lease agreement.
(True/False)
4.8/5 (83)
(83) Simpkin Corporation owns manufacturing facilities in States A, B, and C. A uses a three-factor apportionment formula under which the sales, property and payroll factors are equally weighted. B uses a three-factor apportionment formula under which sales are double-weighted. C employs a single-factor apportionment factor, based solely on sales.
Simpkin's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows. 
Simpkin's apportionable income assigned to B is:
Simpkin's apportionable income assigned to B is: (Multiple Choice)
5.0/5 (76)
(76) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected
a.Taxable
b.Not taxable
-A new auto purchased in Europe and shipped by the driver to her home state in the U.S.
(Multiple Choice)
4.8/5 (102)
(102) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected
a.Taxable
b.Not taxable
-A garment purchased by a self-employed actress.
(Multiple Choice)
4.9/5 (84)
(84) By making a water's edge election, the multinational taxpayer can limit the reach of unitary principles to the apportionment factors and income of its U.S. and E.U. affiliates.
(True/False)
4.9/5 (73)
(73) An LLC apportions and allocates its annual taxable income in the same manner used by any other business operating in the state.
(True/False)
4.7/5 (74)
(74) Match each of the following items with the appropriate description, in applying the P.L. 86-272 definition of solicitation
-Operating a warehouse for inventory that is held in the state.
(Multiple Choice)
4.9/5 (87)
(87) Most states begin the computation of corporate taxable income with an amount from the Federal income tax return.
(True/False)
4.9/5 (85)
(85) Chipper Corporation realized $1,000,000 taxable income from the sales of its products in States X and Z. Chipper's activities establish nexus for income tax purposes only in Z, the state of its incorporation. Chipper's sales, payroll, and property among the states include the following. 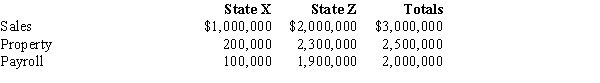
X utilizes a sales-only factor in its three-factor apportionment formula. How much of Chipper's taxable income is apportioned to X?
X utilizes a sales-only factor in its three-factor apportionment formula. How much of Chipper's taxable income is apportioned to X? (Multiple Choice)
4.8/5 (87)
(87) An assembly worker earns a $50,000 salary and receives a fringe benefit package worth $15,000. The payroll factor assigns $65,000 for this employee.
(True/False)
4.8/5 (81)
(81) Match each of the following events, considered independently, to its likely effect on WillCo's various apportionment factors. WillCo is based in Q and has customers in Q, R, and S. To this point, WillCo has not established nexus with S. More than one choice may be correct
-R adopts an increase in its statutory corporate income tax rates.
(Multiple Choice)
4.9/5 (90)
(90) Hopper Corporation's property holdings in State E are as follows. 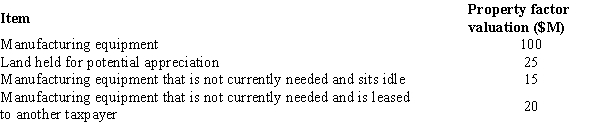 Compute the numerator of Hopper's E property factor.
 (Multiple Choice)
4.9/5 (95)
(95) Property taxes generally are collected by local taxing jurisdictions, not the state or Federal governments.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)