



 Chat with AI
Exam 17: Tax Practice and Ethics

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Juarez (a calendar year taxpayer) donates a painting to a local art museum (a qualified charity). The painting cost Juarez $2,000 ten years ago and, according to one of Juarez's friends (an amateur artist), now is worth $40,000. On his income tax return, Juarez deducts $40,000 as a Form 1040 charitable contribution. Upon later audit by the IRS, it is determined that the true value of the painting was $30,000. Assuming that Juarez is subject to a 25% marginal Federal income tax rate, his penalty for overvaluation is:
(Multiple Choice)
4.8/5  (78)
(78) Jenny prepared Steve's income tax returns for no compensation for 2013 and 2014. Jenny is Steve's mother. In 2016, the IRS notifies Steve that it will audit his returns for 2013 and 2014. Jenny cannot represent Steve during the audit of the returns, as she is not a "registered tax return preparer."
(True/False)
5.0/5 (73)
(73) CPA Liam discovers that last year's Form 1120 for his client PollCo claimed a $100,000 advertising deduction for a gift to candidates of the Green Party. AICPA tax ethics rules require that an amended return immediately be filed, as political expenditures are not deductible.
(True/False)
4.9/5 (78)
(78) Minnie, a calendar year taxpayer, filed a return correctly showing a zero Federal income tax liability for last year, because her Form 1040 showed various deductions and credits. For this tax year, Minnie's AGI is $120,000 and her tax liability is $20,000. To avoid a penalty for the current year, Minnie must make aggregate estimated tax payments of at least:
(Multiple Choice)
4.9/5 (83)
(83) The chief executive of the IRS is the _________________________.
(Short Answer)
4.9/5 (85)
(85) Juanita, who is subject to a 40% marginal Federal gift tax rate, made a gift of a sculpture to Bianca, valuing the property at $150,000. The IRS later valued the gift at $300,000. The applicable undervaluation penalty is:
(Multiple Choice)
4.8/5 (89)
(89) What are the chief responsibilities of the IRS Commissioner, and of the Chief Counsel of the IRS?
(Essay)
4.8/5 (75)
(75) Under Circular 230, tax preparer Winston cannot disclose to a mortgage banker the income level of her client Pickett, or other information acquired by preparing the return, without Pickett's permission.
(True/False)
4.8/5 (90)
(90) Troy Center Ltd. withheld from its employees' paychecks $200,000 in Federal income and Social Security taxes for the Monday, June 30 payroll. It then spent the $200,000 on equipment upgrades, missing altogether the August 2 due date for the tax remittances. How much does Troy now owe the government in taxes and penalties? Ignore interest accruals, and assume that the Treasury can prove that Troy's redirecting of the tax withholdings was willful.
(Essay)
4.9/5 (79)
(79) Circular 230 requires that a tax preparer provide training for the tax staff as to the latest changes in the tax law.
(True/False)
4.8/5 (79)
(79) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters might be used.
-Willful and reckless conduct.
(Multiple Choice)
4.7/5 (91)
(91) In the case of bad debts and worthless securities, the statute of limitations on claims for refund is three years.
(True/False)
4.9/5 (80)
(80) The usual three-year statute of limitations on additional tax assessments applies in the following situation(s).
(Multiple Choice)
4.9/5 (87)
(87) Yang, a calendar year taxpayer, did not file a tax return for 2007 because she honestly believed that no additional tax was due. In 2016, Yang is audited by the IRS and the agent assesses a deficiency of $17,000 for 2007. Yang need not pay this deficiency, since the three-year statute of limitations expired on April 15, 2011, meaning that the IRS no longer can adjust Yang's tax for the 2007 tax year.
(True/False)
4.7/5 (78)
(78) Which of the following is subject to tax return preparer penalties?
(Multiple Choice)
4.8/5 (65)
(65) Minnie, your tax client, has decided to dispute the Revenue Agent's Report. List and discuss at least four of your "next steps" as you prepare to represent Minnie concerning her tax issue within the IRS and in the courts.
(Essay)
4.8/5 (80)
(80) Jake, an individual calendar year taxpayer, incurred the following transactions. 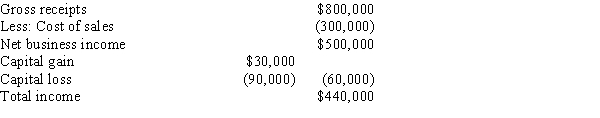 Assuming that any error in timely reporting these amounts was inadvertent, how much omission from gross income would be required before the six-year statute of limitations would apply?
 (Multiple Choice)
4.8/5 (81)
(81) Keepert uses "two sets of books." She only reports one-half of her cash sales on the records that she uses to complete her Federal income tax return. The statute of limitations for Keepert's return is six years.
(True/False)
5.0/5 (66)
(66) A tax preparer is in violation of Circular 230 if he or she:
(Multiple Choice)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)