



 Chat with AI
Exam 17: Tax Practice and Ethics

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Which of the following statements correctly reflects the rules governing interest to be paid on an individual's Federal tax deficiency or claim for refund?
(Multiple Choice)
4.7/5  (93)
(93) An IRS "office audit" takes place at the headquarters office of the corporate taxpayer.
(True/False)
4.9/5 (93)
(93) Loren Ltd., a calendar year taxpayer, had the following transactions, all of which were properly reported on a timely filed return. Presuming the absence of fraud, how much of an omission from gross income must occur for Loren before the six-year statute of limitations applies? Show your computations. 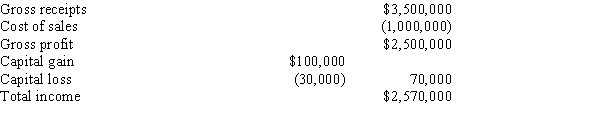
(Essay)
4.8/5 (91)
(91) A negligence penalty is assessed when the taxpayer is found to have not made a reasonable attempt to comply with the tax law.
(True/False)
5.0/5 (75)
(75) Megan prepared for compensation a Federal income tax return for Joan. Joan's return included an aggressive interpretation of the rules concerning overnight business travel. Megan is not liable for a preparer penalty for taking an unreasonable tax return position if:
(Multiple Choice)
4.8/5 (78)
(78) As part of a tax return engagement for XYZ Partnership, Enrolled Agent Wang can draft an amendment to the XYZ partnership agreement.
(True/False)
4.7/5 (82)
(82) Lisa, a calendar year taxpayer subject to a 33% marginal Federal income tax rate, claimed a Form 1040 charitable contribution deduction of $250,000 for a sculpture that the IRS later valued at $160,000. The applicable overvaluation penalty is:
(Multiple Choice)
4.9/5 (75)
(75) The tax ____________________ workpapers prepared as part of an independent financial audit are not privileged communications that can be kept confidential from an IRS subpoena.
(Short Answer)
4.9/5 (89)
(89) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters might be used.
-Filing an improper refund claim.
(Multiple Choice)
4.9/5 (97)
(97) A CPA, an attorney, and a(n) ____________________ can represent taxpayers before the IRS in an Appeals conference.
(Short Answer)
4.8/5 (86)
(86) In preparing a tax return, a CPA should verify "to the penny" every item of information submitted by a client about its deduction for repairs and maintenance.
(True/False)
4.7/5 (80)
(80) Jaime's negligence penalty will be waived, under the reasonable cause exception. He told the court, "My taxes were wrong because I couldn't understand the tax law."
(True/False)
4.8/5 (77)
(77) Freddie has been assessed a preparer penalty for willful and reckless conduct. When he completed Peggy's Federal income tax return (she is in the 33% tax bracket), Freddie purposely omitted $100,000 of cash receipts that should have been reported as gross income. Freddie charged Peggy $4,000 to prepare the return. What is Freddie's preparer penalty?
(Multiple Choice)
4.8/5 (75)
(75) A(n) ___________________ member is required to follow the Statements of Standards for Tax Services in conducting a tax practice.
(Short Answer)
4.7/5 (89)
(89) Linwell underpaid his taxes by $250,000. Portions of the underpayment were attributable to negligence ($210,000) and to civil fraud ($40,000). Compute the total penalties incurred.
(Essay)
4.9/5 (61)
(61) In a criminal fraud case, the burden is on the taxpayer to show that he or she was innocent "beyond the shadow of any reasonable doubt."
(True/False)
4.7/5 (80)
(80) For each of the indicated tax penalties, indicate the appropriate taxpayer defense. A letter may be used more than once. Not all of the letters might be used.
-Negligence in filing a return.
(Multiple Choice)
4.9/5 (74)
(74) CPA Norma and her client Colin hold a privilege of confidentiality from the IRS, as to their tax planning discussions about completing Colin's tax returns. The IRS cannot successfully subpoena records concerning these discussions.
(True/False)
4.9/5 (76)
(76) Lola, a calendar year taxpayer subject to a 40% marginal Federal gift tax rate, made a gift of a sculpture to Redd, valuing the property at $70,000. The IRS later valued the gift at $100,000. The applicable undervaluation penalty is:
(Multiple Choice)
4.9/5 (76)
(76) When a tax issue is taken to court, the burden of proof is on the IRS to show that its audit adjustments are correct.
(True/False)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)