



 Chat with AI
Exam 3: Where Prices Come From: the Interaction of Demand and Supply

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes420 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care337 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance512 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs326 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets256 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income260 Questions
Exam 20: Unemployment and Inflation290 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles251 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies261 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run305 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money, Banks, and the Federal Reserve System278 Questions
Exam 26: Monetary Policy280 Questions
Exam 27: Fiscal Policy313 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy277 Questions
Exam 30: The International Financial System258 Questions
Select questions type


An increase in the quantity of a product supplied is caused by an increase in the price of the product.
(True/False)
4.8/5  (83)
(83) As the number of firms in a market increases, the supply curve will shift to the right and the equilibrium quantity will rise.
(True/False)
4.9/5 (87)
(87) What would happen in the market for knee replacement surgery if insurance companies started to cover a smaller portion of the cost of the surgery?
(Multiple Choice)
4.7/5 (75)
(75) Figure 3-1 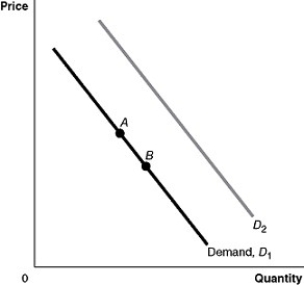 -Refer to Figure 3-1. If the product represented is an inferior good, a decrease in income would be represented by a movement from
 (Multiple Choice)
4.9/5 (81)
(81) Figure 3-8 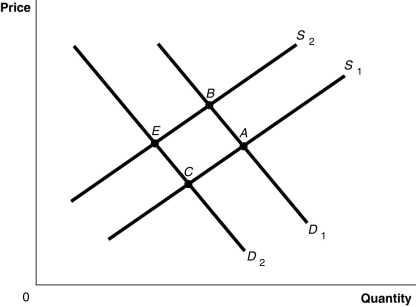 -Refer to Figure 3-8. The graph in this figure illustrates an initial competitive equilibrium in the market for motorcycles at the intersection of D2 and S1 (point C). Which of the following changes would cause the equilibrium to change to point B?
 (Multiple Choice)
4.8/5 (85)
(85) If the price of prime rib falls, the income effect due to the price change will cause
(Multiple Choice)
4.9/5 (80)
(80) If, in response to an increase in the price of pineapples, the quantity of pineapples demanded decreases, then economists would describe this as
(Multiple Choice)
4.9/5 (88)
(88) Figure 3-2 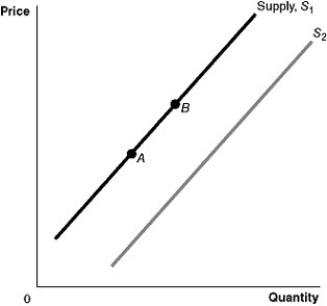 -Refer to Figure 3-2. A decrease in the number of firms in the market would be represented by a movement from
 (Multiple Choice)
4.8/5 (88)
(88) Assume that the demand curve for MP3 players shifts to the right and the supply curve for MP3 players shift to the left, but the supply curve shifts more than the demand curve. As a result
(Multiple Choice)
4.9/5 (72)
(72) According to the Australian Wool Innovation, severe drought conditions in Australia contributed to the lowest level of wool production in 50 years. This record low production has driven up prices sharply in Australian wool markets. Meanwhile, the price of raw cotton increased significantly for the first time in many years.
a. Illustrate this observation with one demand and supply graph for the market for Australian wool and another demand and supply graph for raw cotton.
b. Make sure that your graphs clearly show (1) the initial equilibrium before the decrease in the supply of Australian wool and (2) the final equilibrium.
c. Use arrows to indicate any shifts in the demand and supply curves for each market.
d. Label your graphs fully and write an explanation of your work.
(Essay)
4.8/5 (90)
(90) A shortage is defined as the situation that exists when the quantity of a good supplied is greater than the quantity demanded.
(True/False)
4.8/5 (76)
(76) Ranchers can raise either cattle or sheep on their land. Which of the following would cause the supply of sheep to increase?
(Multiple Choice)
4.8/5 (67)
(67) Figure 3-1
-Refer to Figure 3-1. A decrease in the expected future price of the product would be represented by a movement from
-Refer to Figure 3-1. A decrease in the expected future price of the product would be represented by a movement from (Multiple Choice)
4.8/5 (82)
(82) It is possible for a market for a good to experience a surplus and a shortage at the same time.
(True/False)
4.9/5 (79)
(79) Figure 3-1
-Refer to Figure 3-1. A decrease in the price of a substitute good would be represented by a movement from
-Refer to Figure 3-1. A decrease in the price of a substitute good would be represented by a movement from (Multiple Choice)
4.8/5 (90)
(90) If in the market for apples the supply has decreased, then
(Multiple Choice)
4.7/5 (75)
(75) Which of the following is evidence of a surplus of bananas?
(Multiple Choice)
4.8/5 (82)
(82) Table 3-3
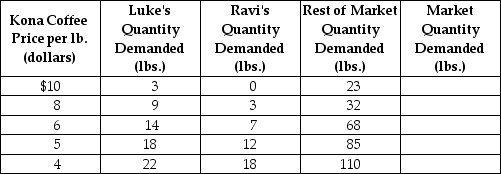 -Refer to Table 3-3. The table above shows the demand schedules for Kona coffee of two individuals (Luke and Ravi) and the rest of the market. If the price of Kona coffee rises from $4 to $5, the market quantity demanded would
 (Multiple Choice)
4.9/5 (86)
(86) The substitution effect explains why there is an inverse relationship between the price of a product and the quantity of the product demanded.
(True/False)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)