



 Chat with AI
Exam 12: Perfect Competition and the Supply Curve

Exam 1: First Principles199 Questions
Exam 2: Economic Models: Trade-Offs and Trade299 Questions
Exam 4: Consumer and Producer Surplus229 Questions
Exam 3: Supply and Demand265 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets216 Questions
Exam 6: Elasticity226 Questions
Exam 7: Taxes286 Questions
Exam 8: International Trade260 Questions
Exam 9: Decision Making by Individuals and Firms186 Questions
Exam 10: The Rational Consumer182 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs317 Questions
Exam 12: Perfect Competition and the Supply Curve341 Questions
Exam 13: Monopoly317 Questions
Exam 14: Oligopoly271 Questions
Exam 15: Monopolistic Competition and Product Differentiation245 Questions
Exam 16: Externalities193 Questions
Exam 17: Public Goods and Common Resources208 Questions
Exam 18: The Economics of the Welfare State126 Questions
Exam 19: Factor Markets and the Distribution of Income316 Questions
Exam 20: Uncertainty, Risk, and Private Information192 Questions
Exam 21: Graphs in Economics60 Questions
Exam 22: Consumer Preferences and Consumer Choice135 Questions
Select questions type


Use the following to answer question: 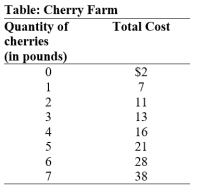 -(Table: Cherry Farm)Use Table: Cherry Farm.Suppose there are 100 farms in this industry with identical cost curves,as shown in the table.If the price is $4 per pound:
 (Multiple Choice)
4.9/5  (73)
(73) A perfectly competitive firm will earn a profit and will continue producing the profit-maximizing quantity of output in the short run if the price is:
(Multiple Choice)
4.9/5 (72)
(72) Use the following to answer question:  -(Figure: Game-Day Shirts)Use Figure: Game-Day Shirts.Rick is one of 10 vendors who sell game-day T-shirts at football games in a perfectly competitive market.His costs are identical to the costs of the other 9 vendors.When the industry is in long-run equilibrium,the price of each shirt will be _____,and the total quantity supplied in the market will be _____.
 (Multiple Choice)
4.7/5 (96)
(96) Use the following to answer question:  -(Figure: Marginal Decision Rule)Use Figure: The Marginal Decision Rule.At q2, or the _____,the _____ price is equal to marginal cost.
 (Multiple Choice)
4.9/5 (82)
(82) In the short run,the fixed costs of running a farm should play no role in determining the level of production.
(True/False)
4.7/5 (73)
(73) Provided that there are no external benefits or costs,resources are efficiently allocated for a perfectly competitive firm when:
(Multiple Choice)
4.8/5 (84)
(84) If firms are making positive economic profits in the short run,then in the long run:
(Multiple Choice)
4.9/5 (78)
(78) The marginal revenue received by a firm in a perfectly competitive market:
(Multiple Choice)
4.8/5 (83)
(83) Use the following to answer question: 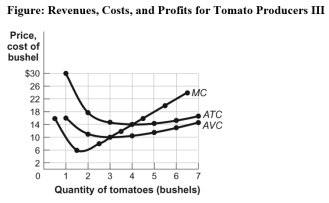 -(Figure: Revenues,Costs,and Profits for Tomato Producers III)Use Figure: Revenues,Costs,and Profits for Tomato Producers III.The market for tomatoes is perfectly competitive.The farm's short-run supply curve is the _____ cost curve above a price of _____.
 (Multiple Choice)
5.0/5 (70)
(70) A perfectly competitive firm will incur an economic loss but will continue to produce a positive quantity of output in the short run if the price is:
(Multiple Choice)
4.9/5 (86)
(86) Use the following to answer question: 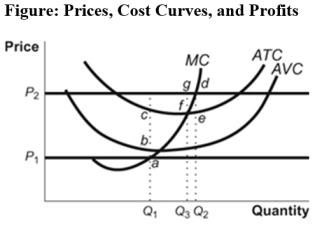 -(Figure: Prices,Cost Curves,and Profits)Use Figure: Prices,Cost Curves,and Profits.If the price is P1 and the firm decides to produce at output Q1,then the firm earns:
 (Multiple Choice)
4.9/5 (86)
(86) Use the following to answer question:
-(Table: Cherry Farm)Use Table: Cherry Farm.Suppose there are 100 farms in this industry with identical cost curves,as shown in the table.If all farms are the same size,how much will each farm produce in long-run equilibrium?
-(Table: Cherry Farm)Use Table: Cherry Farm.Suppose there are 100 farms in this industry with identical cost curves,as shown in the table.If all farms are the same size,how much will each farm produce in long-run equilibrium? (Multiple Choice)
4.8/5 (80)
(80) In the short run,a perfectly competitive firm produces output and earns an economic profit if:
(Multiple Choice)
4.9/5 (87)
(87) In long-run equilibrium in a perfectly competitive market,all firms will be operating at the same level of marginal cost.
(True/False)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)