



 Chat with AI
Exam 12: Perfect Competition and the Supply Curve

Exam 1: First Principles199 Questions
Exam 2: Economic Models: Trade-Offs and Trade299 Questions
Exam 4: Consumer and Producer Surplus229 Questions
Exam 3: Supply and Demand265 Questions
Exam 5: Price Controls and Quotas: Meddling With Markets216 Questions
Exam 6: Elasticity226 Questions
Exam 7: Taxes286 Questions
Exam 8: International Trade260 Questions
Exam 9: Decision Making by Individuals and Firms186 Questions
Exam 10: The Rational Consumer182 Questions
Exam 11: Behind the Supply Curve: Inputs and Costs317 Questions
Exam 12: Perfect Competition and the Supply Curve341 Questions
Exam 13: Monopoly317 Questions
Exam 14: Oligopoly271 Questions
Exam 15: Monopolistic Competition and Product Differentiation245 Questions
Exam 16: Externalities193 Questions
Exam 17: Public Goods and Common Resources208 Questions
Exam 18: The Economics of the Welfare State126 Questions
Exam 19: Factor Markets and the Distribution of Income316 Questions
Exam 20: Uncertainty, Risk, and Private Information192 Questions
Exam 21: Graphs in Economics60 Questions
Exam 22: Consumer Preferences and Consumer Choice135 Questions
Select questions type


Use the following to answer question: 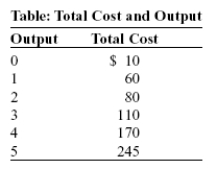 -(Table: Total Cost and Output)Use Table: Total Cost and Output,which describes Sergei's total costs for his perfectly competitive all-natural ice cream firm.If the market price of a tub of ice cream is $35,how much is Sergei's profit at the optimal short-run output?
 (Multiple Choice)
4.9/5  (85)
(85) If a California avocado stand operates in a perfectly competitive market,that stand's owner will be a price:
(Multiple Choice)
4.8/5 (83)
(83) Use the following to answer question:  -(Figure: Marginal Decision Rule)Use Figure: The Marginal Decision Rule.If P1 is the market price and if this firm is maximizing profit,it should produce:
 (Multiple Choice)
4.9/5 (88)
(88) Use the following to answer question: 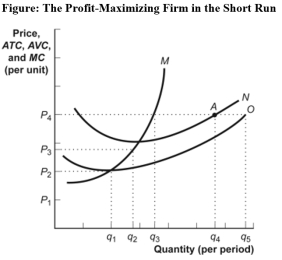 -(Figure: The Profit-Maximizing Firm in the Short Run)Use Figure: The Profit-Maximizing Firm in the Short Run.If the market price is P4,marginal revenue:
 (Multiple Choice)
4.9/5 (84)
(84) Use the following to answer question: 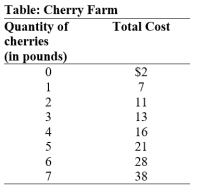 -(Table: Cherry Farm)Use Table: Cherry Farm.Suppose there are 100 farms in this industry with identical cost curves,as shown in the table.Which point would fall on the industry short-run supply curve?
 (Multiple Choice)
4.8/5 (76)
(76) The supply curve found by taking the horizontal summation of the short-run supply curves of all of the firms in a perfectly competitive industry is called the _____ curve.
(Multiple Choice)
4.7/5 (87)
(87) Suppose a perfectly competitive firm can increase its profits by increasing its output.Then it must be true that the firm's _____ exceeds its _____.
(Multiple Choice)
4.9/5 (86)
(86) Use the following to answer question:  -(Table: Variable Costs for Lawns)Use Table: Variable Costs for Lawns.During the summer,Alex runs a lawn-mowing service,and lawn-mowing is a perfectly competitive industry.Assume that costs are constant in each interval;so,for example,the marginal cost of mowing each of the lawns from 1 through 10 is $10.Also assume that he can only mow the quantities of lawn given in the table (and not numbers in between).His only fixed cost is $1,000 for the mower.His variable costs include fuel,his time,and mower parts.If the price for mowing a lawn is $60,how much is Alex's profit at the profit-maximizing output?
 (Multiple Choice)
4.8/5 (84)
(84) In a long-run equilibrium,economic profits in a perfectly competitive industry are:
(Multiple Choice)
4.8/5 (91)
(91) Use the following to answer question: 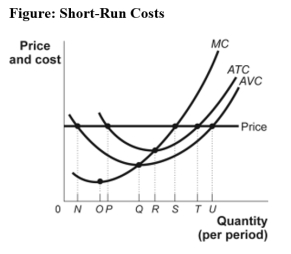 -(Figure: Short-Run Costs)Use Figure: Short-Run Costs.At the given price,the MOST profitable level of output occurs at quantity:
 (Multiple Choice)
4.8/5 (72)
(72) Use the following to answer question:
-(Table: Total Cost and Output)Use Table: Total Cost and Output,which describes Sergei's costs for his perfectly competitive all-natural ice cream firm.If the market price of a tub of ice cream is $67.50,how many tubs of ice cream will Sergei's firm produce?
-(Table: Total Cost and Output)Use Table: Total Cost and Output,which describes Sergei's costs for his perfectly competitive all-natural ice cream firm.If the market price of a tub of ice cream is $67.50,how many tubs of ice cream will Sergei's firm produce? (Multiple Choice)
4.9/5 (77)
(77) A perfectly competitive industry with constant costs initially operates in long-run equilibrium.When demand increases,in the long run and the short run:
(Multiple Choice)
4.9/5 (73)
(73) Use the following to answer question: 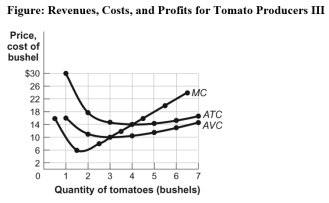 -(Figure: Revenues,Costs,and Profits for Tomato Producers III)Use Figure: Revenues,Costs,and Profits for Tomato Producers III.The market for tomatoes is perfectly competitive.If market price of a bushel of tomatoes is $18,in the short run the farmer's profit-maximizing output is _____ bushels.
 (Multiple Choice)
4.8/5 (84)
(84) Use the following to answer question:  -(Figure: A Perfectly Competitive Firm in the Short Run)Use Figure: A Perfectly Competitive Firm in the Short Run.The firm's total economic profit at its most profitable level of output is:
 (Multiple Choice)
4.8/5 (93)
(93) Use the following to answer question:
-(Table: Total Cost and Output)Use Table: Total Cost and Output,which describes Sergei's total costs for his perfectly competitive all natural ice cream firm.If there are 100 firms in the all-natural ice cream industry,which point falls on the industry short-run supply curve (assuming firms can only produce whole quantities of output)?
-(Table: Total Cost and Output)Use Table: Total Cost and Output,which describes Sergei's total costs for his perfectly competitive all natural ice cream firm.If there are 100 firms in the all-natural ice cream industry,which point falls on the industry short-run supply curve (assuming firms can only produce whole quantities of output)? (Multiple Choice)
4.9/5 (84)
(84) Use the following to answer question:  -(Figure: Total Cost for Tomato Producers)Use Figure: Total Cost for Tomato Producers.The market for tomatoes is perfectly competitive.The market price of a bushel of tomatoes is $14.The farmer's total cost at the profit-maximizing number of bushels is:
 (Multiple Choice)
4.8/5 (81)
(81) Use the following to answer question:
-(Table: Variable Costs for Lawns)Use Table: Variable Costs for Lawns.During the summer,Alex runs a lawn-mowing service,and lawn-mowing is a perfectly competitive industry.Assume that costs are constant in each interval;so,for example,the marginal cost of mowing each of the lawns from 1 through 10 is $10.Also assume that he can only mow the quantities of lawn given in the table (and not numbers in between).His only fixed cost is $1,000 for the mower.His variable costs include fuel,his time,and mower parts.If the price for mowing a lawn is $40,how much is Alex's profit at the profit-maximizing output?
-(Table: Variable Costs for Lawns)Use Table: Variable Costs for Lawns.During the summer,Alex runs a lawn-mowing service,and lawn-mowing is a perfectly competitive industry.Assume that costs are constant in each interval;so,for example,the marginal cost of mowing each of the lawns from 1 through 10 is $10.Also assume that he can only mow the quantities of lawn given in the table (and not numbers in between).His only fixed cost is $1,000 for the mower.His variable costs include fuel,his time,and mower parts.If the price for mowing a lawn is $40,how much is Alex's profit at the profit-maximizing output? (Multiple Choice)
4.8/5 (72)
(72) Use the following to answer question: 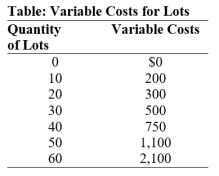 -(Table: Variable Costs for Lots)Use Table: Variable Costs for Lots.During the winter,Alexa runs a snow-clearing service in a perfectly competitive industry.Assume that costs are constant in each interval;so,for example,the marginal cost of clearing each of the lots from 1 through 10 is $20.Also assume that she can only plow the quantities of the lots given in the table (and not numbers in between).Her only fixed cost is $1,000 for a snowplow.Her variable costs include fuel,her time,and hot coffee.Which point falls on Alexa's short-run supply curve?
 (Multiple Choice)
4.8/5 (75)
(75) Use the following to answer question:
-(Figure: The Profit-Maximizing Firm in the Short Run)Use Figure: The Profit-Maximizing Firm in the Short Run.If the market price is less than P2,the firm will _____ in the short run.
-(Figure: The Profit-Maximizing Firm in the Short Run)Use Figure: The Profit-Maximizing Firm in the Short Run.If the market price is less than P2,the firm will _____ in the short run. (Multiple Choice)
4.9/5 (72)
(72) Suppose that some firms in a perfectly competitive industry are earning positive economic profits.In the long run,the:
(Multiple Choice)
4.7/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)