



 Chat with AI
Exam 19: Information for Decisions: Relevant Costs and Benefits

Exam 1: Management Accounting: Information for Creating Value and Managing Resources52 Questions
Exam 2: Management Accounting: Cost Terms and Concepts73 Questions
Exam 3: Cost Behaviour, Cost Drivers and Cost Estimation78 Questions
Exam 4: Product Costing Systems74 Questions
Exam 5: Process Costing and Operation Costing73 Questions
Exam 6: Service Costing78 Questions
Exam 7: A Closer Look at Overhead Costs85 Questions
Exam 8: Activity-Based Costing78 Questions
Exam 9: Budgeting Systems78 Questions
Exam 10: Standard Costs for Control: Direct Material and Direct Labour91 Questions
Exam 11: Standard Costs for Control: Flexible Budgets and Manufacturing Overhead97 Questions
Exam 12: Managing and Reporting Performance88 Questions
Exam 13: Financial Performance Measures and Incentive Schemes80 Questions
Exam 14: Strategic Performance Measurement Systems73 Questions
Exam 15: Managing Suppliers and Customers76 Questions
Exam 16: Managing Costs and Quality78 Questions
Exam 17: Sustainability and Management Accounting71 Questions
Exam 18: Cost Volume Profit Analysis97 Questions
Exam 19: Information for Decisions: Relevant Costs and Benefits95 Questions
Exam 20: Pricing and Product Mix Decisions95 Questions
Exam 21: Information for Capital Expenditure Decisions108 Questions
Select questions type


Criteria measured utilising quantitative terms include objectives such as:
(Multiple Choice)
4.9/5  (78)
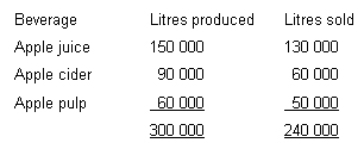
(78) A firm incurs manufacturing costs totalling $240 000 in process 1 to produce the following three beverages emerging from that process at the split-off point.Apple juice: sold immediately it emerges from Process 1 without further processing for $0.70 litre
Apple cider: processed further in Process 2 at an additional cost of $0.66667 litre,then sold for $1.50 litre
Apple pulp: processed further in Process 3 at an additional cost of $1.50 litre,then sold for $3.50 litre
The following data relates to the period in which the joint costs were incurred.What is the amount of joint cost that would be allocated to apple juice if the net realisable value method had been used?
(Multiple Choice)
4.8/5 (86)
(86) Which of the following statements about relevant information is/are true?
i.For information to be relevant,it must relate to the future
ii.For information to be relevant,it must differ between the alternatives.
iii.For information to be relevant,it must be completely accurate.
(Multiple Choice)
4.9/5 (91)
(91) Product costs incurred after the split-off point are called:
(Multiple Choice)
4.8/5 (72)
(72) Which of the following statements is/are true?
i.Accurate but irrelevant information is still useful for decision making
ii.Relevant,accurate,but not timely information is not useful in decision making.
iii.Relevant information that is known to have some weaknesses in accuracy still is useful in decision making.
(Multiple Choice)
4.7/5 (79)
(79) The method under which the relative magnitude of the final products' net realisable values is used to allocate the joint cost is the:
(Multiple Choice)
4.8/5 (92)
(92) In order to be relevant to a decision,cost or benefit information must involve ________,rather than ________.
(Multiple Choice)
4.8/5 (84)
(84) The most common trade-off in a decision situation is between information:
(Multiple Choice)
4.8/5 (84)
(84) When deciding whether to accept a special order,spare or idle capacity is not a factor that needs to be taken into account.
(True/False)
4.9/5 (67)
(67) Which of the following statements about the decision-making process is/are true?
i.The first step in the decision-making process is to define or clarify a decision problem into clear terms that can be addressed
ii.Before alternatives can be identified,the necessary data must first be collected.
iii.After the alternatives are identified,the criterion on which a decision will be made must be specified.
(Multiple Choice)
4.8/5 (84)
(84) When excess capacity exists,the only relevant cost associated with a special order will usually be which cost?
(Multiple Choice)
4.9/5 (80)
(80) SloGrowth has idle capacity.They have received a special order for 2000 units at a price of $6 per unit.Currently production and sales are budgeted for 20 000 units without considering the special order.Budget information for the year is presented below.Cost of goods sold includes $20 000 of fixed manufacturing cost.Determine the effect on profit if the special order is accepted. 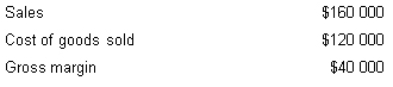
(Multiple Choice)
4.7/5 (75)
(75) Kragle Ltd manufacturers a number of specialised electronic components,including the advanced X1000.Kragle Ltd has the capacity to produce 10 000 units of X1000 per year.Currently it is operating at 80 per cent capacity.The selling price for X1000 is $100 per unit.The variable cost per unit is $30.Fixed cost allocated to producing X1000 is $200 000 per year.Kragle Ltd receives a special order for 2000 units of X1000.The opportunity cost associated with taking this special order is:
(Multiple Choice)
4.9/5 (88)
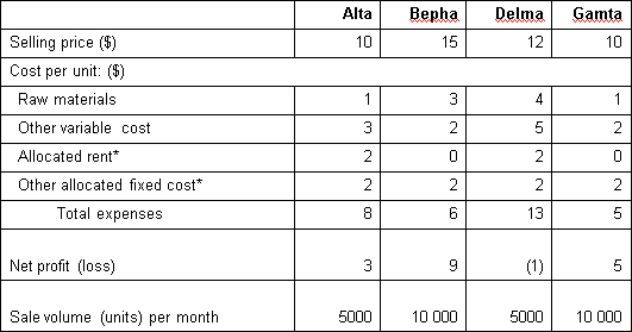
(88) Zoota Ltd makes four products: Alta,Bepha,Delma and Gamta.The selling price and per unit costs are show below.*Alta and Delma share the same factory;therefore,monthly rent is allocated equally between the two products.Other allocated monthly fixed costs include administrative costs,which are allocated based on a $2/unit charge.Zoota Ltd is planning to downsize by focusing on the two most profitable products,Bepha and Gamta,while discontinuing Alta and Delma.Which of the following are the correct assessments of the relevance of the items listed?
(Multiple Choice)
4.8/5 (82)
(82) Holt Pty Ltd presently makes 20 000 units of a certain part to use in production.The cost to make the part is $20 per unit including $15 in variable costs and $5 in fixed overhead applied.If Holt buys the part from Bricker,the cost would be $18 per unit and the released facilities could not be used for any other activity.Eighty per cent of the fixed overhead would continue.Determine the relevant costs to make the part.
(Multiple Choice)
4.9/5 (88)
(88) Contribution margin per machine hour can be calculated by dividing:
(Multiple Choice)
4.8/5 (72)
(72) Lido Products produces two products (A and B)from a joint process.The joint cost of production is $80 000.Five thousand units of Product A can be sold at split-off for $20 per unit or processed further at an additional cost of $20 000 and sold for $25 per unit.Ten thousand units of Product B can be sold at split-off for $15 per unit or processed further at an additional cost of $20 000 and sold for $16 per unit.What is the difference in profit if Lido decides to process further Product A,instead of selling it at split-off?
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)