



 Chat with AI
Exam 9: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models145 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System151 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Market Efficiency and Market Failure171 Questions
Exam 5: The Economics of Health Care117 Questions
Exam 6: Firms, the Stock Market, and Corporate Governance126 Questions
Exam 7: Consumer Choice and Elasticity193 Questions
Exam 8: Technology,production,and Costs147 Questions
Exam 9: Firms in Perfectly Competitive Markets153 Questions
Exam 10: Monopoly and Antitrust Policy148 Questions
Exam 11: Monopolistic Competition and Oligopoly200 Questions
Exam 12: GDP: Measuring Total Production and Income135 Questions
Exam 13: Unemployment and Inflation148 Questions
Exam 14: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 16: Money, banks, and the Federal Reserve System144 Questions
Exam 17: Monetary Policy145 Questions
Exam 18: Fiscal Policy143 Questions
Exam 19: Comparative Advantage,international Trade,and Exchange Rates158 Questions
Select questions type


Figure 9-4  Figure 9-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 9-4.If the market price is $30 and the firm is producing output,what is the amount of the firm's profit or loss?
Figure 9-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 9-4.If the market price is $30 and the firm is producing output,what is the amount of the firm's profit or loss? (Multiple Choice)
4.8/5  (70)
(70) The market demand curve for a perfectly competitive industry is the horizontal summation of each individual firm's demand curve.
(True/False)
4.9/5 (74)
(74) Table 9-1
 Table 9-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 9-1.If the market price of each camera case is $8,what is the profit-maximizing quantity?
Table 9-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 9-1.If the market price of each camera case is $8,what is the profit-maximizing quantity? (Multiple Choice)
4.8/5 (93)
(93) When a perfectly competitive firm finds that its market price is below its minimum average variable cost,it will sell
(Multiple Choice)
4.9/5 (96)
(96) If,for a perfectly competitive firm,price exceeds the marginal cost of production,the firm should
(Multiple Choice)
4.8/5 (87)
(87) Figure 9-9 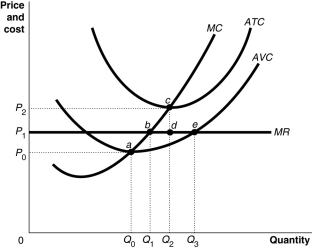 -Refer to Figure 9-9.Suppose the prevailing price is P1 and the firm is currently producing its loss-minimizing quantity.If the firm represented in the diagram continues to stay in business,in the long-run equilibrium,
 (Multiple Choice)
4.9/5 (76)
(76) Figure 9-5  Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost,perfectly competitive industry.
-Refer to Figure 9-5.The firm's manager suggests that the firm's goal should be to maximize average profit.If the firm does this,what is the amount of profit that it will earn?
Figure 9-5 shows cost and demand curves facing a typical firm in a constant-cost,perfectly competitive industry.
-Refer to Figure 9-5.The firm's manager suggests that the firm's goal should be to maximize average profit.If the firm does this,what is the amount of profit that it will earn? (Multiple Choice)
4.8/5 (87)
(87) A perfectly competitive firm breaks even at a price equal to its minimum average total cost.
(True/False)
4.8/5 (79)
(79) In an increasing-cost industry the long-run supply curve is upward sloping.
(True/False)
4.9/5 (72)
(72) Figure 9-1  -Refer to Figure 9-1.If the firm is producing 200 units,
 (Multiple Choice)
4.9/5 (81)
(81) Figure 9-6  Figure 9-6 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 9-6.At price P2,the firm would produce
Figure 9-6 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 9-6.At price P2,the firm would produce (Multiple Choice)
4.9/5 (74)
(74) A perfectly competitive market is in long-run equilibrium.At present there are 100 identical firms each producing 5,000 units of output.The prevailing market price is $20.Assume that each firm faces increasing marginal cost.Now suppose there is a sudden increase in demand for the industry's product which causes the price of the good to rise to $24.Which of the following describes the effect of this increase in demand on a typical firm in the industry?
(Multiple Choice)
4.7/5 (86)
(86) Figure 9-11 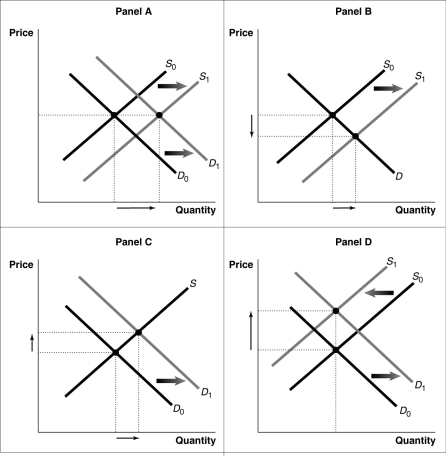 -Refer to Figure 9-11.Suppose a typical firm in a perfectly competitive market is earning economic profits in the short run.Which of the diagrams in the figure depicts what happens to in the industry as it transitions to along run equilibrium?
 (Multiple Choice)
4.9/5 (82)
(82) Without government subsidization,the conversion of farmland in the United Kingdom from conventional to organic production will generally cause a farmer's
(Multiple Choice)
4.9/5 (69)
(69) Apple introduced its iPhone 3G in July 2008 and within a month sales had topped 3 million units.By April 2009,more than 25,000 apps for the iPhone 3G were available in the iTunes store,an indication that in a competitive market
(Multiple Choice)
4.8/5 (54)
(54) In a graph with output on the horizontal axis and total revenue on the vertical axis,what is the shape of the total revenue curve for a perfectly competitive seller?
(Multiple Choice)
4.8/5 (76)
(76) In the short run,if price falls below a firm's minimum average total cost,the firm should shut down.
(True/False)
4.8/5 (81)
(81) Assume that the LCD and plasma television sets industry is perfectly competitive.Suppose a producer develops a successful innovation that enables it to lower its cost of production.What happens in the short run and in the long run?
(Multiple Choice)
4.7/5 (88)
(88) What is meant by productive efficiency? How does a perfectly competitive firm achieve productive efficiency?
(Essay)
5.0/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)