



 Chat with AI
Exam 9: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models145 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System151 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply149 Questions
Exam 4: Market Efficiency and Market Failure171 Questions
Exam 5: The Economics of Health Care117 Questions
Exam 6: Firms, the Stock Market, and Corporate Governance126 Questions
Exam 7: Consumer Choice and Elasticity193 Questions
Exam 8: Technology,production,and Costs147 Questions
Exam 9: Firms in Perfectly Competitive Markets153 Questions
Exam 10: Monopoly and Antitrust Policy148 Questions
Exam 11: Monopolistic Competition and Oligopoly200 Questions
Exam 12: GDP: Measuring Total Production and Income135 Questions
Exam 13: Unemployment and Inflation148 Questions
Exam 14: Economic Growth, the Financial System, and Business Cycles130 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis145 Questions
Exam 16: Money, banks, and the Federal Reserve System144 Questions
Exam 17: Monetary Policy145 Questions
Exam 18: Fiscal Policy143 Questions
Exam 19: Comparative Advantage,international Trade,and Exchange Rates158 Questions
Select questions type


Suppose Veronica sells teapots in the perfectly competitive teapot market.Her output per day and her costs are as follows:
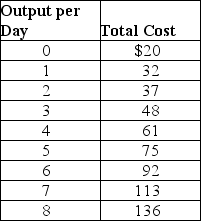 Suppose the current equilibrium price in the teapot market is $20.To maximize profit,how many teapots will Veronica produce,what price will she charge,and how much profit (or loss)will she make? Draw a graph to illustrate your answer.Your graph should include Veronica's demand,ATC,AVC,MC,and MR curves,the price she is charging,the quantity she is producing,and the area representing her profit (or loss).
 (Essay)
4.9/5  (58)
(58) Jason,a high-school student,mows lawns for families in his neighborhood.The going rate is $12 for each lawn-mowing service.Jason would like to charge $20 because he believes he has more experience mowing lawns than the many other teenagers who also offer the same service.If the market for lawn mowing services is perfectly competitive,what would happen if Jason raised his price?
(Multiple Choice)
4.7/5 (67)
(67) Figure 9-10 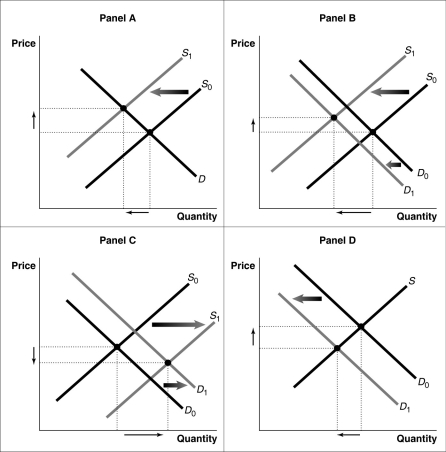 -Refer to Figure 9-10.Consider a typical firm in a perfectly competitive industry which is incurring short-run losses.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
5.0/5 (84)
(84) Which of the following describes a situation in which every good or service is produced up to the point where the last unit provides a marginal benefit to consumers equal to the marginal cost of producing it?
(Multiple Choice)
4.9/5 (76)
(76) Assume that price is greater than average variable cost.If a perfectly competitive firm is producing at an output where price is $114 and the marginal cost is $102,then the firm is probably producing more than its profit-maximizing quantity.
(True/False)
4.8/5 (84)
(84) The price of a seller's product in perfect competition is determined by
(Multiple Choice)
4.8/5 (77)
(77) Figure 9-6  Figure 9-6 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 9-6.Identify the short-run shut down point for the firm.
Figure 9-6 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 9-6.Identify the short-run shut down point for the firm. (Multiple Choice)
4.7/5 (92)
(92) All of the following can be used to compute average profit except
(Multiple Choice)
4.8/5 (87)
(87) Both buyers and sellers are price takers in a perfectly competitive market because
(Multiple Choice)
5.0/5 (87)
(87) Figure 9-4  Figure 9-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 9-4.What is the amount of its total fixed cost?
Figure 9-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 9-4.What is the amount of its total fixed cost? (Multiple Choice)
4.7/5 (74)
(74) Figure 9-7  -Refer to Figure 9-7.If this is a constant-cost industry,what is the market price in the long-run equilibrium?
 (Multiple Choice)
4.8/5 (89)
(89) If in the long run a firm makes zero profit,it should exit the industry.
(True/False)
4.7/5 (71)
(71) An individual seller in perfect competition will not sell at a price lower than the market price because
(Multiple Choice)
4.8/5 (82)
(82) A perfectly competitive firm's marginal revenue curve is downward sloping.
(True/False)
4.9/5 (63)
(63) A perfectly competitive wheat farmer in a constant-cost industry produces 3,000 bushels of wheat at a total cost of $36,000.The prevailing market price is $15.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.8/5 (72)
(72) Figure 9-2  -Refer to Figure 9-2.Suppose the firm is currently producing Q2 units.What happens if it expands output to Q3 units?
 (Multiple Choice)
4.9/5 (73)
(73) Assume the market for organic produce sold at farmers' markets is perfectly competitive.All else equal,as more farmers choose to produce and sell organic produce at farmers' markets,what is likely to happen to the equilibrium price of the produce and profits of the organic farmers in the long run?
(Multiple Choice)
4.9/5 (84)
(84) Suppose the equilibrium price in a perfectly competitive industry is $15 and a firm in the industry charges $21.Which of the following will happen?
(Multiple Choice)
4.7/5 (86)
(86) Figure 9-7
-Refer to Figure 9-7.Suppose the prevailing price is $20 and the firm is currently producing 1,350 units.In the long-run equilibrium,
-Refer to Figure 9-7.Suppose the prevailing price is $20 and the firm is currently producing 1,350 units.In the long-run equilibrium, (Multiple Choice)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)