



 Chat with AI
Exam 3: Consolidations - Subsequent to the Date of Acquisition

Exam 1: The Equity Method of Accounting for Investments119 Questions
Exam 2: Consolidation of Financial Information118 Questions
Exam 3: Consolidations - Subsequent to the Date of Acquisition121 Questions
Exam 4: Consolidated Financial Statements and Outside Ownership116 Questions
Exam 5: Consolidated Financial Statements - Intercompany Asset Transactions127 Questions
Exam 6: Intercompany Debt, Consolidated Statement of Cash Flows, and Other Issues114 Questions
Exam 7: Consolidated Financial Statements - Ownership Patterns and Income Taxes117 Questions
Exam 8: Segment and Interim Reporting113 Questions
Exam 9: Foreign Currency Transactions and Hedging Foreign Exchange Risk93 Questions
Exam 10: Translation of Foreign Currency Financial Statements97 Questions
Exam 11: Worldwide Accounting Diversity and International Accounting Standards60 Questions
Exam 12: Financial Reporting and the Securities and Exchange Commission76 Questions
Exam 13: Accounting for Legal Reorganizations and Liquidations83 Questions
Exam 14: Partnerships: Formation and Operation88 Questions
Exam 15: Partnerships: Termination and Liquidation70 Questions
Exam 16: Accounting for State and Local Governments78 Questions
Exam 17: Accounting for State and Local Governments51 Questions
Exam 18: Accounting for Not-For-Profit Organizations64 Questions
Exam 19: Accounting for Estates and Trusts80 Questions
Select questions type


Fesler Inc. acquired all of the outstanding common stock of Pickett Company on January 1, 2010. Annual amortization of $22,000 resulted from this transaction. On the date of the acquisition, Fesler reported retained earnings of $520,000 while Pickett reported a $240,000 balance for retained earnings. Fesler reported net income of $100,000 in 2010 and $68,000 in 2011, and paid dividends of $25,000 in dividends each year. Pickett reported net income of $24,000 in 2010 and $36,000 in 2011, and paid dividends of $10,000 in dividends each year.
Assume that Fesler's reported net income includes Equity in Subsidiary Income.
If the parent's net income reflected use of the partial equity method, what were the consolidated retained earnings on December 31, 2011?
(Essay)
4.9/5  (83)
(83) When consolidating a subsidiary under the equity method, which of the following statements is true with regard to the subsidiary subsequent to the year of acquisition?
(Multiple Choice)
4.9/5 (81)
(81) Pritchett Company recently acquired three businesses, recognizing goodwill in each acquisition. Destin has allocated its acquired goodwill to its three reporting units: Apple, Banana, and Carrot. Pritchett provides the following information in performing the 2011 annual review for impairment: 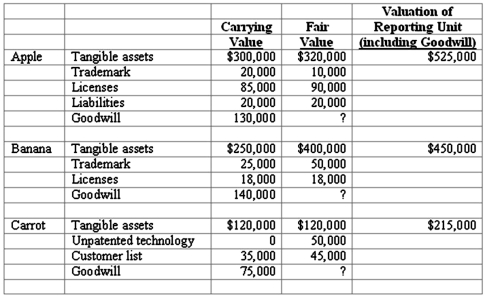 Which of Pritchett's reporting units require both steps to test for goodwill impairment?
 (Essay)
4.8/5 (75)
(75) All of the following are acceptable methods to account for a majority-owned investment in subsidiary except
(Multiple Choice)
4.9/5 (65)
(65) One company acquires another company in a combination accounted for as an acquisition. The acquiring company decides to apply the initial value method in accounting for the combination. What is one reason the acquiring company might have made this decision?
(Multiple Choice)
4.8/5 (83)
(83) Jans Inc. acquired all of the outstanding common stock of Tysk Corp. on January 1, 2009, for $372,000. Equipment with a ten-year life was undervalued on Tysk's financial records by $46,000. Tysk also owned an unrecorded customer list with an assessed fair value of $67,000 and an estimated remaining life of five years. Tysk earned reported net income of $180,000 in 2009 and $216,000 in 2010. Dividends of $70,000 were paid in each of these two years. Selected account balances as of December 31, 2011, for the two companies follow.  If the equity method had been applied, what would be the Investment in Tysk Corp. account balance within the records of Jans at the end of 2011?
 (Multiple Choice)
4.9/5 (82)
(82) Jaynes Inc. acquired all of Aaron Co.'s common stock on January 1, 2010, by issuing 11,000 shares of $1 par value common stock. Jaynes' shares had a $17 per share fair value. On that date, Aaron reported a net book value of $120,000. However, its equipment (with a five-year remaining life) was undervalued by $6,000 in the company's accounting records. Any excess of consideration transferred over fair value of assets and liabilities is assigned to an unrecorded patent to be amortized over ten years. 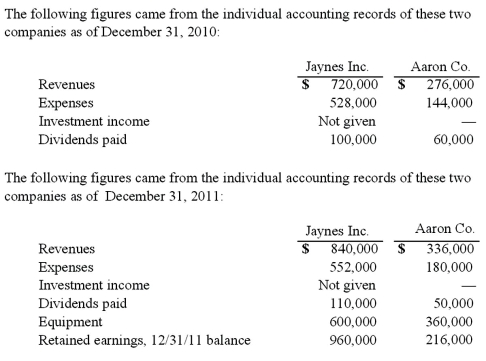 What was consolidated equipment as of December 31, 2011?
 (Essay)
4.8/5 (91)
(91) On January 1, 2010, Jumper Co. acquired all of the common stock of Cable Corp. for $540,000. Annual amortization associated with the purchase amounted to $1,800. During 2010, Cable earned net income of $54,000 and paid dividends of $24,000. Cable's net income and dividends for 2011 were $86,000 and $24,000, respectively.
Required:
Assuming that Jumper decided to use the partial equity method, prepare a schedule to show the balance in the investment account at the end of 2011.
(Essay)
4.7/5 (83)
(83) How is the fair value allocation of an intangible asset allocated to expense when the asset has no legal, regulatory, contractual, competitive, economic, or other factors that limit its life?
(Multiple Choice)
4.9/5 (70)
(70) Kaye Company acquired 100% of Fiore Company on January 1, 2011. Kaye paid $1,000 excess consideration over book value which is being amortized at $20 per year. Fiore reported net income of $400 in 2011 and paid dividends of $100. Assume the partial equity method is applied. How much will Kaye's income increase or decrease as a result of Fiore's operations?
(Multiple Choice)
4.9/5 (80)
(80) Following are selected accounts for Green Corporation and Vega Company as of December 31, 2013. Several of Green's accounts have been omitted.  Green acquired 100% of Vega on January 1, 2009, by issuing 10,500 shares of its $10 par value common stock with a fair value of $95 per share. On January 1, 2009, Vega's land was undervalued by $40,000, its buildings were overvalued by $30,000, and equipment was undervalued by $80,000. The buildings have a 20-year life and the equipment has a 10-year life. $50,000 was attributed to an unrecorded trademark with a 16-year remaining life. There was no goodwill associated with this investment. Compute the December 31, 2013, consolidated common stock.
 (Multiple Choice)
5.0/5 (86)
(86) From which methods can a parent choose for its internal recordkeeping related to the operations of a subsidiary?
(Essay)
4.8/5 (70)
(70) Consolidated net income using the equity method for an acquisition combination is computed as follows:
(Multiple Choice)
4.9/5 (67)
(67) Which of the following internal record-keeping methods can a parent choose to account for a subsidiary acquired in a business combination?
(Multiple Choice)
4.8/5 (79)
(79) Cashen Co. paid $2,400,000 to acquire all of the common stock of Janex Corp. on January 1, 2010. Janex's reported earnings for 2010 totaled $432,000, and it paid $120,000 in dividends during the year. The amortization of allocations related to the investment was $24,000. Cashen's net income, not including the investment, was $3,180,000, and it paid dividends of $900,000. On the consolidated financial statements for 2010, what amount should have been shown for Equity in Subsidiary Earnings?
(Multiple Choice)
4.7/5 (83)
(83) Following are selected accounts for Green Corporation and Vega Company as of December 31, 2013. Several of Green's accounts have been omitted.  Green acquired 100% of Vega on January 1, 2009, by issuing 10,500 shares of its $10 par value common stock with a fair value of $95 per share. On January 1, 2009, Vega's land was undervalued by $40,000, its buildings were overvalued by $30,000, and equipment was undervalued by $80,000. The buildings have a 20-year life and the equipment has a 10-year life. $50,000 was attributed to an unrecorded trademark with a 16-year remaining life. There was no goodwill associated with this investment. Compute the book value of Vega at January 1, 2009.
 (Multiple Choice)
4.8/5 (93)
(93) Perry Company acquires 100% of the stock of Hurley Corporation on January 1, 2010, for $3,800 cash. As of that date Hurley has the following trial balance;  Any excess of consideration transferred over fair value of net assets acquired is considered goodwill with an indefinite life. FIFO inventory valuation method is used. Compute the amount of Hurley's equipment that would be reported in a December 31, 2011, consolidated balance sheet.
 (Multiple Choice)
4.7/5 (89)
(89) Following are selected accounts for Green Corporation and Vega Company as of December 31, 2013. Several of Green's accounts have been omitted.  Green acquired 100% of Vega on January 1, 2009, by issuing 10,500 shares of its $10 par value common stock with a fair value of $95 per share. On January 1, 2009, Vega's land was undervalued by $40,000, its buildings were overvalued by $30,000, and equipment was undervalued by $80,000. The buildings have a 20-year life and the equipment has a 10-year life. $50,000 was attributed to an unrecorded trademark with a 16-year remaining life. There was no goodwill associated with this investment. Compute the December 31, 2013, consolidated additional paid-in capital.
 (Multiple Choice)
4.8/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)