



 Chat with AI
Exam 7: Consumer Choice and Elasticity

Exam 1: Economics: Foundations and Models160 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System191 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply241 Questions
Exam 4: Market Efficiency and Market Failure226 Questions
Exam 5: The Economics of Healthcare169 Questions
Exam 6: Firms,the Stock Market,and Corporate Governance255 Questions
Exam 7: Consumer Choice and Elasticity270 Questions
Exam 8: Technology, production, and Costs277 Questions
Exam 9: Firms in Perfectly Competitive Markets351 Questions
Exam 10: Monopoly and Antitrust253 Questions
Exam 11: Monopolistic Competition and Oligopoly304 Questions
Exam 12: GDP: Measuring Total Production and Income200 Questions
Exam 13: Unemployment and Inflation207 Questions
Exam 14: Economic Growth, the Financial System and Business Cycles172 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis120 Questions
Exam 16: Money, banks, and the Federal Reserve System139 Questions
Exam 17: Monetary Policy180 Questions
Exam 18: Fiscal Policy131 Questions
Exam 19: Comparative Advantage, international Trade, and Exchange Rates247 Questions
Select questions type


Producing where marginal revenue equals marginal cost is equivalent to producing where
(Multiple Choice)
4.9/5  (93)
(93) If,in a perfectly competitive industry,the market price facing a firm is below its average total cost but above average variable cost at the output where marginal cost equals marginal revenue,
(Multiple Choice)
4.9/5 (68)
(68) Suppose Veronica sells teapots in the perfectly competitive teapot market.Her output per day and her costs are as follows:
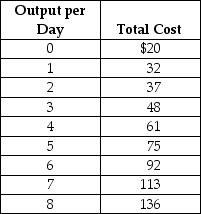 Suppose the current equilibrium price in the teapot market is $15.To maximise profit,how many teapots will Veronica produce,what price will she charge,and how much profit (or loss)will she make? Draw a graph to illustrate your answer.Your graph should include Veronica's demand,ATC,AVC,MC,and MR curves,the price she is charging,the quantity she is producing,and the area representing her profit (or loss).
 (Essay)
5.0/5 (79)
(79) The price a perfectly competitive firm receives for its output
(Multiple Choice)
4.7/5 (69)
(69) If total variable cost exceeds total revenue at all output levels,a perfectly competitive firm
(Multiple Choice)
4.9/5 (89)
(89) The market demand curve in a perfectly competitive market is downward sloping.
(True/False)
4.9/5 (88)
(88) Which of the following is not an option for a perfectly competitive firm that suffers short-run losses?
(Multiple Choice)
4.9/5 (72)
(72) Figure 7-4  Figure 7-4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7-4.If the market price is $30 and the firm is producing output,what is the amount of the firm's profit or loss?
Figure 7-4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7-4.If the market price is $30 and the firm is producing output,what is the amount of the firm's profit or loss? (Multiple Choice)
4.8/5 (64)
(64) A firm's total profit can be calculated as all of the following except
(Multiple Choice)
4.7/5 (78)
(78) The price of a seller's product in perfect competition is determined by
(Multiple Choice)
4.8/5 (73)
(73) If a firm in a perfectly competitive industry experiences persistent losses,in the long run it should
(Multiple Choice)
4.8/5 (83)
(83) Which of the following describes a situation in which every good or service is produced up to the point where the last unit provides a marginal benefit to consumers equal to the marginal cost of producing it?
(Multiple Choice)
4.8/5 (71)
(71) Figure 7-13 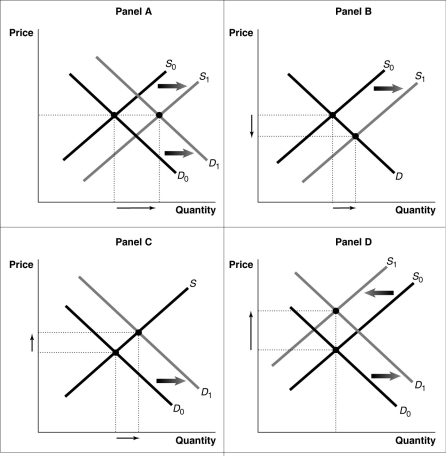 -Refer to Figure 7-13.Suppose a typical firm in a perfectly competitive market is earning economic profits in the short run.Which of the diagrams in the figure depicts what happens in the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.7/5 (83)
(83) If,in a perfectly competitive industry,the market price facing a firm is above its average total cost at the output where marginal revenue equals marginal cost,then
(Multiple Choice)
4.9/5 (67)
(67) Some markets have many buyers and sellers but fall into the category of monopolistic competition rather than perfect competition.The most common reason for this is
(Multiple Choice)
4.8/5 (73)
(73) Suppose there are economies of scale in the production of a specialised memory chip that is used in manufacturing microwaves.This suggests that the microwave industry is a decreasing-cost industry.
(True/False)
4.9/5 (82)
(82) Werner & Sons is a manufacturer of three-ring binders operating in a perfectly competitive industry.Table 7-4 shows the firm's cost schedule.
Table 7-4
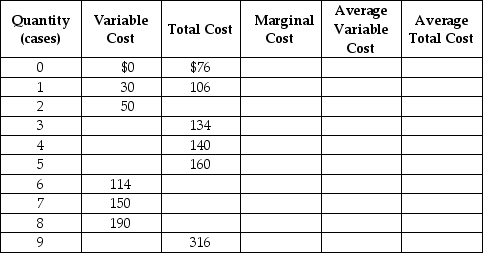 Use the table to answer the following questions.
a.Complete Table 7-4 by filling in the blank cells.
b.Werner is selling in a perfectly competitive market at a price of $40.What is the profit-maximising or loss-minimising output?
c.Calculate the firm's profit or loss.
d.Should the firm continue to produce in the short run? Explain.
e.If the firm's fixed costs were $30 higher,what would be the profit-maximising output level in the short run? Indicate whether the output level will increase,decrease or remain unchanged compared to your answer in b.
f.Suppose fixed cost remains at $76.If the price of three-ring binders falls to $20 what is the profit-maximising or loss-minimising output?
g.Calculate the profit or loss.Should the firm continue to produce in the short run? Explain your answer.
h.Suppose the fixed cost remains at $76.What price corresponds to the shutdown point?
i.Suppose the fixed cost remains at $76.What price corresponds to the break-even point?
Use the table to answer the following questions.
a.Complete Table 7-4 by filling in the blank cells.
b.Werner is selling in a perfectly competitive market at a price of $40.What is the profit-maximising or loss-minimising output?
c.Calculate the firm's profit or loss.
d.Should the firm continue to produce in the short run? Explain.
e.If the firm's fixed costs were $30 higher,what would be the profit-maximising output level in the short run? Indicate whether the output level will increase,decrease or remain unchanged compared to your answer in b.
f.Suppose fixed cost remains at $76.If the price of three-ring binders falls to $20 what is the profit-maximising or loss-minimising output?
g.Calculate the profit or loss.Should the firm continue to produce in the short run? Explain your answer.
h.Suppose the fixed cost remains at $76.What price corresponds to the shutdown point?
i.Suppose the fixed cost remains at $76.What price corresponds to the break-even point? (Essay)
4.9/5 (77)
(77) At the profit-maximising level of output for a perfectly competitive firm,price equals marginal cost.Which of the following is also true?
(Multiple Choice)
4.8/5 (71)
(71) Explain two different ways to determine the profit-maximising level of output for a firm in a perfectly competitive market.
(Essay)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)