



 Chat with AI
Exam 7: Consumer Choice and Elasticity

Exam 1: Economics: Foundations and Models160 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System191 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply241 Questions
Exam 4: Market Efficiency and Market Failure226 Questions
Exam 5: The Economics of Healthcare169 Questions
Exam 6: Firms,the Stock Market,and Corporate Governance255 Questions
Exam 7: Consumer Choice and Elasticity270 Questions
Exam 8: Technology, production, and Costs277 Questions
Exam 9: Firms in Perfectly Competitive Markets351 Questions
Exam 10: Monopoly and Antitrust253 Questions
Exam 11: Monopolistic Competition and Oligopoly304 Questions
Exam 12: GDP: Measuring Total Production and Income200 Questions
Exam 13: Unemployment and Inflation207 Questions
Exam 14: Economic Growth, the Financial System and Business Cycles172 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis120 Questions
Exam 16: Money, banks, and the Federal Reserve System139 Questions
Exam 17: Monetary Policy180 Questions
Exam 18: Fiscal Policy131 Questions
Exam 19: Comparative Advantage, international Trade, and Exchange Rates247 Questions
Select questions type


Suppose the equilibrium price in a perfectly competitive industry is $15 and a firm in the industry charges $21.Which of the following will happen?
(Multiple Choice)
4.9/5  (75)
(75) The long-run supply curve for a perfectly competitive,constant-cost industry
(Multiple Choice)
4.9/5 (71)
(71) Figure 7-4  Figure 7-4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7-4.If the market price is $30 and if the firm is producing output,what is the amount of its total variable cost?
Figure 7-4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7-4.If the market price is $30 and if the firm is producing output,what is the amount of its total variable cost? (Multiple Choice)
4.9/5 (84)
(84) Mark Frost grows apples in a perfectly competitive market.If we drew a line in a graph that illustrates Mark's total revenue from selling apples,it would be
(Multiple Choice)
4.8/5 (88)
(88) The demand curve for an individual seller's product in perfect competition is
(Multiple Choice)
5.0/5 (82)
(82) Figure 7-9 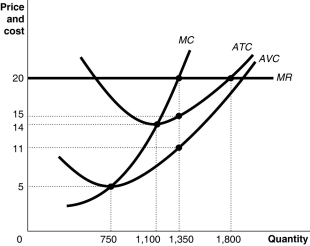 -Refer to Figure 7-9.If this is a constant-cost industry,what is the market price in the long-run equilibrium?
 (Multiple Choice)
4.8/5 (81)
(81) Firms in perfect competition produce the allocatively efficient output in the short run and in the long run.
(True/False)
4.8/5 (79)
(79) Perfectly competitive industries tend to produce low-priced,low-technology products.
(True/False)
4.8/5 (79)
(79) If a typical firm in a perfectly competitive industry is incurring losses,then
(Multiple Choice)
5.0/5 (79)
(79) Figure 7-15 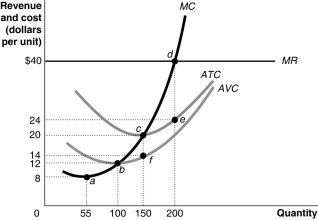 -Use Figure 7-15 to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximising output?
d.What is total revenue at the profit-maximising output?
e.What is the total cost at the profit-maximising output?
f.What is the profit or loss at the profit-maximising output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium,what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium,what is the firm's profit maximising quantity?
-Use Figure 7-15 to answer the following questions.
a.How can you determine that the figure represents a graph of a perfectly competitive firm? Be specific; indicate which curve gives you the information and how you use this information to arrive at your conclusion.
b.What is the market price?
c.What is the profit-maximising output?
d.What is total revenue at the profit-maximising output?
e.What is the total cost at the profit-maximising output?
f.What is the profit or loss at the profit-maximising output?
g.What is the firm's total fixed cost?
h.What is the total variable cost?
i.Identify the firm's short-run supply curve.
j.Is the industry in a long-run equilibrium?
k.If it is not in long-run equilibrium,what will happen in this industry to restore long-run equilibrium?
l.In long-run equilibrium,what is the firm's profit maximising quantity? (Essay)
5.0/5 (92)
(92) Figure 7-10 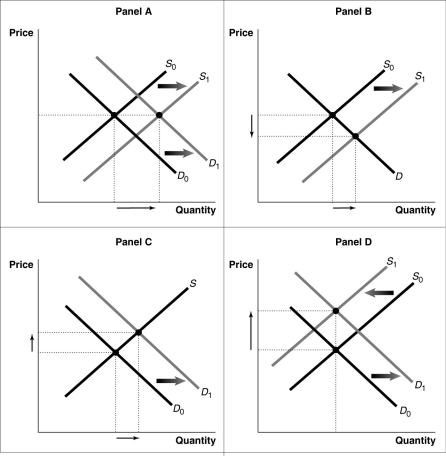 -Refer to Figure 7-10.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.9/5 (76)
(76) Figure 7-7 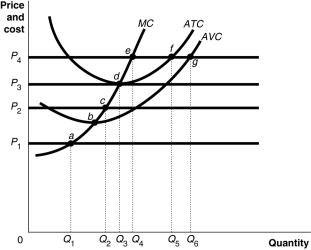 Figure 7-7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7-7.At price P4,the firm would
Figure 7-7 shows cost and demand curves facing a profit-maximising, perfectly competitive firm.
-Refer to Figure 7-7.At price P4,the firm would (Multiple Choice)
4.8/5 (80)
(80) Which of the following describes a difference between allocative efficiency and productive efficiency in a perfectly competitive market?
(Multiple Choice)
4.8/5 (71)
(71) In the short run,a profit-maximising firm will shut down if its total revenue is greater than its variable costs.
(True/False)
5.0/5 (92)
(92) In analysing the decision to shut down in the short run,we assume that the firm's fixed costs are
(Multiple Choice)
4.7/5 (90)
(90) Ted's Pancake Kitchen suffers a short-run loss.When should Ted decide to shut down rather than continue to produce?
(Multiple Choice)
4.7/5 (77)
(77) Figure 7-4 Figure 7-4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7-4.Assuming the firm is profit maximising,what is the amount of its total fixed cost?
Figure 7-4 shows the cost and demand curves for a profit-maximising firm in a perfectly competitive market.
-Refer to Figure 7-4.Assuming the firm is profit maximising,what is the amount of its total fixed cost? (Multiple Choice)
4.7/5 (78)
(78) When plasma television sets were first introduced,prices were high and few firms were in the market.Later,economic profits attracted new firms,and the price of plasma televisions fell.This example illustrates
(Multiple Choice)
4.7/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)