



 Chat with AI
Exam 6: Corporations: Redemptions and Liquidations

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


Explain the stock attribution rules that apply in the case of stock redemptions.
(Essay)
4.9/5  (74)
(74) A shareholder's holding period of property acquired in a stock redemption begins on the date of the distribution.
(True/False)
4.9/5 (81)
(81) Puffin Corporation's 2,000 shares outstanding are owned as follows: Paul,800 shares;Sandra (Paul's sister),800 shares;and Greta (Paul's granddaughter),400 shares.During the current year,Puffin (E & P of $1 million)redeemed 600 shares of Paul's stock for $100,000.If Paul had acquired the 600 shares five years ago for $30,000,he will have a long-term capital gain of $70,000 from the redemption.
(Essay)
4.9/5 (75)
(75) In a not essentially equivalent redemption [§ 302(b)(1)],the meaningful reduction test is an objective safe harbor rule that taxpayers can rely upon for sale or exchange treatment.
(True/False)
4.9/5 (82)
(82) Tammy forms White Corporation in a transaction qualifying under § 351.In that transaction,Tammy transferred cash and equipment in exchange for White Corporation common (1,000 shares)and preferred (200 shares)stock.The preferred stock is § 306 stock for Tammy.
(True/False)
4.7/5 (93)
(93) Corporate shareholders generally receive less favorable tax treatment from a qualifying stock redemption than from a dividend distribution.
(True/False)
4.7/5 (84)
(84) The adjusted gross estate of Debra,decedent,is $8 million.Debra's estate will incur death taxes and funeral and administration expenses of $1 million.Debra's gross estate includes stock in Silver Corporation that she had purchased twelve years ago for $600,000 (date of death fair market value of $3 million).At the time of her death in 2012,Debra owned 80% of the stock in Silver Corporation.Silver Corporation (E & P of $4 million)redeems all of the estate's stock in the corporation for $3 million.Debra's will names her daughter,Dena,who owns the remaining 20% interest in Silver Corporation,as her sole heir.With respect to this redemption,Debra's estate has the following income:
(Multiple Choice)
4.9/5 (90)
(90) Hazel,Emily,and Frank,unrelated individuals,own all of the stock in Wren Corporation (E & P of $1.2 million)as follows: Hazel,1,300 shares;Emily,400 shares;and Frank,300 shares.Wren redeems 300 of Hazel's shares (basis of $60,000)for $450,000.With respect to the distribution in redemption of the stock:
(Multiple Choice)
4.8/5 (89)
(89) Section 332 does not apply to a parent-subsidiary liquidation if the subsidiary corporation is insolvent on the date of the liquidation.
(True/False)
4.8/5 (87)
(87) The sale of § 306 stock to a third party results in dividend income to the shareholder.
(True/False)
4.9/5 (88)
(88) Sparrow Corporation purchased 90% of the stock of Warbler Corporation eight years ago for $1 million.In the current year,Sparrow liquidates Warbler and acquires assets with a basis to Warbler of $850,000 (fair market value of $1.2 million).Sparrow will have a basis in the assets of $850,000 (Warbler's basis in the assets),and a recognized loss of $150,000 ($1 million basis in Warbler stock - $850,000 carryover basis in assets).
(True/False)
4.8/5 (86)
(86) Ivory Corporation (E & P of $650,000)has 1,000 shares of common stock outstanding owned by unrelated parties as follows: Veronica,500 shares,and Tommie,500 shares.Veronica and Tommie each paid $125 per share for the Ivory stock 12 years ago.In May of the current year,Ivory distributes securities held as an investment (basis of $140,000,fair market value of $250,000)to Veronica in redemption of 200 of her shares.
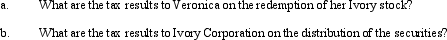
(Essay)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)