



 Chat with AI
Exam 6: Corporations: Redemptions and Liquidations

Exam 1: Understanding and Working With the Federal Tax Law68 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations110 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions98 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations116 Questions
Exam 8: Consolidated Tax Returns141 Questions
Exam 9: Taxation of International Transactions149 Questions
Exam 10: Partnerships: Formation, operation, and Basis99 Questions
Exam 11: Partnerships: Distributions, transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations154 Questions
Exam 13: Comparative Forms of Doing Business141 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities145 Questions
Exam 16: Multistate Corporate Taxation145 Questions
Exam 17: Tax Practice and Ethics152 Questions
Exam 18: The Federal Gift and Estate Taxes170 Questions
Exam 19: Family Tax Planning149 Questions
Exam 20: Income Taxation of Trusts and Estates150 Questions
Select questions type


Kite Corporation has 1,000 shares of stock outstanding.Kent owns 300 shares,Kent's father owns 200 shares,Kent's daughter owns 100 shares,and Kent's aunt owns 200 shares.Plover Corporation owns the other 200 shares in Kite Corporation.Kent owns 75% of the stock in Plover Corporation.Applying the § 318 stock attribution rules,how many shares does Kent own in Kite Corporation?
(Multiple Choice)
4.9/5  (90)
(90) Tanya is in the 35% tax bracket.She acquired 1,000 shares of stock in Swan Corporation seven years ago for $250 a share.In the current year,Swan Corporation (E & P of $1.2 million)redeems all of her shares for $400,000.What are the tax consequences to Tanya if:
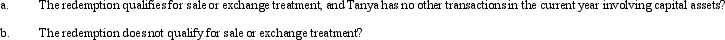
(Essay)
4.9/5 (85)
(85) The stock of Penguin Corporation is held as follows: 85% by Duck Corporation and 15% by Gerald,an individual.Penguin Corporation is liquidated in December of the current year,pursuant to a plan adopted earlier in the year.Penguin Corporation distributes land with a basis of $350,000 and fair market value of $390,000 to Gerald in liquidation of his stock interest.Gerald had a basis of $200,000 in his Penguin stock.How much gain will Penguin Corporation recognize in this liquidating distribution?
(Multiple Choice)
4.7/5 (78)
(78) Which of the following is a correct statement regarding a redemption to pay death taxes under § 303?
(Multiple Choice)
4.9/5 (94)
(94) A subsidiary corporation is liquidated at a time when it is indebted to its parent corporation.The subsidiary corporation distributes property to the parent corporation in satisfaction of the indebtedness.If the liquidation is governed by § 332,neither the subsidiary nor the parent recognize gain or loss on the transfer of property in satisfaction of indebtedness.
(True/False)
4.8/5 (74)
(74) On March 16,2011,Blue Corporation purchased 10% of the Gold Corporation stock outstanding.Blue Corporation purchased an additional 40% of the stock in Gold on October 24,2011,and an additional 25% on April 4,2012.On July 23,2012,Blue Corporation purchased the remaining 25% of Gold Corporation stock outstanding.
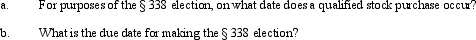
(Essay)
4.9/5 (81)
(81) One difference between the tax treatment accorded nonliquidating and liquidating distributions is with respect to the recognition of losses by the distributing corporation.As a general rule,a corporation recognizes losses on liquidating distributions of depreciated property (fair market value less than basis)but not on nonliquidating distributions of such property.
(True/False)
4.7/5 (67)
(67) The stock of Cardinal Corporation is held as follows: 90% by Blue Jay Corporation (basis of $500,000)and 10% by Samuel (basis of $70,000).Cardinal Corporation is liquidated in October of the current year,pursuant to a plan adopted earlier in the year.Pursuant to the liquidation,Cardinal Corporation distributed Asset A (basis of $450,000,fair market value of $720,000)to Blue Jay,and Asset B (basis of $45,000,fair market value of $80,000)to Samuel.No election is made under § 338.With respect to the liquidation of Cardinal:
(Multiple Choice)
4.7/5 (76)
(76) Egret Corporation has manufactured recreational vehicles for 8 years.In addition,for the last 3 years,Egret has operated a separate division that sells bicycle equipment.Francis,an individual,and Loon Corporation each acquired 500 shares of stock in Egret (basis of $2,000 per share)10 years ago.In the current year,the bicycle equipment division is entirely destroyed by fire.Egret Corporation decides to discontinue the business and distributes pro rata all of the $5 million of insurance proceeds collected as a result of the fire to Francis and Loon Corporation in redemption of 200 shares of stock from each shareholder.Determine the tax consequences of the stock redemption to Egret Corporation (E & P of $6 million),to Francis,and to Loon Corporation.
(Essay)
4.7/5 (77)
(77) During the current year,Goldfinch Corporation purchased 100% of the stock of Dove Corporation and made a qualified election under § 338.Which of the following statements is incorrect with respect to the § 338 election?
(Multiple Choice)
4.8/5 (71)
(71) Compare the sale of a corporation's assets with a sale of its stock from the perspective of the seller.
(Essay)
4.9/5 (72)
(72) In the current year,Loon Corporation made a distribution in redemption of some of its shares.Loon incurred expenditures in connection with the redemption totaling $35,000 (accounting fees of $9,000,legal fees of $20,000,and brokerage fees of $6,000).The distribution was a qualifying stock redemption.How much of the $35,000 is deductible in the current year?
(Multiple Choice)
4.7/5 (86)
(86) For purposes of the application of § 304 (redemptions through the use of related corporations),a shareholder must own (directly or indirectly)at least 50% of the stock of two more corporations.
(True/False)
4.8/5 (82)
(82) Which of the following is an incorrect statement regarding the application of the § 318 stock attribution rules?
(Multiple Choice)
4.8/5 (83)
(83) To qualify a partial liquidation under the termination of a business test,the distribution must consist of the proceeds from the sale of a qualified trade or business.
(True/False)
4.7/5 (85)
(85) To carry out a qualifying stock redemption,Turaco Corporation (E & P of $800,000)transfers land held for investment purposes to Aida,a shareholder.The land had a basis of $250,000,a fair market value of $400,000,and is subject to a $300,000 liability.Aida has a basis of $70,000 in the shares redeemed.Which of the following is a correct statement regarding the tax consequences of this redemption?
(Multiple Choice)
4.8/5 (86)
(86) The stock in Tangerine Corporation is held by two unrelated individuals,Janet (60%)and Joaquin (40%).One year before the liquidation of Tangerine,the shareholders transfer properties to the corporation in a transaction that qualifies under § 351.Included in that transfer was land (basis of $600,000,fair market value of $650,000).Pursuant to its liquidation in the current year,Tangerine Corporation distributes the land (now worth $500,000)pro rata to the shareholders.What amount of loss will Tangerine recognize on the distribution?
(Multiple Choice)
4.9/5 (85)
(85) For purposes of a partial liquidation,the termination of a business test is a subjective test that should be relied upon only after obtaining a favorable ruling from the IRS.
(True/False)
4.8/5 (88)
(88) Which of the following statements is correct with respect to the § 338 election?
(Multiple Choice)
4.9/5 (78)
(78) Reginald and Roland (Reginald's son)each own 50% of the stock of Robin Corporation.Reginald's stock interest is entirely redeemed by Robin Corporation.Two years later,Reginald loans Robin Corporation $250,000.The loan to Robin Corporation does not constitute a prohibited interest for purposes of the family attribution waiver.
(True/False)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)