



 Chat with AI
Exam 15: Cost Allocation: Joint Products and Byproducts

Exam 1: The Accountants Vital Role in Decision Making141 Questions
Exam 2: An Introduction to Cost Terms and Purposes171 Questions
Exam 3: Cost-Volume-Profit Analysis156 Questions
Exam 4: Job Costing145 Questions
Exam 5: Activity-Based Costing and Management144 Questions
Exam 6: Master Budget and Responsibility Accounting170 Questions
Exam 7: Flexible Budgets,variances,and Management Control: I172 Questions
Exam 8: Flexible Budgets,variances,and Management Control: II148 Questions
Exam 9: Income Effects of Denominator Level on Inventory Valuation171 Questions
Exam 10: Analysis of Cost Behaviour212 Questions
Exam 11: Decision Making and Relevant Information174 Questions
Exam 12: Pricing Decisions, product Profitability Decisions, and Cost Management150 Questions
Exam 13: Strategy,balanced Scorecard,and Profitability Analysis161 Questions
Exam 14: Period Cost Allocation163 Questions
Exam 15: Cost Allocation: Joint Products and Byproducts167 Questions
Exam 16: Revenue and Customer Profitability Analysis152 Questions
Exam 17: Process Costing147 Questions
Exam 18: Spoilage, rework, and Scrap137 Questions
Exam 19: Inventory Cost Management Strategies152 Questions
Exam 20: Capital Budgeting: Methods of Investment Analysis187 Questions
Exam 21: Transfer Pricing and Multinational Management Control Systems157 Questions
Exam 22: Multinational Performance Measurement and Compensation156 Questions
Select questions type


Costs which are assignable beyond the splitoff point at which individual products emerge are called
(Multiple Choice)
4.8/5  (66)
(66) The cause-and-effect criterion is not present when joint costing is used.
(True/False)
4.9/5 (86)
(86) Yip Manufacturing purchases trees from Cheney Lumber and processes them up to the splitoff point where two products (paper and pencil casings)are obtained.The products are then sold to an independent company that markets and distributes them to retail outlets.The following information was collected for the month of May:
 The cost of purchasing 100 trees and processing them up to the splitoff point to yield 70,000 sheets of paper and 60,000 pencil casings is $3,000.
Yip's Manufacturing's accounting department reported no beginning inventories and an ending inventory of 2,000 sheets of paper.
What are the paper's and the pencils' approximate weighted cost proportions using the sales value at splitoff method,respectively?
The cost of purchasing 100 trees and processing them up to the splitoff point to yield 70,000 sheets of paper and 60,000 pencil casings is $3,000.
Yip's Manufacturing's accounting department reported no beginning inventories and an ending inventory of 2,000 sheets of paper.
What are the paper's and the pencils' approximate weighted cost proportions using the sales value at splitoff method,respectively? (Multiple Choice)
4.9/5 (97)
(97) Explain the difference between a joint product and a byproduct.Can a byproduct ever become a joint product?
(Essay)
4.9/5 (95)
(95) When a product is the result of a joint process,the decision to process the product past the splitoff point further should be influenced by the
(Multiple Choice)
4.9/5 (66)
(66) Blue Paper Company processes wood pulp into two products.During January the joint costs of processing were $144,000.Production and sales value information for the month were as follows:
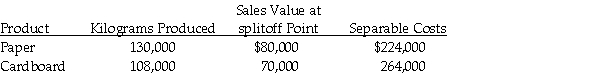 Paper sells for $2.75 a kilogram and cardboard sells for $3.50 a kilogram.
There were no beginning inventories for January but ending inventories totalled 10,000 kilograms for paper and 12,000 kilograms for cardboard.
Required:
Prepare a product line income statement in gross margin format.Joint costs are allocated using the net realizable value method assuming all available product is sold.
Paper sells for $2.75 a kilogram and cardboard sells for $3.50 a kilogram.
There were no beginning inventories for January but ending inventories totalled 10,000 kilograms for paper and 12,000 kilograms for cardboard.
Required:
Prepare a product line income statement in gross margin format.Joint costs are allocated using the net realizable value method assuming all available product is sold. (Essay)
4.9/5 (67)
(67) Product X is sold for $8 a unit and Product Y is sold for $12 a unit.Each product can also be sold at the splitoff point.Product X can be sold for $5 and Product Y for $4.Joint costs for the two products totaled $4,000 for January for 600 units of X and 500 units of Y.What are the respective joint costs assigned to each unit of products X and Y if the sales value at splitoff method is used?
(Multiple Choice)
4.9/5 (76)
(76) Ontario Lumber Company prepares lumber for companies who manufacture furniture.The main product is finished lumber with a byproduct of wood shavings.The byproduct is sold to plywood manufacturers.For July the manufacturing process incurred $166,000 in total costs.Eighty thousand board metres of lumber were produced and sold along with 6,800 kilograms of shavings.The finished lumber sold for $3.00 per board metre and the shavings sold for $0.30 a kilogram.There were no beginning or ending inventories.
Required:
Prepare an income statement showing the byproduct (1)as a cost reduction during production and (2)as a revenue item when sold.
(Essay)
4.7/5 (80)
(80) Use the information below to answer the following question(s).
Beverage Drink Company processes direct materials up to the splitoff point,where two products,A and B,are obtained.The following information was collected for the month of July:
Direct materials processed: 2,500 litres (with 20 percent shrinkage)
 Cost of purchasing 2,500 litres of direct materials and processing it up to the splitoff point to yield a total of 2,000 litres of good products was $4,500.There were no inventory balances of A and B.
Product A may be processed further to yield 1,375 litres of Product Z5 for an additional processing cost of $150.Product Z5 is sold for $25.00 per litre.There was no beginning inventory and ending inventory was 125 litres.
Product B may be processed further to yield 375 litres of Product W3 for an additional processing cost of $275.Product W3 is sold for $30.00 per litre.There was no beginning inventory and ending inventory was 25 litres.
-What is Product Z5's and Product W3's respective production cost per unit,assuming the company allocates joint costs on the basis of net realizable value?
Cost of purchasing 2,500 litres of direct materials and processing it up to the splitoff point to yield a total of 2,000 litres of good products was $4,500.There were no inventory balances of A and B.
Product A may be processed further to yield 1,375 litres of Product Z5 for an additional processing cost of $150.Product Z5 is sold for $25.00 per litre.There was no beginning inventory and ending inventory was 125 litres.
Product B may be processed further to yield 375 litres of Product W3 for an additional processing cost of $275.Product W3 is sold for $30.00 per litre.There was no beginning inventory and ending inventory was 25 litres.
-What is Product Z5's and Product W3's respective production cost per unit,assuming the company allocates joint costs on the basis of net realizable value? (Multiple Choice)
4.8/5 (85)
(85) Use the information below to answer the following question(s).
Cranbrook Chemical Ltd.manufactures two industrial compounds.In the month of May,15,000 litres of direct material costing $160,000 were processed at a cost of $400,000.The joint process yielded 16,000 containers of a compound known as Jarlon and 4,000 containers of a compound known as Kharton.The respective selling prices of Jarlon and Kharton are $38 and $58.Both products may be processed further.Jarlon may be processed into Jaxton at an incremental cost of $8 per jar of the final product while Kharton may be processed into Kraxton at an additional cost of $32 per jar of the final product.The volume of jars of the final product are: 12,000 and 3,000 for Jaxton and Kraxton respectively.The selling price of Jaxton is $48 per jar.The selling price of Kraxton is $102 per jar.
-Using the physical measures method,the weightings for joint cost allocations for Jarlon and Kharton respectively are
(Multiple Choice)
4.8/5 (82)
(82) One problem with the physical measure method of allocation is that the physical weights used for allocating joint costs may have no relation to the product's ability to produce revenue.
(True/False)
4.8/5 (82)
(82) What is the net effect to the income statement for the recognition of the byproduct,if byproducts are recognized when production is completed,and the company uses FIFO?
(Multiple Choice)
4.9/5 (91)
(91) Assigning joint costs when only a portion of a business's products are sold to a single customer is an example of which of the following?
(Multiple Choice)
4.9/5 (83)
(83) Distinguish between the two principal methods of accounting for byproducts,the production byproduct method and the sale byproduct method.Briefly discuss the relative merits (or lack thereof)of each.
(Essay)
4.8/5 (83)
(83) The estimated net realizable method allocates joint costs on the basis of
(Multiple Choice)
4.9/5 (85)
(85) Use the information below to answer the following question(s).
Cranbrook Chemical Ltd.manufactures two industrial compounds.In the month of May,15,000 litres of direct material costing $160,000 were processed at a cost of $400,000.The joint process yielded 16,000 containers of a compound known as Jarlon and 4,000 containers of a compound known as Kharton.The respective selling prices of Jarlon and Kharton are $38 and $58.Both products may be processed further.Jarlon may be processed into Jaxton at an incremental cost of $8 per jar of the final product while Kharton may be processed into Kraxton at an additional cost of $32 per jar of the final product.The volume of jars of the final product are: 12,000 and 3,000 for Jaxton and Kraxton respectively.The selling price of Jaxton is $48 per jar.The selling price of Kraxton is $102 per jar.
-Assuming Cranbrook uses the physical measures method and 2,000 containers of Jarlon and 75 containers of Kharton are unsold at the end of the period,Cranbrook would report cost of goods sold of
(Multiple Choice)
4.8/5 (70)
(70) Use the information below to answer the following question(s):
Orange Paper Company processes wood pulp into two products.During February the joint costs of processing were $156,000.Production and sales value information for the month were as follows:
 Paper sells for $2.85 a kilogram and cardboard sells for $3.90 a kilogram.
There were no beginning inventories for April but ending inventories totalled 15,000 kilograms for paper and 18,000 kilograms for cardboard.
-What will be the total incremental benefit or (loss)from all potential sales of processing the cardboard beyond the splitoff point?
Paper sells for $2.85 a kilogram and cardboard sells for $3.90 a kilogram.
There were no beginning inventories for April but ending inventories totalled 15,000 kilograms for paper and 18,000 kilograms for cardboard.
-What will be the total incremental benefit or (loss)from all potential sales of processing the cardboard beyond the splitoff point? (Multiple Choice)
4.9/5 (87)
(87) The net realizable value method is generally used for products or services that are processed and after splitoff additional value is added to the product and a selling price can be determined.
(True/False)
4.7/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)