



 Chat with AI
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Gains and losses on nontaxable exchanges are deferred because the tax law recognizes that nontaxable exchanges result in a change in the substance but not the form of the taxpayer's relative economic position.
(True/False)
4.8/5  (85)
(85) The holding period for property acquired by gift is automatically long term.
(True/False)
4.8/5 (72)
(72) Eva exchanges a pick-up truck that she has held for personal use plus $19,000 for a new pick-up truck which she will use exclusively in her sole proprietorship business.This exchange qualifies for nontaxable exchange treatment.
(True/False)
4.8/5 (70)
(70) In 2008, Harold purchased a classic car that he planned to restore for $12,000.However, Harold is too busy to work on the car and he gives it to his daughter Julia in 2012.At this time, the fair market value of the car has declined to $10,000.Harold paid no gift tax on the transaction.Julia completes some of the restoration herself with out-of-pocket costs of $5,000.She later sells the car for $30,000.What is Julia's recognized gain or loss on the sale of the car?
(Multiple Choice)
4.7/5 (81)
(81) Under the taxpayer-use test for a § 1033 involuntary conversion, the taxpayer has less flexibility in qualifying replacement property than under the functional-use test.
(True/False)
4.8/5 (69)
(69) Kevin purchased 5,000 shares of Purple Corporation stock at $10 per share.Two years later, he receives a 5% common stock dividend.At that time, the common stock of Purple Corporation had a fair market value of $12.50 per share.What is the basis of the Purple Corporation stock, the per share basis, and gain recognized upon receipt of the common stock dividend?
(Multiple Choice)
4.9/5 (83)
(83) Realized gain or loss is measured by the difference between the amount realized from the sale or other disposition of property and the property's adjusted basis at the date of disposition.
(True/False)
4.8/5 (77)
(77) Cassie purchases a sole proprietorship for $145,000.The fair market value of the tangible assets is $110,000 and the agreed to value of goodwill is $10,000.Assuming there are no other intangible assets, Cassie's basis for the tangible assets is $132,917 ($110,000 + $22,917) and her basis for the goodwill is $12,083 ($10,000 + $2,083).
(True/False)
4.9/5 (89)
(89) Henrietta and Hollis have been married for 10 years when Hollis dies in a sky-diving accident.Their assets are summarized below. 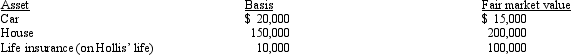 Henrietta and Hollis reside in Wisconsin, a community property state.All of the assets were acquired with community funds and pass to Henrietta.Her basis for each of the assets becomes:
Car House Cash from life insurance proceeds
Henrietta and Hollis reside in Wisconsin, a community property state.All of the assets were acquired with community funds and pass to Henrietta.Her basis for each of the assets becomes:
Car House Cash from life insurance proceeds (Multiple Choice)
4.7/5 (69)
(69) A condemned office building owned and used in the business by a taxpayer can be replaced by land and qualify for nonrecognition treatment.
(True/False)
4.9/5 (95)
(95) Sandra's automobile, which is used exclusively in her trade or business, was damaged in an accident.The adjusted basis prior to the accident was $11,000.The fair market value before the accident was $10,000 and the fair market value after the accident is $6,000.Insurance proceeds of $3,200 are received.What is Sandra's adjusted basis for the automobile after the casualty?
(Multiple Choice)
4.9/5 (80)
(80) Sam's office building with an adjusted basis of $750,000 and a fair market value of $900,000 is condemned on November 30, 2012.Sam is a calendar year taxpayer.He receives a condemnation award of $875,000 on March 1, 2013.He builds a new office building at a cost of $845,000 which is completed and paid for on December 31, 2015.What is Sam's recognized gain on receipt of the condemnation award and basis for the new office building assuming his objective is to minimize gain recognition?
(Multiple Choice)
4.9/5 (74)
(74) The taxpayer can elect to have the exclusion of gain under § 121 (sale of principal residence) not apply.
(True/False)
4.9/5 (77)
(77) Which of the following statements is incorrect for a § 1033 involuntary conversion?
(Multiple Choice)
4.9/5 (75)
(75) A taxpayer who sells his or her principal residence at a realized loss can elect to recognize the loss even if a qualified residence is acquired during the statutory time period.
(True/False)
4.8/5 (86)
(86) A realized gain whose recognition is postponed results in the temporary recovery of more than the taxpayer's cost or other basis.
(True/False)
4.9/5 (73)
(73) Vanessa's personal residence was condemned, and she received a condemnation award of $475,000.Vanessa had owned and occupied the residence for 15 years.The adjusted basis in the residence at the time of condemnation was $200,000.Vanessa used part of the condemnation proceeds to purchase a new residence for $210,000.What is Vanessa's recognized gain or loss and her basis in the new residence?
(Multiple Choice)
4.8/5 (69)
(69) Shari exchanges an office building in New Orleans (adjusted basis of $700,000) for an apartment building in Baton Rouge (fair market value of $900,000).In addition, she receives $100,000 of cash.Shari's recognized gain is $100,000 and her basis for the apartment building is $800,000 ($700,000 adjusted basis + $100,000 recognized gain).
(True/False)
4.9/5 (83)
(83) Khalid sells two personal use assets during the taxable year. A gain of $6,000 is realized on the sale of one asset and a loss of $2,000 is realized on the sale of the other asset. What is the recognized gain or loss?
(Multiple Choice)
4.9/5 (73)
(73) The basis of personal use property converted to business use is:
(Multiple Choice)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)