



 Chat with AI
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Sandy has the following results of netting her short-term and long-term capital gains and losses for 2012: $48,000 short-term capital loss, $22,000 net long-term capital gain ($21,000 0%/15% long-term capital gain, and $1,000 28% long-term capital gain).What is her net capital gain or loss for 2012 and, if there is a net capital loss, how much of the loss and what type of loss carries over to 2013?
(Essay)
4.9/5  (77)
(77) Which of the following events could result in § 1250 depreciation recapture?
(Multiple Choice)
4.8/5 (85)
(85) When an individual taxpayer has a net long-term capital gain that includes both 25% gain and 0%/15% gain, which of these gains will be taxed first when the alternative tax on net long-term capital gain method is used and what difference does it make?
(Essay)
4.7/5 (70)
(70) Vertigo, Inc., has a 2012 net § 1231 loss of $64,000 and had a $32,000 net § 1231 gain in 2011.For 2012, Vertigo's net § 1231 loss is treated as:
(Multiple Choice)
4.8/5 (93)
(93) A lease cancellation payment received by a lessee is generally treated as an exchange because the lease extinguished is usually a capital asset.
(True/False)
4.9/5 (74)
(74) As a general rule, the sale or exchange of an option to buy or sell property results in capital gain or loss if the property subject to the option is (or would be) a capital asset in the hands of the option holder.
(True/False)
4.8/5 (79)
(79) White Company acquires a new machine for $35,000 and uses it in White's manufacturing operations.A few months after White places the machine in service, it discovers that the machine is not suitable for White's business.White had fully expensed the machine in the year of acquisition using § 179. White sells the machine for $5,000 in the tax year after it was acquired, but held the machine only for a total of 10 months. What was the tax status of the machine when it was disposed of and the amount of the gain or loss?
(Multiple Choice)
4.9/5 (91)
(91) The § 1245 depreciation recapture potential does not reduce the amount of the charitable contribution deduction under § 170.
(True/False)
4.9/5 (90)
(90) Betty, a single taxpayer with no dependents, has the gains and losses shown below. Before considering these transactions, Betty has $45,000 of other taxable income. What is the treatment of the gains and losses and what is Betty's taxable income?
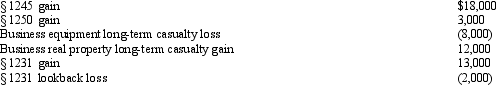
(Essay)
4.7/5 (83)
(83) Section 1231 applies to the sale or exchange of business properties, but not to personal use activity casualties.
(True/False)
4.8/5 (64)
(64) Tan, Inc., has a 2012 $50,000 long-term capital gain included in its $185,000 taxable income.Which of the following is correct?
(Multiple Choice)
4.9/5 (79)
(79) The chart below describes the § 1231 assets sold by the Ecru Company (a sole proprietorship) this year.Compute the gain or loss from each asset disposition and determine the net § 1231 gain treated as long-term capital gain for the year.Assume there is a § 1231 lookback loss of $4,000.

(Essay)
4.9/5 (92)
(92) On January 10, 2012, Wally sold an option for $2,000 on vacant land he held as an investment.He had purchased the land in 2008 for $76,000.The option allowed the option holder to purchase the property for $122,000 plus the cost of the option.On March 1, 2012, the option holder exercised the option.What is the amount and nature of Wally's gain or loss from disposition of the land?
(Essay)
4.8/5 (66)
(66) The tax law requires that capital gains and losses be separated from other types of gains and losses.Among the reasons for this treatment are:
(Multiple Choice)
4.7/5 (76)
(76) Verway, Inc., has a 2012 net § 1231 gain of $55,000 and had a $62,000 net § 1231 loss in 2011.For 2012, Verway's net § 1231 gain is treated as:
(Multiple Choice)
5.0/5 (80)
(80) Why is it generally better to have a net § 1231 gain year followed by a net § 1231 loss year rather than a net § 1231 loss year followed by a net § 1231 gain year?
(Essay)
4.7/5 (79)
(79) A franchisor licenses its mode of business operation to a franchisee.
(True/False)
4.8/5 (78)
(78) Section 1231 property generally does not include accounts receivables arising in the ordinary course of business.
(True/False)
4.7/5 (101)
(101) Phil's father died on January 10, 2012.The father had owned stock for 20 years with a basis of $45,000 that was transferred to Phil as a gift on August 10, 2011, when the stock was worth $430,000.His father paid gift tax of $31,000.This stock was worth $566,000 at the date of the father's death.Phil sold the stock for $545,000 net of commissions on February 23, 2012.What is the amount and nature of Phil's gain or loss from disposition of this property?
(Essay)
4.7/5 (81)
(81) A barn held more than one year and used in a business is destroyed in a tornado. The barn originally cost $356,000 and was fully depreciated using straight-line depreciation. The barn was insured for its $543,000 replacement cost minus a deductible of $1,000. Which of the statements below is correct concerning these facts?
(Multiple Choice)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)