



 Chat with AI
Exam 16: Accounting Periods and Methods

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


In the case of a small home construction company that builds under long-term contracts, generally:
(Multiple Choice)
4.9/5  (80)
(80) A calendar year, cash basis corporation began business on April 1, 2012, and paid $2,400 for a 24-month liability insurance policy. An accrual basis, calendar year taxpayer also began business on April 1, 2012, and purchased a 24-month liability insurance policy. Both the cash basis and accrual basis taxpayers' deduction for insurance expense on the policy for 2012 is $900 (9/12 ´ $1,200).
(True/False)
4.9/5 (88)
(88) Gold Corporation, Silver Corporation, and Copper Corporation are equal partners in the GSC Partnership.The partners' tax year-ends are as follows: 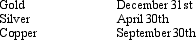
(Multiple Choice)
4.9/5 (80)
(80) Generally, deductions for additions to reserves for estimated future costs (e.g., an allowance for estimated warranty costs) are not allowed for Federal income tax purposes because allowing the deduction would:
(Multiple Choice)
4.9/5 (91)
(91) Sandstone, Inc., has consistently included some factory overhead as a current expense, rather than as a cost of producing goods.As a result, the beginning inventory for 2012 is understated by $40,000.If Sandstone voluntarily changes accounting methods effective January 1, 2012, the positive adjustment to the inventory is a § 481 adjustment and $10,000 must be added to taxable income for each year 2012, 2013, 2014, and 2015.
(True/False)
4.9/5 (86)
(86) A C corporation's selection of a tax year, generally, is independent of the tax year of its principal shareholders.
(True/False)
4.8/5 (80)
(80) In 2012, T Corporation changed its tax year from ending each September 30th to ending each December 31st. The corporation earned $25,000 during the period October 1, 2012 through December 31, 2012. The tax on the annualized income for the short period will be greater than the tax on $25,000 when the tax rates are progressive.
(True/False)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)