



 Chat with AI
Exam 17: Corporations: Introduction and Operating Rules

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Jessica, a cash basis individual, is a 60% shareholder of Crow Corporation, a regular corporation. On January 1, 2012, Jessica loaned Crow $300,000, with the principal due in 5 years and 6% interest due each January 1. Crow, an accrual method, calendar year taxpayer, accrued $18,000 of interest expense on the loan on December 31, 2012, and paid the $18,000 to Jessica on January 1, 2013. How much is Crow's deduction for interest on this loan for 2012? Would your answer change if Jessica was a 25% shareholder of Crow?
(Essay)
4.9/5  (86)
(86) Nancy is a 40% shareholder and president of Robin Corporation, a regular corporation. The board of directors of Robin has decided to pay Nancy a $175,000 bonus for the year based on her outstanding performance. The directors want to pay the $175,000 as salary, but Nancy would prefer to have it paid as a dividend. If both Robin Corporation and Nancy are in a 35% marginal tax bracket irrespective of the treatment of the bonus, discuss which form of payment would be most beneficial for each party. (Ignore any employment tax considerations.)
(Essay)
4.8/5 (92)
(92) A personal service corporation with taxable income of $100,000 will have a tax liability of $22,250.
(True/False)
4.7/5 (73)
(73) Rose is a 50% partner in Wren Partnership.During the year, Wren earned net profit of $100,000 ($210,000 gross income - $110,000 operating expenses) and distributed $20,000 to each partner.Rose must report Wren Partnership profit of $20,000 on her Federal income tax return.
(True/False)
4.7/5 (70)
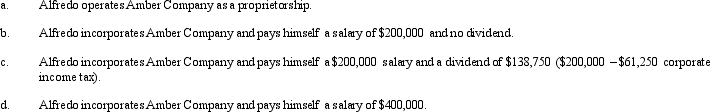
(70) Amber Company has $400,000 in net income in 2012 before deducting any compensation or other payment to its sole owner, Alfredo. Assume that Alfredo is in the 35% marginal tax bracket. Discuss the tax aspects of each of the following independent arrangements. (Assume that any salaries are reasonable in amount and ignore any employment tax considerations.)
(Essay)
5.0/5 (78)
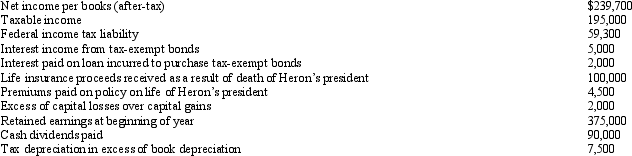
(78) Heron Corporation, a calendar year, accrual basis taxpayer, provides the following information for this year and asks you to prepare Schedule M-1:
(Essay)
4.8/5 (76)
(76) A taxpayer is considering the formation of a business that would derive some amounts of tax-exempt interest, qualified dividends, and capital gains. Explain how these income categories would be reported and taxed under the various types of entity forms discussed in the chapter. Consider the tax implications both to the entities and to their owners.
(Essay)
4.9/5 (65)
(65) Eagle Company, a partnership, had a short-term capital loss of $10,000 during the year. Aaron, who owns 25% of Eagle, will report $2,500 of Eagle's short-term capital loss on his individual tax return.
(True/False)
4.8/5 (86)
(86) On December 31, 2012, Flamingo, Inc., a calendar year, accrual method C corporation, accrues a bonus of $50,000 to its president (a cash basis taxpayer), who owns 75% of the corporation's outstanding stock. The $50,000 bonus is paid to the president on February 1, 2013. For Flamingo's 2012 Form 1120, the $50,000 bonus will be a subtraction item on Schedule M-1.
(True/False)
4.8/5 (89)
(89) Quail Corporation is a C corporation with net income of $125,000 during the current year.If Quail paid dividends of $25,000 to its shareholders, the corporation must pay tax on $100,000 of net income.Shareholders must report the $25,000 of dividends as income.
(True/False)
4.9/5 (92)
(92) A calendar year C corporation with average annual gross receipts of $5 million or less must use the cash method of accounting.
(True/False)
4.7/5 (70)
(70) Under the "check-the-box" Regulations, a two-owner LLC that fails to elect to be to treated as a corporation will be taxed as a sole proprietorship.
(True/False)
4.8/5 (79)
(79) On December 28, 2012, the board of directors of Taupe Corporation, a calendar year, accrual method C corporation, authorized a contribution of land to a qualified charitable organization. The land (basis of $75,000, fair market value of $125,000) was acquired five years ago and held as an investment. For purposes of the taxable income limitation applicable to charitable deductions, Taupe has taxable income of $800,000 and $950,000 for 2012 and 2013, respectively. Describe the tax consequences to Taupe Corporation under the following independent situations.
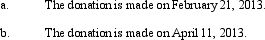
(Essay)
4.9/5 (66)
(66) Almond Corporation, a calendar year C corporation, had taxable income of $900,000, $1.1 million, and $1.2 million for 2009, 2010, and 2011, respectively. Almond's taxable income is $2 million for 2012. Compute the minimum estimated tax payments for 2012 for Almond Corporation.
(Essay)
4.8/5 (79)
(79) Schedule M-1 of Form 1120 is used to reconcile financial net income with taxable income reported on the corporation's income tax return as follows: net income per books + additions - subtractions = taxable income.Which of the following items is a subtraction on Schedule M-1?
(Multiple Choice)
4.9/5 (71)
(71) If a C corporation uses straight-line depreciation on real estate (§ 1250 property), no gain on the sale of the property will be recaptured as ordinary income.
(True/False)
4.8/5 (71)
(71) Which of the following statements is incorrect regarding the dividends received deduction?
(Multiple Choice)
4.9/5 (88)
(88) What is the purpose of Schedule M-3? Which corporations are required to file Schedule M-3?
(Essay)
4.9/5 (79)
(79) Generally, corporate net operating loss can be carried back 3 years and forward 5 years to offset taxable income for those years.
(True/False)
4.7/5 (67)
(67) Red Corporation, a C corporation that has two equal shareholders, earned $450,000 during 2012. Orange Company, a partnership that has two equal partners, earned $450,000 during the year. Red did not make any distributions to its shareholders, and Orange's partners did not make any withdrawals. Contrast the tax treatment of the shareholders of Red Corporation and the partners of Orange Company.
(Essay)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)