



 Chat with AI
Exam 19: Corporations: Distributions Not in Complete Liquidation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


As a result of a redemption, a shareholder's interest (direct and indirect) in the corporation decreased from 58% to 45%. The redemption qualifies for sale or exchange treatment as a disproportionate redemption.
(True/False)
4.8/5  (73)
(73) Ten years ago, Carrie purchased 2,000 shares in Osprey Corporation for $20,000.In the current year, Carrie receives a nontaxable stock dividend of 20 shares of Osprey preferred.Values at the time of the dividend are: $8,000 for the preferred stock and $72,000 for the common.Based on this information, Carrie's basis in the stock is:
(Multiple Choice)
4.7/5 (91)
(91) Ashley, the sole shareholder of Hawk Corporation, has a stock basis of $200,000 at the beginning of the year.On July 1, she sells all of her stock to Matt for $1 million.On January 1, Hawk has accumulated E & P of $90,000 and during the year, current E & P of $160,000.Hawk makes the following cash distributions: $270,000 to Ashley on March 31 and $90,000 to Matt on December 1.How are the distributions taxed to Ashley and Matt? What is Ashley's recognized gain on the sale to Matt?
(Essay)
4.8/5 (74)
(74) Five years ago, Eleanor transferred property she had used in her sole proprietorship to Blue Corporation for 1,000 shares of Blue Corporation in a transaction that qualified under § 351. The assets had a tax basis to her of $100,000 and a fair market value of $270,000 on the date of the transfer.In the current year, Blue Corporation ( E & P $800,000) redeems 250 shares from Eleanor for $220,000 in a transaction that qualifies for sale or exchange treatment.With respect to the redemption, Eleanor will have a:
(Multiple Choice)
4.7/5 (75)
(75) Tanya is in the 35% tax bracket. She acquired 1,000 shares of stock in Swan Corporation seven years ago for $250 a share. In the current year, Swan Corporation (E & P of $1.2 million) redeems all of her shares for $400,000. What are the tax consequences to Tanya if:
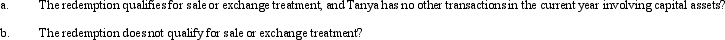
(Essay)
4.9/5 (83)
(83) On January 1, Gold Corporation (a calendar year taxpayer) has E & P of $30,000 and generates no additional E & P during the year.On March 31, the corporation distributes $40,000 to its sole shareholder, Wyatt (basis in stock of $8,000).Determine the effect of the distribution on Wyatt's taxable income and stock basis.
(Essay)
4.8/5 (86)
(86) Robin Corporation distributes furniture (basis of $40,000; fair market value of $50,000) as a property dividend to its shareholders.The furniture is subject to a liability of $55,000.Robin Corporation recognizes gain of:
(Multiple Choice)
4.8/5 (70)
(70) A loss in current E & P is treated as occurring ratably during the year, unless the taxpayer can show otherwise.
(True/False)
4.9/5 (70)
(70) Finch Corporation distributes property (basis of $225,000, fair market value of $300,000) to a shareholder in a distribution that is a qualifying stock redemption.The property is subject to a liability of $160,000, which the shareholder assumes.The basis of the property to the shareholder is:
(Multiple Choice)
4.8/5 (90)
(90) A corporation that distributes a property dividend must reduce its E & P by the adjusted basis of the property less any liability on the property.
(True/False)
4.8/5 (77)
(77) A corporate shareholder that receives a constructive dividend cannot apply a dividends received deduction to the distribution.
(True/False)
4.7/5 (69)
(69) On January 2, 2012, Orange Corporation purchased equipment for $300,000 with an ADS recovery period of 10 years and a MACRS useful life of 7 years.Section 179 was not elected.MACRS depreciation properly claimed on the asset, including depreciation in the year of sale, totaled $79,605.The equipment was sold on July 1, 2013, for $290,000.As a result of the sale, the adjustment to taxable income needed to arrive at current E & P is:
(Multiple Choice)
4.8/5 (65)
(65) Swan Corporation makes a property distribution to its sole shareholder, Matthew. The property distributed is a cottage (fair market value of $135,000; basis of $110,000) that is subject to a $175,000 mortgage that Matthew assumes.Before considering the consequences of the distribution, Swan's current E & P is $25,000 and its accumulated E & P is 100,000. Swan makes no other distributions during the current year. What is Swan's taxable gain on the distribution of the cottage?
(Multiple Choice)
4.9/5 (95)
(95) On January 1, Tulip Corporation (a calendar year taxpayer) has accumulated E & P of $300,000.Its current E & P for the year is $90,000 (before considering dividend distributions).During the year, Tulip distributes $600,000 ($300,000 each) to its equal shareholders, Anne and Tom.Anne has a basis in her stock of $65,000, while Tom's basis is $120,000.What is the effect of the distribution by Tulip Corporation on Anne and Tom?
(Essay)
4.8/5 (89)
(89) Ivory Corporation (E & P of $650,000) has 1,000 shares of common stock outstanding owned by unrelated parties as follows: Veronica, 500 shares, and Tommie, 500 shares. Veronica and Tommie each paid $125 per share for the Ivory stock 12 years ago.In May of the current year, Ivory distributes securities held as an investment (basis of $140,000, fair market value of $250,000) to Veronica in redemption of 200 of her shares.
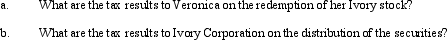
(Essay)
4.9/5 (83)
(83) Glenda is the sole shareholder of Condor Corporation.She sold her stock to Melissa on October 31 for $150,000.Glenda's basis in Condor stock was $50,000 at the start of the year.Condor distributed land to Glenda immediately before the sale.Condor's basis in the land was $20,000 (fair market value of $25,000).On December 31, Melissa received a $75,000 cash distribution from Condor.During the year, Condor has $20,000 of current E & P and its accumulated E & P balance on January 1 is $10,000.Which of the following statements is true?
(Multiple Choice)
4.8/5 (74)
(74) Betty's adjusted gross estate is $9 million.The death taxes and funeral and administration expenses of her estate total $1.2 million.Included in Betty's gross estate is stock in Heron Corporation, valued at $3.3 million as of the date of her death in 2012.Betty had acquired the stock six years ago at a cost of $810,000.If Heron Corporation redeems $1.2 million of Heron stock from the estate, the transaction will qualify under § 303 as a redemption to pay death taxes and receive sale or exchange treatment.
(True/False)
5.0/5 (80)
(80) Falcon Corporation ended its first year of operations with taxable income of $250,000.At the time of Falcon's formation, it incurred $50,000 of organizational expenses.In calculating its taxable income for the year, Falcon claimed an $8,000 deduction for the organizational expenses.What is Falcon's current E & P?
(Multiple Choice)
4.8/5 (69)
(69) Regardless of any deficit in current E & P, distributions during the year are taxed as dividends to the extent of accumulated E & P.
(True/False)
4.8/5 (74)
(74) If a distribution of stock rights is taxable and their fair market value is less than 15 percent of the value of the old stock, then either a zero basis or a portion of the old stock basis may be assigned to the rights, at the shareholder's option.
(True/False)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)