



 Chat with AI
Exam 25: Taxation of International Transactions

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


The purpose of the transfer pricing rules is to ensure that taxpayers have ultimate flexibility in shifting profits between related entities.
(True/False)
4.8/5  (78)
(78) In allocating interest expense between U.S.and foreign sources, a taxpayer must use the tax basis of the income-producing assets.
(True/False)
4.9/5 (90)
(90) A U.S.corporation may be able to alleviate the problem of excess foreign taxes by:
(Multiple Choice)
4.7/5 (82)
(82) Which of the following statements regarding the taxation of U.S.real property gains recognized by foreign persons not engaged in a U.S.trade or business is false? Gains from the disposition of U.S.real property are:
(Multiple Choice)
4.8/5 (80)
(80) WaterCo, a domestic corporation, purchases inventory for resale from unrelated distributors outside the United States and resells this inventory to customers inside the United States with title passing inside the United States.What is the source of WaterCo's inventory sales income?
(Multiple Choice)
4.8/5 (75)
(75) Kipp, a U.S.shareholder under the CFC provisions, owns 40% of a CFC.If the CFC's Subpart F income for the taxable year is $200,000, Kipp is not taxed on receipt of a constructive dividend of $80,000 because he doesn't own more than 50% of the CFC.
(True/False)
4.8/5 (78)
(78) Freda was born and continues to live in Uruguay. She exports widgets to U.S.customers. The U.S.does not have in force an income tax treaty with Urugauy. Freda's net U.S.income from the widgets is subject to a flat 30% Federal income tax rate.
(True/False)
4.8/5 (85)
(85) GlobalCo, a foreign corporation not engaged in a U.S.trade or business, receives $80,000 in interest income from deposits with the foreign branch of a U.S.bank.The U.S.bank earns 24% of its income from foreign sources.How much of GlobalCo's interest income is U.S.source?
(Multiple Choice)
5.0/5 (81)
(81) Unused foreign tax credits are carried back one year and then forward 10 years.
(True/False)
4.8/5 (79)
(79) Xenia, Inc., a U.S.shareholder, owns 100% of Fredonia, a CFC.Xenia receives a $3 million cash distribution from Fredonia.Fredonia's E & P is composed of the following amounts. 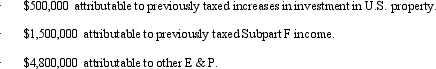 Xenia recognizes a taxable dividend of:
 (Multiple Choice)
4.9/5 (84)
(84) Julio, a nonresident alien, realizes a gain on the sale of commercial real estate located in Omaha.The real estate was sold to Mariana, Julio's cousin who is also a nonresident alien.Julio recognizes foreign-source income from the sale because his home country is not the U.S.
(True/False)
4.8/5 (79)
(79) A domestic corporation is one whose assets are primarily (> 50%) located in the U.S.
(True/False)
4.8/5 (87)
(87) Hendricks Corporation, a domestic corporation, owns 40 percent of Shane Corporation and 55 percent of Ferrell Corporation, both foreign corporations.Ferrell owns the other 60 percent of Shane Corporation.Both Shane and Ferrell are CFCs.
(True/False)
4.7/5 (79)
(79) Peanut, Inc., a domestic corporation, receives $500,000 of foreign-source interest income, on which foreign taxes of $5,000 are withheld.Peanut's worldwide taxable income is $900,000, and its U.S.Federal income tax liability before FTC is $270,000.What is Peanut's foreign tax credit?
(Multiple Choice)
4.7/5 (84)
(84) Which of the following foreign taxes paid by a U.S.corporation may be eligible for the foreign tax credit?
(Multiple Choice)
4.8/5 (72)
(72) The "residence of seller" rule is used in determining the sourcing of all gross income and deductions of a U.S.multinational business.
(True/False)
4.8/5 (91)
(91) Waltz, Inc., a U.S.taxpayer, pays foreign taxes of $50,000 on foreign-source general basket income of $90,000. Waltz's worldwide taxable income is $450,000, on which it owes U.S.taxes of $157,500 before FTC. Waltz's FTC is $50,000.
(True/False)
4.8/5 (74)
(74) Which of the following transactions, if entered into by an NRA, is not subject to U.S.taxation?
(Multiple Choice)
5.0/5 (71)
(71) Which of the following statements regarding foreign persons not engaged in a U.S.trade or business is true?
(Multiple Choice)
4.7/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)