



 Chat with AI
Exam 28: Income Taxation of Trusts and Estates

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


A fiduciary assigns its tax credits to beneficiaries corresponding to the disposition of its ____________________ for the year.
(Short Answer)
4.7/5  (80)
(80) The IRS encourages ____________________ filing for Forms 1041.
(Short Answer)
4.9/5 (85)
(85) A fiduciary entity computes its alternative minimum tax in a manner similar to that used for a(n) ____________________.
(Short Answer)
4.7/5 (92)
(92) The Gable Trust reports $20,000 business income and $10,000 exempt interest income, and it paid a $3,000 fiduciary fee.Gable's distributable net income includes $10,000 of net tax-exempt income.
(True/False)
4.9/5 (79)
(79) Beneficiary information concerning a trust's income and distributions are conveyed on Schedule ____________________ of the Form 1041.
(Short Answer)
4.9/5 (71)
(71) The Willa estate reports $100,000 DNI, composed of $50,000 dividends, $20,000 taxable interest, $10,000 passive income, and $20,000 tax-exempt interest.Willa's two noncharitable income beneficiaries, Shanna and Tom, receive distributions of $75,000 each.How much of each class of income is deemed to have been distributed to Shanna? To Tom? Use the following template to structure your answer.
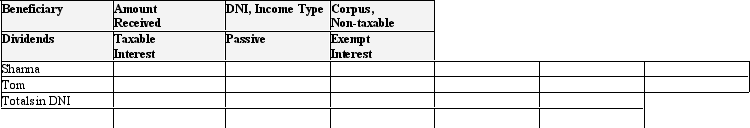
(Essay)
4.8/5 (87)
(87) Remainder beneficiary Shelley receives a $50,000 net operating loss carryover when the Malone Trust terminates. Shelley deducts this amount ____________________ (for/from) AGI on her Form 1040.
(Short Answer)
4.8/5 (80)
(80) Harry, the sole income beneficiary, received a $40,000 distribution from the Lucy Trust, in a year when the trust's distributable net income was $30,000.Harry's AGI can increase by as much as $40,000.
(True/False)
5.0/5 (73)
(73) The Ulrich Trust has distributable net income (DNI) for the year of $100,000 and no income from tax-exempt sources.Under the terms of the trust instrument, the trustee must distribute $60,000 to Roger and $60,000 to Sally.After paying these amounts, the trustee is empowered to make additional distributions at its discretion.Exercising this authority, the Ulrich trustee distributes an additional $15,000 to Roger and $15,000 to Sally.How much gross income from the trust must Roger recognize?
(Multiple Choice)
4.7/5 (79)
(79) A ____________________ tier distribution is one that the trust agreement requires to be made by the trustee to the income beneficiary.
or
(Short Answer)
4.9/5 (79)
(79) A complex trust pays tax on the income that it retains and adds to corpus.
(True/False)
4.9/5 (81)
(81) Judy can claim one-third of the Sweet Estate's cost recovery deductions, because she received one-third of the fiduciary's distributable net income (DNI).
(True/False)
5.0/5 (75)
(75) A fiduciary's distribution deduction shifts the tax burden for current-year income from the entity to the beneficiary.
(True/False)
4.7/5 (79)
(79) The Leonardo Estate operates a business and generates cost recovery deductions. Which taxpayer(s), if any, can deduct these items, e.g., the deceased, the estate, the income or remainder beneficiaries?
(Essay)
4.8/5 (70)
(70) In the year in which an estate terminates, its beneficiaries receive and can use as their own any unexpired NOL carryforwards proportionately to the corpus assets that they received.
(True/False)
4.8/5 (73)
(73) To reduce trustee commissions, the Sigrid Trust is operated as though it were two trusts (i.e., with 70-year-old Grandma and 7-year old Skippy each holding equal shares).This year the trust generated distributable net income (DNI) of $80,000.The Sigrid trustee distributed $100,000 to Grandma this year: $40,000 as her one-half share of the entity's income, and $60,000 as a distribution of principal.Skippy received no distribution. How much of the year's distributable net income is assigned to Grandma?
(Multiple Choice)
4.7/5 (84)
(84) The Zhao Estate generated distributable net income (DNI) this year of $100,000, one-fourth of which was tax-exempt interest, and the balance of which was long-term capital gain.Kyle Zhao, the sole income beneficiary of the estate, received a distribution of the entire $125,000 accounting income of the entity.How does Kyle report the distribution?
(Multiple Choice)
4.9/5 (69)
(69) The Doyle Trust reports distributable net income for the year of $100,000 and no income from tax-exempt sources.Under the terms of the trust instrument, the trustee must distribute $30,000 to Roger and $30,000 to Sally.After payment of these amounts, the trustee is empowered to make additional distributions at its discretion.Exercising this authority, the trustee distributes an additional $25,000 to Roger and $25,000 to Sally.How much income from the trust must Sally recognize?
(Multiple Choice)
4.7/5 (70)
(70) "First-tier distributions" allowed by the will or trust document are made at the discretion of the executor or trustee.
(True/False)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)