



 Chat with AI
Exam 4: Gross Income: Concepts and Inclusions

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: A: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


The constructive receipt doctrine requires that income must be recognized when it is made available to the cash basis taxpayer, although it has not been actually received.The constructive receipt doctrine does not apply to accrual basis taxpayers.
(True/False)
4.9/5  (95)
(95) With respect to the prepaid income from services, which of the following is true?
(Multiple Choice)
4.9/5 (75)
(75) Roy is considering purchasing land for $10,000.He expects the land to appreciate in value 8% each year (compounded) and he will sell it at the end of 10 years.He also is considering purchasing a bond for $10,000.The bond does not pay any annual interest, but will pay $21,589 at maturity in 10 years.The before-tax rate of return on the bond is 8%.Roy is in the 40% (combined Federal and State) marginal tax bracket.Roy has other investments that earn a 8% before-tax rate of return.Given that the compound interest factor at 8% is 2.1589, and at 4.8% the factor is 1.5981, which alternative should Roy choose?
(Essay)
4.9/5 (78)
(78) Terri purchased an annuity for $100,000.She was to receive $8,000 per year and her life expectancy was 20 years. She died after receiving 15 payments.Terri's final return should reflect a loss of $40,000 (5 payments not made ´ $8,000).
(True/False)
4.9/5 (84)
(84) Teal company is an accrual basis taxpayer.On December 1, 2012, a customer paid for an item that was on hand, but the customer wanted the item delivered in early January 2013. Teal delivered the item on January 4, 2013.Teal included the sale in its 2012 income for financial accounting purposes.
(Multiple Choice)
4.8/5 (78)
(78) Our tax laws encourage taxpayers to ____ assets that have appreciated in value and ____ assets that have declined in value.
(Multiple Choice)
4.9/5 (69)
(69) Which of the following is not a requirement for an alimony deduction?
(Multiple Choice)
4.8/5 (71)
(71) Sharon made a $60,000 interest-free loan to her son, Todd, who used the money to start a new business.Todd's only sources of income were $25,000 from the business and $490 of interest on his checking account.The relevant Federal interest rate was 5%.Based on the above information:
(Multiple Choice)
4.8/5 (61)
(61) Turner, a successful executive, is negotiating a compensation plan with his potential employer.The employer has offered to pay Turner a $600,000 annual salary, payable at the rate of $50,000 per month.Turner counteroffers to receive a monthly salary of $40,000 ($480,000 annually) and a $180,000 bonus in 5 years when Turner will be age 65.
(Multiple Choice)
4.8/5 (81)
(81) The Green Company, an accrual basis taxpayer, provides business-consulting services.Clients generally pay a retainer at the beginning of a 12-month period.This entitles the client to no more than 40 hours of services.Once the client has received 40 hours of services, Green charges $500 per hour.Green Company allocates the retainer to income based on the number of hours worked on the contract.At the end of the tax year, the company had $50,000 of unearned revenues from these contracts.The company also had $10,000 in unearned rent income received from excess office space leased to other companies.Based on the above, Green must include in gross income for the current year:
(Multiple Choice)
4.8/5 (88)
(88) In the case of a below-market loan between family members, if the imputed interest rules apply, which of the following is not true?
(Multiple Choice)
5.0/5 (78)
(78) A cash basis taxpayer purchased a certificate of deposit for $1,000 on July 1, 2012 that will pay $1,100 upon its maturity on June 30, 2014. The taxpayer must recognize a portion of the income in 2012.
(True/False)
4.8/5 (79)
(79) Dick and Jane are divorced in 2011.At the time of the divorce, Dick had a lawsuit pending.He had filed suit against a former employer for overtime pay.As part of a divorce agreement, Dick agreed to pay Jane one-half of the proceeds from the lawsuit.In 2012, Dick collected $250,000 from the former employer and paid Jane $125,000.What are the tax consequences for Dick receiving the $250,000 and then paying Jane the $125,000?
(Essay)
4.8/5 (86)
(86) Mark is a cash basis taxpayer. He is a partner in the M&M partnership, and his share of the partnership's profits for 2012 is $90,000.Only $40,000 was distributed to him in January 2012, and this was his share of the 2011 partnership profits. None of the 2012 profits were distributed although Mark's share of the 2012 profits was $90,000.Mark's gross income from the partnership for 2012 is $40,000.
(True/False)
4.8/5 (80)
(80) Sarah, a majority shareholder in Teal, Inc., made a $200,000 interest-free loan to the corporation.Sarah is not an employee of the corporation.
(Multiple Choice)
4.8/5 (85)
(85) Jake is the sole shareholder of an S corporation that earned $50,000 in 2012. The corporation was short on cash and therefore distributed only $15,000 to Jake in 2012. Jake is required to recognize $15,000 of income from the S corporation in 2012.
(True/False)
4.8/5 (73)
(73) Jessica is a cash basis taxpayer.When Jessica failed to repay a loan, the bank garnished her salary.Each week $60 was withheld from Jessica's salary and paid to the bank.Jessica is required to include the $60 each week in her gross income even though it is the creditor that benefits from the income.
(True/False)
4.9/5 (77)
(77) Tim and Janet were divorced.Their only marital property was a personal residence with a value of $120,000 and cost of $50,000.Under the terms of the divorce agreement, Janet would receive the house and Janet would pay Tim $15,000 each year for 5 years, or until Tim's death, whichever should occur first.Tim and Janet lived apart when the payments were made to Tim.The divorce agreement did not contain the word "alimony."
(Multiple Choice)
4.8/5 (76)
(76) Freddy purchased a certificate of deposit for $20,000 on July 1, 2012.The certificate's maturity value in two years (June 30, 2014) is $21,218, yielding 3% before-tax interest.
(Multiple Choice)
4.9/5 (83)
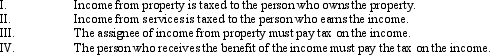
(83) 

Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)