



 Chat with AI
Exam 18: Spoilage, Rework, and Scrap

Exam 1: The Accountants Vital Role in Decision Making141 Questions
Exam 2: An Introduction to Cost Terms and Purposes165 Questions
Exam 3: Cost-Volume-Profit Analysis139 Questions
Exam 4: Job Costing138 Questions
Exam 5: Activity-Based Costing and Management133 Questions
Exam 6: Master Budget and Responsibility Accounting150 Questions
Exam 7: Flexible Budgets, Variances, and Management Control: I146 Questions
Exam 8: Flexible Budgets, Variances, and Management Control: II137 Questions
Exam 9: Income Effects of Denominator Level on Inventory Valuation154 Questions
Exam 10: Quantitative Analyses of Cost Functions114 Questions
Exam 11: Decision Making and Relevant Information146 Questions
Exam 12: Pricing Decisions, Product Profitability Decisions, and Cost Management135 Questions
Exam 13: Strategy, Balanced Scorecard, and Profitability Analysis140 Questions
Exam 14: Period Cost Allocation153 Questions
Exam 15: Cost Allocation: Joint Products and Byproducts149 Questions
Exam 16: Revenue and Customer Profitability Analysis137 Questions
Exam 17: Process Costing128 Questions
Exam 18: Spoilage, Rework, and Scrap121 Questions
Exam 19: Cost Management: Quality, Time, and the Theory of Constraints158 Questions
Exam 20: Inventory Cost Management Strategies136 Questions
Exam 21: Capital Budgeting: Methods of Investment Analysis128 Questions
Exam 22: Capital Budgeting: a Closer Look120 Questions
Exam 23: Transfer Pricing and Multinational Management Control Systems141 Questions
Exam 24: Multinational Performance Measurement and Compensation139 Questions
Select questions type


The Skate Board Company uses a process cost system for making skateboard wheels. Materials are added at the beginning of the process and conversion costs are uniformly incurred. At the beginning of September the work in process is 40 percent complete and at the end of the month it is 60 percent complete. Spoilage is detected at the end of the process. Other data for the month include:

 Beginning work in process costs:
 Required:
a. Prepare a production cost worksheet using the FIFO method of process costing. Recognize spoilage.
b. Prepare journal entries to record transferring out of cost from the work in process accounts.
Beginning work in process costs:
Required:
a. Prepare a production cost worksheet using the FIFO method of process costing. Recognize spoilage.
b. Prepare journal entries to record transferring out of cost from the work in process accounts. (Essay)
4.8/5  (66)
(66) Robotoys Incorporated manufactures and distributes small robotic toys. Reworked units are common. The average cost of the reworked orders is $11.30: $4.15 for labour, $5.00 for more materials, and $2.15 for overhead. This ratio of costs holds for the average original order. On a recent day, the shop reworked 83 orders out of 700. The original cost of the 83 orders totaled $1,909. The average cost of all orders is $24.34, including rework, with an average selling price of $34.50.
Required:
Prepare the necessary journal entry to record the rework for the day if the shop charges such activities to Robo Department Overhead Control. Prepare journal entries to record all relevant rework charges as well as to transfer the reworked items finished goods to Finished Goods Inventory.
(Essay)
4.9/5 (70)
(70) Hogan Ltd. uses a standard cost system in its manufacturing process. During a recent job, it noticed that its spoilage rate was high. Normal spoilage rate averages 8% of units started. Direct materials are added at the beginning of the process. Inspection occurs at the 50% point. Other information about the job follows:
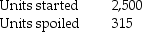
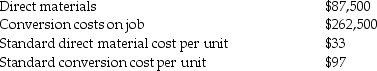 Spoiled units have no salvage value.
Required:
Make necessary journal entries to record all spoilage.
Spoiled units have no salvage value.
Required:
Make necessary journal entries to record all spoilage. (Essay)
4.9/5 (85)
(85) Under the weighted-average method, the costs of normal spoilage are added to the costs of their related good units. Hence, the cost per good unit completed and transferred out equals the total costs transferred out divided by the number of good units produced.
(True/False)
4.9/5 (70)
(70) 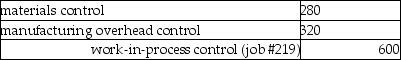
Reworked goods are unacceptable units of production usually not capable of being repaired or converted into a salable product.
(True/False)
4.8/5 (91)
(91) Dutton Industries is a manufacturer of cleaning products. Its main product goes through two departments: Mixing and Bottling. During June, the beginning WIP in the Mixing department was 32% complete as to conversion cost. The beginning inventory included $15,200 for materials and $19,800 for conversion costs. Ending WIP in the Mixing department was 80% complete. All direct materials are added at the beginning of the process in each department. Inspection occurs at the end of the process in both departments. Normal spoilage is 2.5% of good output in Mixing and 1.4% of good output in Bottling. Beginning WIP in Bottling was 60% complete with respect to conversion costs and ending WIP was 30% converted. Beginning WIP included $8,850 for direct materials, $72,200 for transferred in costs and $23,800 for conversion costs. Additional information follows:
 Required:
Prepare a production cost worksheet using weighted-average for the Mixing department and FIFO for the Bottling department.
Required:
Prepare a production cost worksheet using weighted-average for the Mixing department and FIFO for the Bottling department. (Essay)
4.9/5 (72)
(72) Answer the following question(s) using the information below.
Samantha's Office Supplies manufactures desk organizers in its Processing Department. Direct materials are added at the beginning of the process and conversion costs are incurred evenly throughout the production cycle. Inspection takes place at the end of the process and spoiled units generally constitute 4% of the good units. Data provided for February are as follows:
 -What are the direct materials and conversion costs of all the units that were started and completed during February?
 (Multiple Choice)
4.9/5 (81)
(81) New Image Sports uses a process costing system. Direct materials are placed into production at the beginning of the process. All spoilage is normal and is detected at the end of the process. For March the company had the following activities:
 Required:
Prepare a production cost worksheet using the FIFO method.
Required:
Prepare a production cost worksheet using the FIFO method. (Essay)
4.8/5 (69)
(69) The unit costs of abnormal and normal spoilage are equal, when the two are detected simultaneously.
(True/False)
5.0/5 (81)
(81) Use the information below to answer the following question(s).
Cartwright Custom Carpentry manufactures chairs in its Processing Department, and uses the FIFO cost flow assumption. Direct Materials are included at the inception of the production cycle and must be bundled in single kits for each unit. Conversion costs are incurred evenly throughout the production cycle. Inspection takes place at the end of the process and spoiled units generally constitute 3 percent of the good output Information provided for March is as follows:
 -What costs are allocated to the ending work in process inventory for direct materials and conversion costs, respectively?
 (Multiple Choice)
4.8/5 (85)
(85) If scrap, common to all jobs, is returned to the storeroom and the time between the scrap being inventoried and its disposal is quite lengthy, the journal entry is:
(Multiple Choice)
4.8/5 (70)
(70) Which of the following is NOT a consideration when accounting for scrap?
(Multiple Choice)
4.8/5 (86)
(86) If normal spoilage is presumed to occur prior to a specific inspection point, and abnormal spoilage is detected at other inspection points,
(Multiple Choice)
4.9/5 (78)
(78) Use the information below to answer the following question(s).
Craft Concept manufactures small tables in its Processing Department. Direct Materials are added at the initiation of the production cycle and must be bundled in single kits for each unit. Conversion costs are incurred evenly throughout the production cycle. Before inspection, some units are spoiled due to non-detectable materials defects. Inspection occurs at the end of the process. Spoiled units generally constitute 5 percent of the good units. Data for December are as follows:
 -What are the amounts of direct materials and conversion costs assigned to ending work in process using the weighted-average process costing method?
 (Multiple Choice)
4.8/5 (73)
(73) Answer the following question(s) using the information below.
Samantha's Office Supplies manufactures desk organizers in its Processing Department. Direct materials are added at the beginning of the process and conversion costs are incurred evenly throughout the production cycle. Inspection takes place at the end of the process and spoiled units generally constitute 4% of the good units. Data provided for February are as follows:
-Assuming Hawk uses the FIFO method of process costing, the equivalent units for direct materials and conversion costs respectively for October are:
-Assuming Hawk uses the FIFO method of process costing, the equivalent units for direct materials and conversion costs respectively for October are: (Multiple Choice)
4.8/5 (88)
(88) Playtime Ltd. manufactures toys in two departments: Forming and Finishing. During August, the beginning WIP in the Forming Department was 38% complete with respect to conversion, direct materials are added at the beginning of the process. The beginning inventory in Forming included $36,400 for materials and $9,400 for conversion costs. Ending WIP in the Forming department was 70% complete. In the second department, Finishing, direct materials are added at the end of the process. Beginning WIP in Finishing was 22% complete with respect to conversion costs and ending WIP was 85% converted. Beginning WIP included $35,200 for transferred in costs and $12,350 for conversion costs. Additional information follows:
 Required:
Prepare a production cost worksheet using weighted-average for the Forming department and FIFO for the Finishing department.
Required:
Prepare a production cost worksheet using weighted-average for the Forming department and FIFO for the Finishing department. (Essay)
4.9/5 (80)
(80) Spoilage that should not arise under efficient operating conditions is referred to as
(Multiple Choice)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)